
強
強気
強気 · 25%GOOGL
$268.91
シナリオ価格
$340.275
-3.845 (-1.13%)終値時点
Alphabet Inc. is a holding company. The Company's segments include Google Services, Google Cloud, and Other Bets. The Google Services segment includes products and services such as ads, Android, Chrome, devices, Google Maps, Google Play, Search, and YouTube. The Google Cloud segment includes infrastructure and platform services, collaboration tools, and other services for enterprise customers. Its Other Bets segment is engaged in the sale of healthcare-related services and Internet services. Its Google Cloud provides enterprise-ready cloud services, including Google Cloud Platform and Google Workspace. Google Cloud Platform provides access to solutions such as artificial intelligence (AI) offerings, including its AI infrastructure, Vertex AI platform, and Gemini for Google Cloud; cybersecurity, and data and analytics. Google Workspace includes cloud-based communication and collaboration tools for enterprises, such as Calendar, Gmail, Docs, Drive, and Meet.
Alphabet Inc (GOOGL) is a good buy right now due to its strong financial performance, highlighted by a gross margin of 61.65% in Q2 2026 and a significant net income of $112.1 billion in the same quarter. The stock is currently priced at $340.59, which is below analyst price targets that range from $411 to $485, indicating substantial upside potential. The main risk is the RSI of 32.63, suggesting that the stock is currently oversold, but this could also present a buying opportunity as it may rebound.
Wells Fargo
$417
2026-10-06
Wells Fargo
2026-10-06
目標株価
$417
Citi
$447
2026-10-01
Citi
2026-10-01
目標株価
$447
Tigress Financial
$485
2026-09-17
Tigress Financial
2026-09-17
目標株価
$485
Evercore ISI
$450
2026-09-16
Evercore ISI
2026-09-16
目標株価
$450
Freedom Broker
$400
2026-07-23
Freedom Broker
2026-07-23
目標株価
$400
シナリオ価格は本年の最終月次予想レンジです。確率はモデルの固定ウェイト(25 / 50 / 25)であり、保証ではありません。
SpaceX Reports Strong Q3 Results, Analysts See Growth Potential
Google Cloud Revenue Surge Could Propel Alphabet's Stock
Berkshire's Strategic Shift Post-Buffett Retirement
SpaceX Reports 161% Revenue Growth in Q3, Musk Considers Merger with Tesla
US Stock Market Faces Valuation Warnings Amidst Rising Yields
Alphabet Inc. is a holding company. The Company's segments include Google Services, Google Cloud, and Other Bets. The Google Services segment includes products and services such as ads, Android, Chrome, devices, Google Maps, Google Play, Search, and YouTube. The Google Cloud segment includes infrastructure and platform services, collaboration tools, and other services for enterprise customers. Its Other Bets segment is engaged in the sale of healthcare-related services and Internet services. Its Google Cloud provides enterprise-ready cloud services, including Google Cloud Platform and Google Workspace. Google Cloud Platform provides access to solutions such as artificial intelligence (AI) offerings, including its AI infrastructure, Vertex AI platform, and Gemini for Google Cloud; cybersecurity, and data and analytics. Google Workspace includes cloud-based communication and collaboration tools for enterprises, such as Calendar, Gmail, Docs, Drive, and Meet. It operates in the Technology sector (SERVICES-COMPUTER PROGRAMMING, DATA PROCESSING, ET industry).
Alphabet Inc (GOOGL) is a good buy right now due to its strong financial performance, highlighted by a gross margin of 61.65% in Q2 2026 and a significant net income of $112.1 billion in the same quarter. The stock is currently priced at $340.59, which is below analyst price targets that range from $411 to $485, indicating substantial upside potential. The main risk is the RSI of 32.63, suggesting that the stock is currently oversold, but this could also present a buying opportunity as it may rebound.
43 analysts cover GOOGL: 38 rate it Buy, 5 Hold and 0 Sell. The average price target is 374.25.
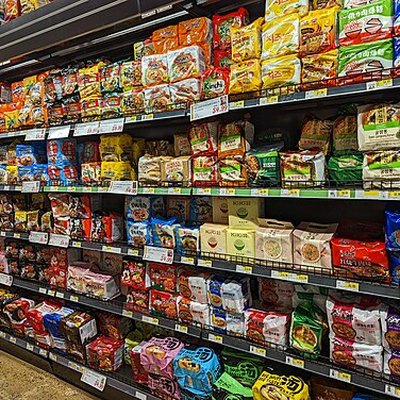
$GOOGL is back below its 200-day moving average while its relative strength line continues to decline.
もっと見る
Netflix earned $0.87 per share, beating expectations, yet fell 5.7% after hours to 64.78, breaking below the post-earnings low from July. I'm not catching this falling knife. What I see: Q3 revenue was $12.87 billion, up nearly 12% year over year and in line with expectations; profit beat, but the company itself said part of that was due to timing shifts in expense recognition. Q4 revenue guidance is $13.44 billion, below the market expectation of $13.51 billion; full-year guidance is $51.1 billion, at the low end of the original range. Q4 margin guidance is about 26%, down sharply from 34.6% in Q3, and restructuring costs will be included. I think the market doesn't care how much was earned this quarter; it cares that growth keeps slowing and viewing time is being taken by YouTube and short-form video. Profit propped up by shifting expenses around will have to be paid back next quarter. What I'll do: no bottom-fishing; wait for the official U.S. market open tonight. A close back above 68.69 would mean the bad news has been absorbed; if it can't hold the July low of 65.08 on a close, that's a new leg down. Netflix is at just over 64 after hours. Would you buy at that price at tonight's open, yes or no? $NFLX $GOOGL #EarningsSeason #Netflix
もっと見る
Google search interest in "Crypto" has dropped quickly during this pullback. Sentiment toward #Altcoins has fallen into a slump again. 😂
もっと見る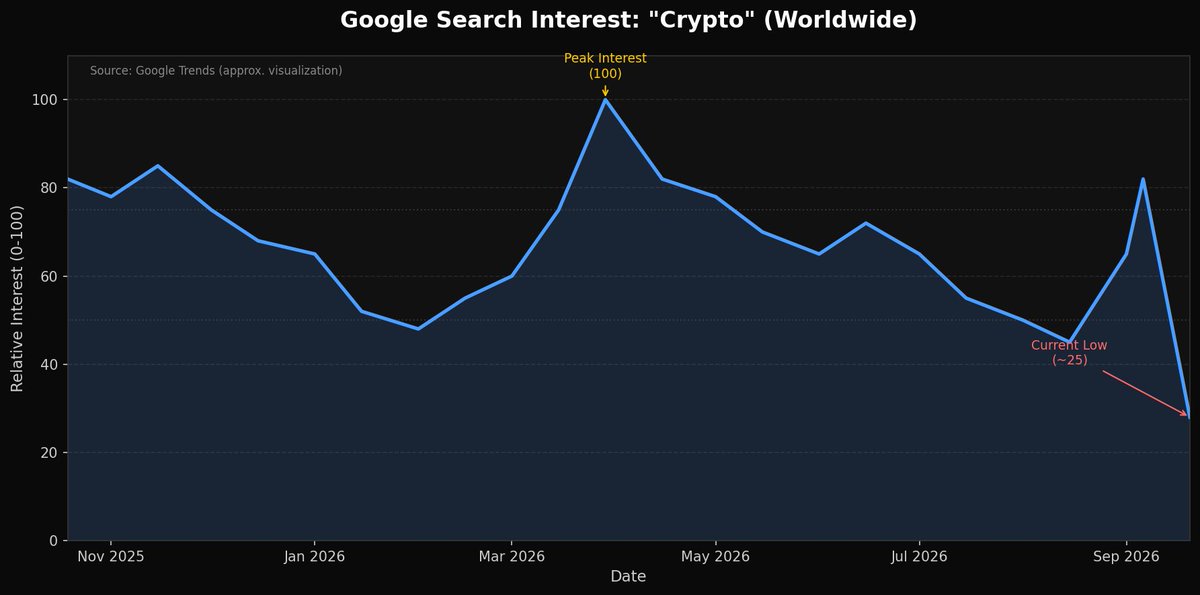
本ページは調査目的であり、投資助言ではありません。モデルは誤ることがあります。過去の実績は将来の成果を保証しません。