
乐
乐观
乐观 · 25%TSM
$272.63
情景价格
$445.120
+0.757 (+0.17%)收盘时
Taiwan Semiconductor Manufacturing Co Ltd is a Taiwan-based integrated circuit foundry service provider. The Company is primarily engaged in integrated circuit manufacturing services. It offers advanced process technologies, specialised process solutions, advanced photomask and silicon stacking, and packaging-related technologies, while supporting a comprehensive design ecosystem. The Company's products serve diverse electronic sectors including artificial intelligence, high-performance computing, wired and wireless communications, automotive and industrial equipment, personal computing, information applications, consumer electronics, smart internet of things, and wearable devices.
TSMC is a good buy right now due to its current price of $453.31, a low forward P/E ratio of 21.41, and a gross margin of 67.72%. The company has shown significant revenue growth, with a 34% year-over-year increase in Q2, and holds a dominant 72.5% market share in the semiconductor foundry market. However, a potential risk is the RSI of 39.48, indicating the stock may be oversold, which could lead to short-term volatility.
Citi
—
2026-10-07
Citi
2026-10-07
目标价
—
Stifel
—
2026-09-01
Stifel
2026-09-01
目标价
—
Needham
$530
2026-07-27
Needham
2026-07-27
目标价
$530
TD Cowen
$440
2026-07-17
TD Cowen
2026-07-17
目标价
$440
DA Davidson
$500
2026-07-17
DA Davidson
2026-07-17
目标价
$500
情景价格取自当年最后一个月度预测区间。概率为固定的模型权重(25 / 50 / 25),不构成保证。
TSMC Benefits from Global Chip Boom
Taiwan Semiconductor's Q3 Earnings Preview Shows Strong Growth
Accelerating Semiconductor Demand Driven by AI Infrastructure Investments
Custom Processors Surge Driving AI Market Growth
TSMC Stock Continues to Rise, Promising Future Ahead
Taiwan Semiconductor Manufacturing Co Ltd is a Taiwan-based integrated circuit foundry service provider. The Company is primarily engaged in integrated circuit manufacturing services. It offers advanced process technologies, specialised process solutions, advanced photomask and silicon stacking, and packaging-related technologies, while supporting a comprehensive design ecosystem. The Company's products serve diverse electronic sectors including artificial intelligence, high-performance computing, wired and wireless communications, automotive and industrial equipment, personal computing, information applications, consumer electronics, smart internet of things, and wearable devices. It operates in the Technology sector.
TSMC is a good buy right now due to its current price of $453.31, a low forward P/E ratio of 21.41, and a gross margin of 67.72%. The company has shown significant revenue growth, with a 34% year-over-year increase in Q2, and holds a dominant 72.5% market share in the semiconductor foundry market. However, a potential risk is the RSI of 39.48, indicating the stock may be oversold, which could lead to short-term volatility.
6 analysts cover TSM: 1 rate it Buy, 5 Hold and 0 Sell. The average price target is 313.46.
$TSM Q3 '26 Earnings Results & Recap TSMC reported 3Q26 revenue of NT$1.49T, up 50.9% year over year; net income was NT$763.06B, up 68.7%, diluted EPS was NT$29.43, and gross margin was 66.4%.
展开
If you missed September, don't miss October 🔥 We're already halfway through the month, right at the most active period of the market. Seize the opportunity to recover what was lost before, or push toward even greater heights. Time waits for no one, but in life you really only need to catch one or two opportunities — that's enough. #ASML and #TSMC are about to release Q3 earnings.
展开
What are we talking about today? Gate Square's trending topics have been updated. US September CPI will be released tonight. Will the inflation data once again change the trading pace for $BTC and US stocks? Gate's derivatives market share has risen to 10.1%, the largest global increase in September. Can this growth continue? ASML and TSMC's Q3 earnings will be released soon. Will the semiconductor supply chain see a new round of repricing? Quality content may receive traffic support and featured recommendations. What are your thoughts? Join the discussion:
展开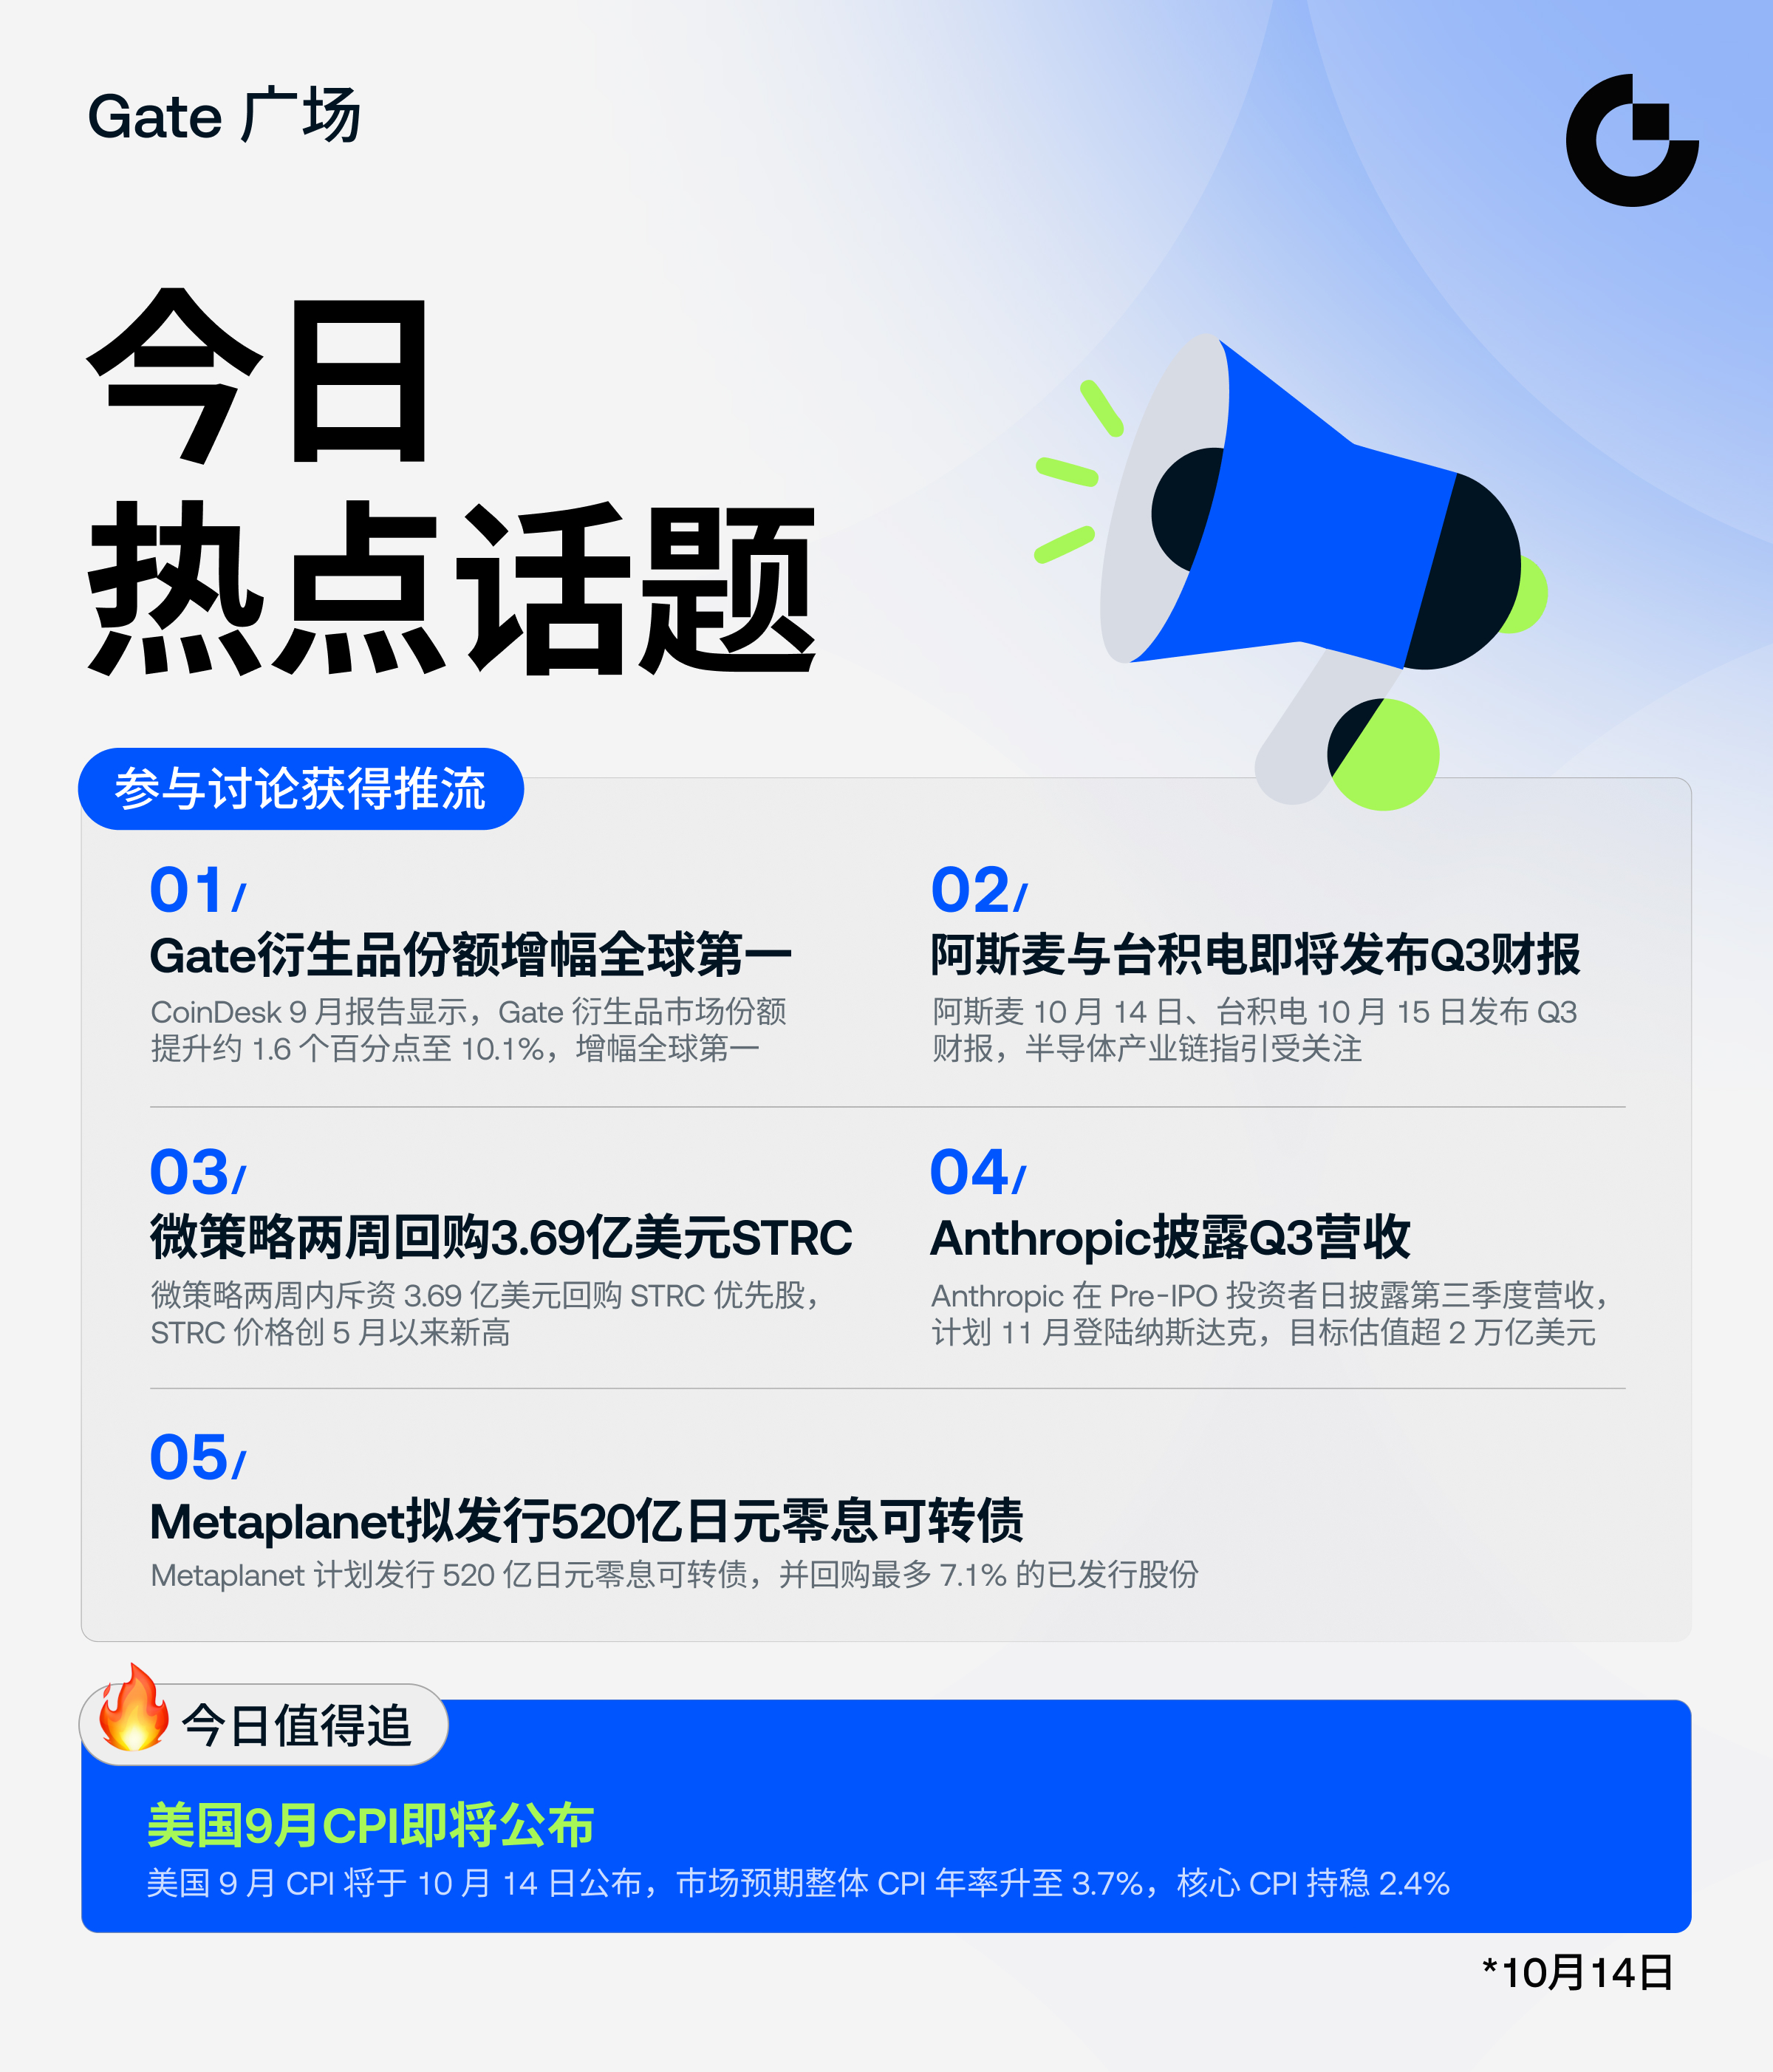
🔥 What are we talking about today? Gate Square's trending topics have been updated! 🔹 US September CPI is released tonight — will the inflation data once again change the trading rhythm for $BTC and US stocks? 🔹 Gate's derivatives market share rose to 10.1%, the largest global increase in September — can this growth continue? 🔹 ASML and TSMC Q3 earnings are coming up one after another — will the semiconductor supply chain see a new round of pricing? Quality content can receive traffic support + featured recommendations. 💰 Have a view? Come join the discussion:
展开
What signal does Microsoft's heavily funded in-house Maia 300 chip actually send? Recently, Microsoft $MSFT unveiled its third-generation in-house AI chip, Maia 300. The key compute section directly uses TSMC's $TSM 2nm process and is paired with 288GB of HBM4 memory. This is not just about saving money; it also reflects the deep concern among tech giants about Nvidia's $NVDA hardware monopoly. From a technical route perspective, Nvidia $NVDA tends to use very large monolithic chips with high-bandwidth memory, while Microsoft $MSFT is pursuing a multi-chip small-chiplet approach, using 2nm for the core and lower-cost 3nm for other auxiliary parts. This design allows flexible cost control and is better suited to handling large-scale long-text inference tasks in the cloud. However, the biggest challenge for in-house chips has never been on-paper specs, but ecosystem compatibility and speed of deployment. Although there are reports of an ambitious goal to deploy over a million units next year, truly challenging the software moat Nvidia $NVDA has built over many years will still be a hard battle in the short term. I think cloud providers making chips is ultimately not about completely replacing anyone, but about having leverage when negotiating with Nvidia $NVDA. Next, in-house chips from major companies will move from behind the scenes to the forefront, forcing the entire hardware supply chain to accelerate competition. From this wave of in-house chip development and the supply chain landscape: ▶️ Microsoft $MSFT In-house chips reduce costs and improve efficiency, the cloud and AI ecosystem is solid, and the medium- to long-term trend looks favorable. ▶️ Nvidia $NVDA In the short term, its ecosystem monopoly advantage is strong and growth is sufficient. In the medium to long term, it faces pressure from major companies' in-house chips diverting demand. ▶️ TSMC $TSM It benefits from advanced process dividends, foundry demand is solid, and performance is highly certain. DYOR
展开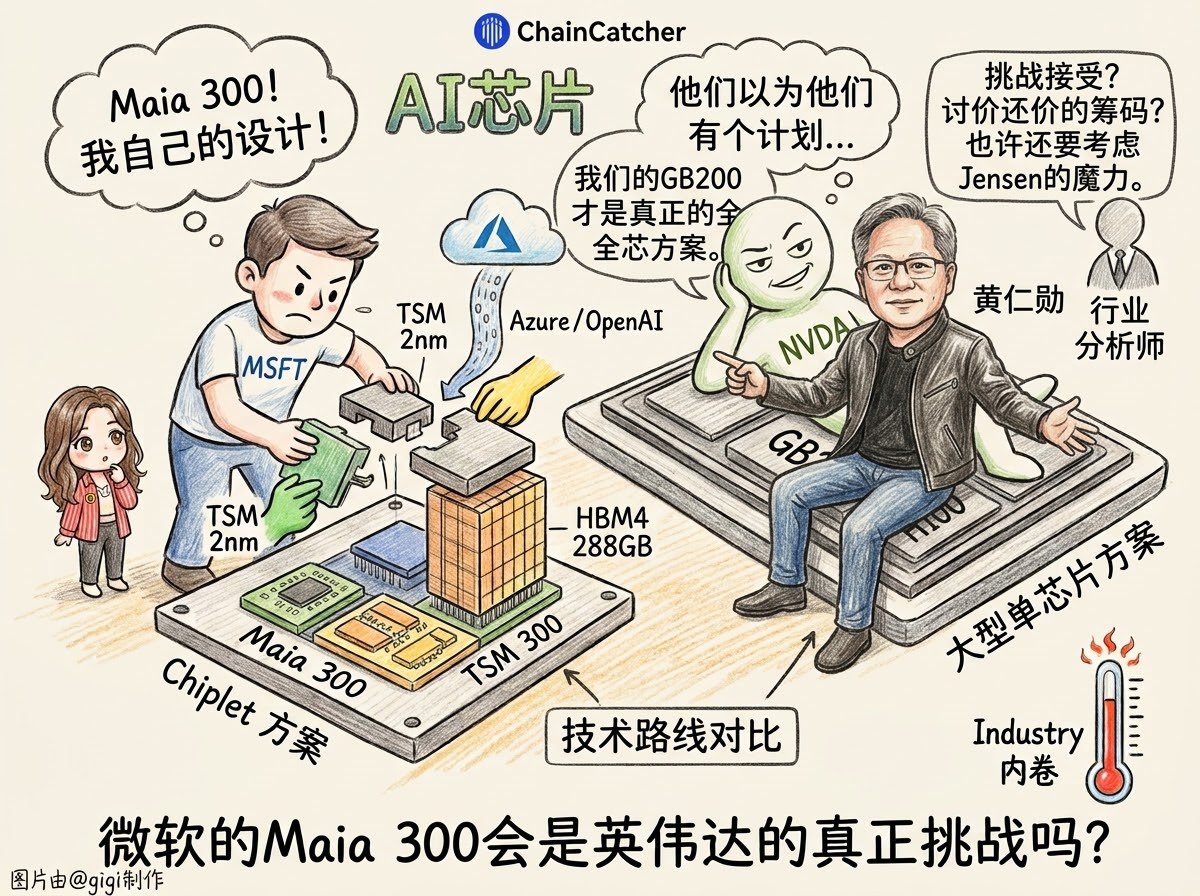
本页仅供研究参考,不构成投资建议。模型可能出错。过往表现不代表未来结果。