強
強気
強気 · 25%TSM
$272.63
シナリオ価格
$430.000
-14.620 (-3.40%)終値時点
Taiwan Semiconductor Manufacturing Co Ltd is a Taiwan-based integrated circuit foundry service provider. The Company is primarily engaged in integrated circuit manufacturing services. It offers advanced process technologies, specialised process solutions, advanced photomask and silicon stacking, and packaging-related technologies, while supporting a comprehensive design ecosystem. The Company's products serve diverse electronic sectors including artificial intelligence, high-performance computing, wired and wireless communications, automotive and industrial equipment, personal computing, information applications, consumer electronics, smart internet of things, and wearable devices.
TSMC is a good buy right now due to its current price of $453.31, a low forward P/E ratio of 21.41, and a gross margin of 67.72%. The company has shown significant revenue growth, with a 34% year-over-year increase in Q2, and holds a dominant 72.5% market share in the semiconductor foundry market. However, a potential risk is the RSI of 39.48, indicating the stock may be oversold, which could lead to short-term volatility.
Citi
—
2026-10-07
Citi
2026-10-07
目標株価
—
Stifel
—
2026-09-01
Stifel
2026-09-01
目標株価
—
Needham
$530
2026-07-27
Needham
2026-07-27
目標株価
$530
TD Cowen
$440
2026-07-17
TD Cowen
2026-07-17
目標株価
$440
DA Davidson
$500
2026-07-17
DA Davidson
2026-07-17
目標株価
$500
シナリオ価格は本年の最終月次予想レンジです。確率はモデルの固定ウェイト(25 / 50 / 25)であり、保証ではありません。
Taiwan Semiconductor Manufacturing Co Ltd is a Taiwan-based integrated circuit foundry service provider. The Company is primarily engaged in integrated circuit manufacturing services. It offers advanced process technologies, specialised process solutions, advanced photomask and silicon stacking, and packaging-related technologies, while supporting a comprehensive design ecosystem. The Company's products serve diverse electronic sectors including artificial intelligence, high-performance computing, wired and wireless communications, automotive and industrial equipment, personal computing, information applications, consumer electronics, smart internet of things, and wearable devices. It operates in the Technology sector.
TSMC is a good buy right now due to its current price of $453.31, a low forward P/E ratio of 21.41, and a gross margin of 67.72%. The company has shown significant revenue growth, with a 34% year-over-year increase in Q2, and holds a dominant 72.5% market share in the semiconductor foundry market. However, a potential risk is the RSI of 39.48, indicating the stock may be oversold, which could lead to short-term volatility.
6 analysts cover TSM: 1 rate it Buy, 5 Hold and 0 Sell. The average price target is 313.46.
$TSM breaks its silence on Terafab and insists on operational control. TSMC CEO C.C. Wei confirmed that the company is in preliminary discussions with Elon Musk's Terafab initiative about potentially using its planned semiconductor manufacturing capacity. No agreement has been reached yet, and Wei stressed that any fab involving cooperation must be operated by TSMC. TSMC has also sent a team to Texas to assess potential expansion opportunities beyond Arizona, driven by growing demand from U.S. customers.
もっと見る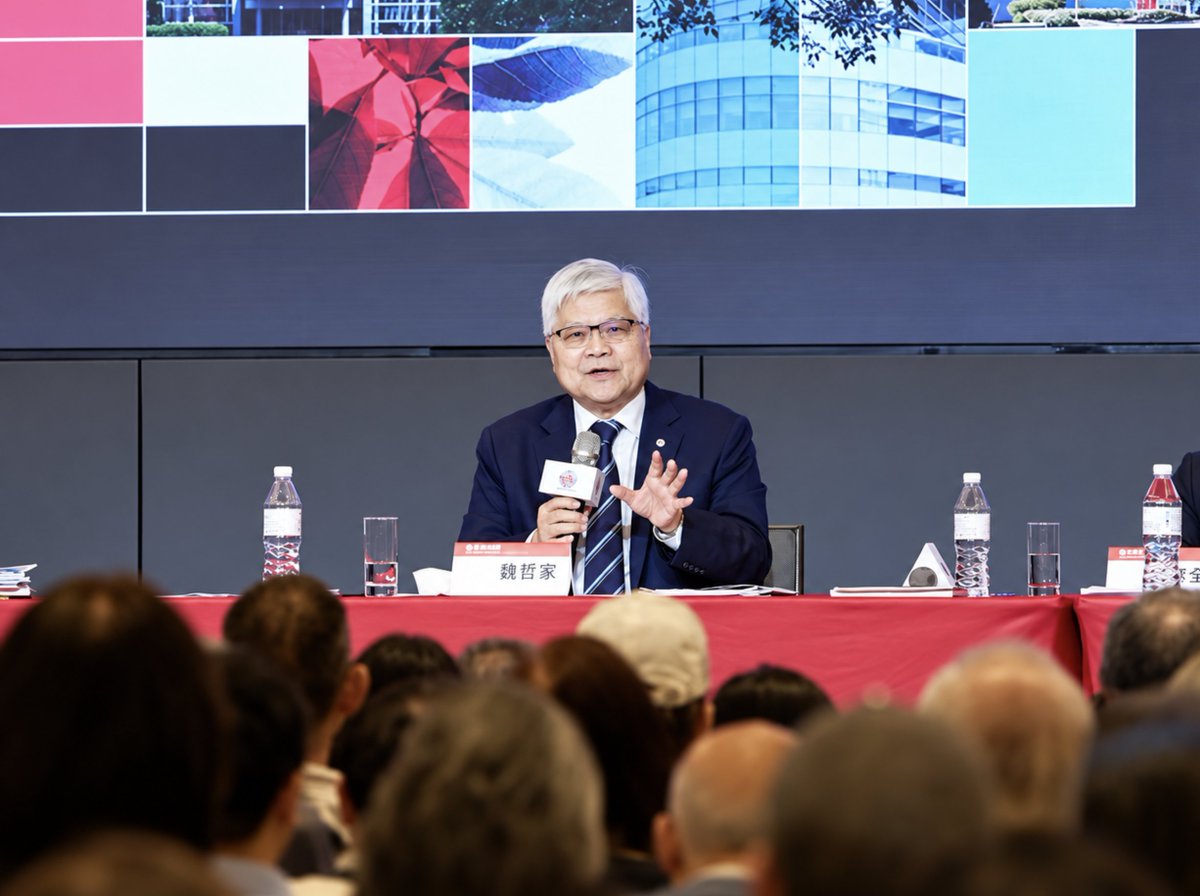
TSMC's latest earnings showed profit surging nearly 70%, so why did the stock fall instead? $TSM Looking at TSMC's just-released Q3 earnings, revenue topped NT$1.49 trillion, net profit jumped to NT$763.1 billion, up nearly 69% year over year, beating market expectations across the board. The share of 2nm and advanced process nodes is very high, and demand for AI chips remains solid. What's interesting is that after the strong results were announced, the market dipped slightly. The market isn't worried about whether it can make money, but is starting to question its highly ambitious capital expenditure plans. This year TSMC's capex has been pushed directly to $64 billion, and in the coming years it could even reach an astronomical figure around $80 billion. With nearly 20 fabs being rolled out globally at the same time, this unprecedented pace of expansion means extremely high depreciation costs and diluted management from overseas plant construction. Also, gross margin guidance was slightly adjusted, and the market is starting to watch out for overcapacity and declining marginal returns on AI investment. The expectation is that TSMC's short-term logic is monopoly premium, with no one able to replace it, but its medium- to long-term logic will shift from the AI dividend period to a capacity digestion period. Once the major tech giants' AI spending enters a stage of refined cost calculation, huge capital expenditure will become a double-edged sword. Earnings are at a peak, but the alarm bells of running too fast are also ringing. DYOR
もっと見る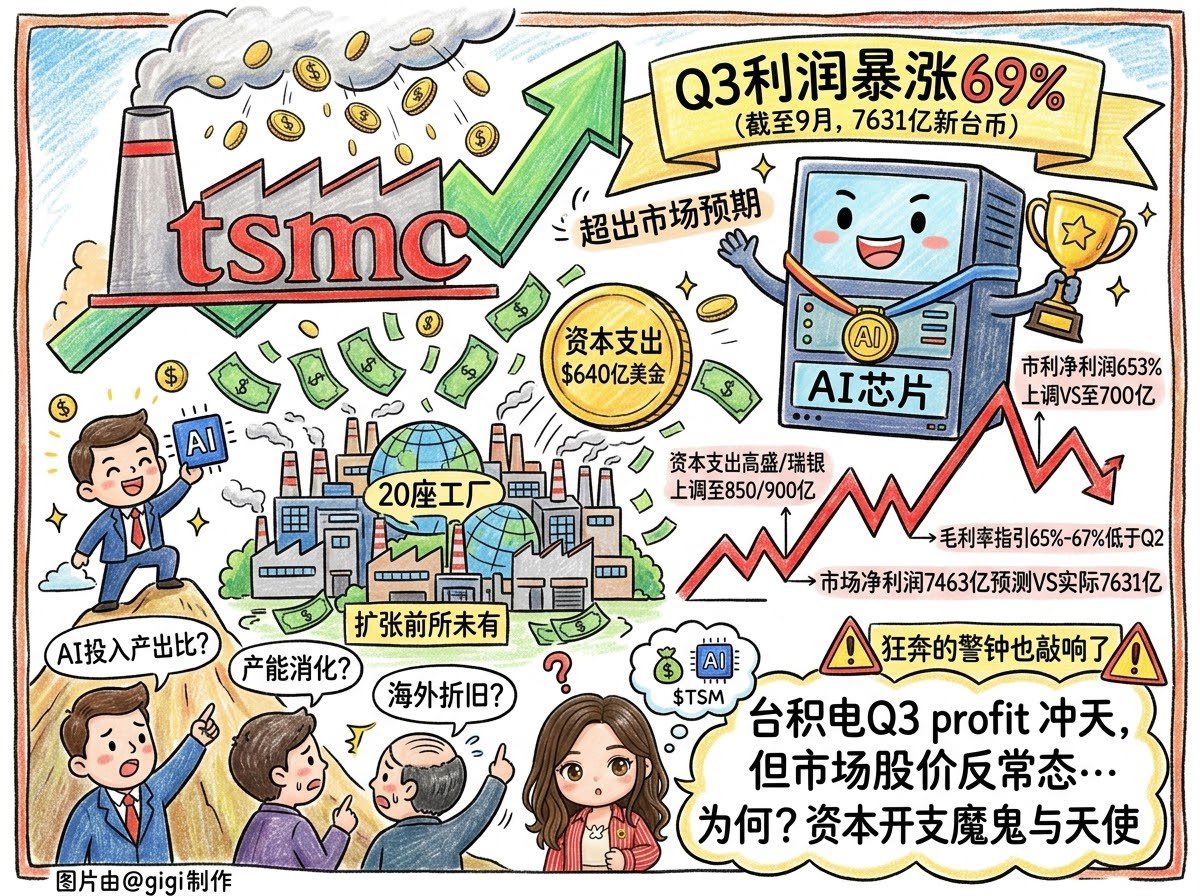
$TSM Q3 '26 Earnings Results & Recap TSMC reported 3Q26 revenue of NT$1.49T, up 50.9% year over year; net income was NT$763.06B, up 68.7%, diluted EPS was NT$29.43, and gross margin was 66.4%.
もっと見る
If you missed September, don't miss October 🔥 We're already halfway through the month, right at the most active period of the market. Seize the opportunity to recover what was lost before, or push toward even greater heights. Time waits for no one, but in life you really only need to catch one or two opportunities — that's enough. #ASML and #TSMC are about to release Q3 earnings.
もっと見る
What are we talking about today? Gate Square's trending topics have been updated. US September CPI will be released tonight. Will the inflation data once again change the trading pace for $BTC and US stocks? Gate's derivatives market share has risen to 10.1%, the largest global increase in September. Can this growth continue? ASML and TSMC's Q3 earnings will be released soon. Will the semiconductor supply chain see a new round of repricing? Quality content may receive traffic support and featured recommendations. What are your thoughts? Join the discussion:
もっと見る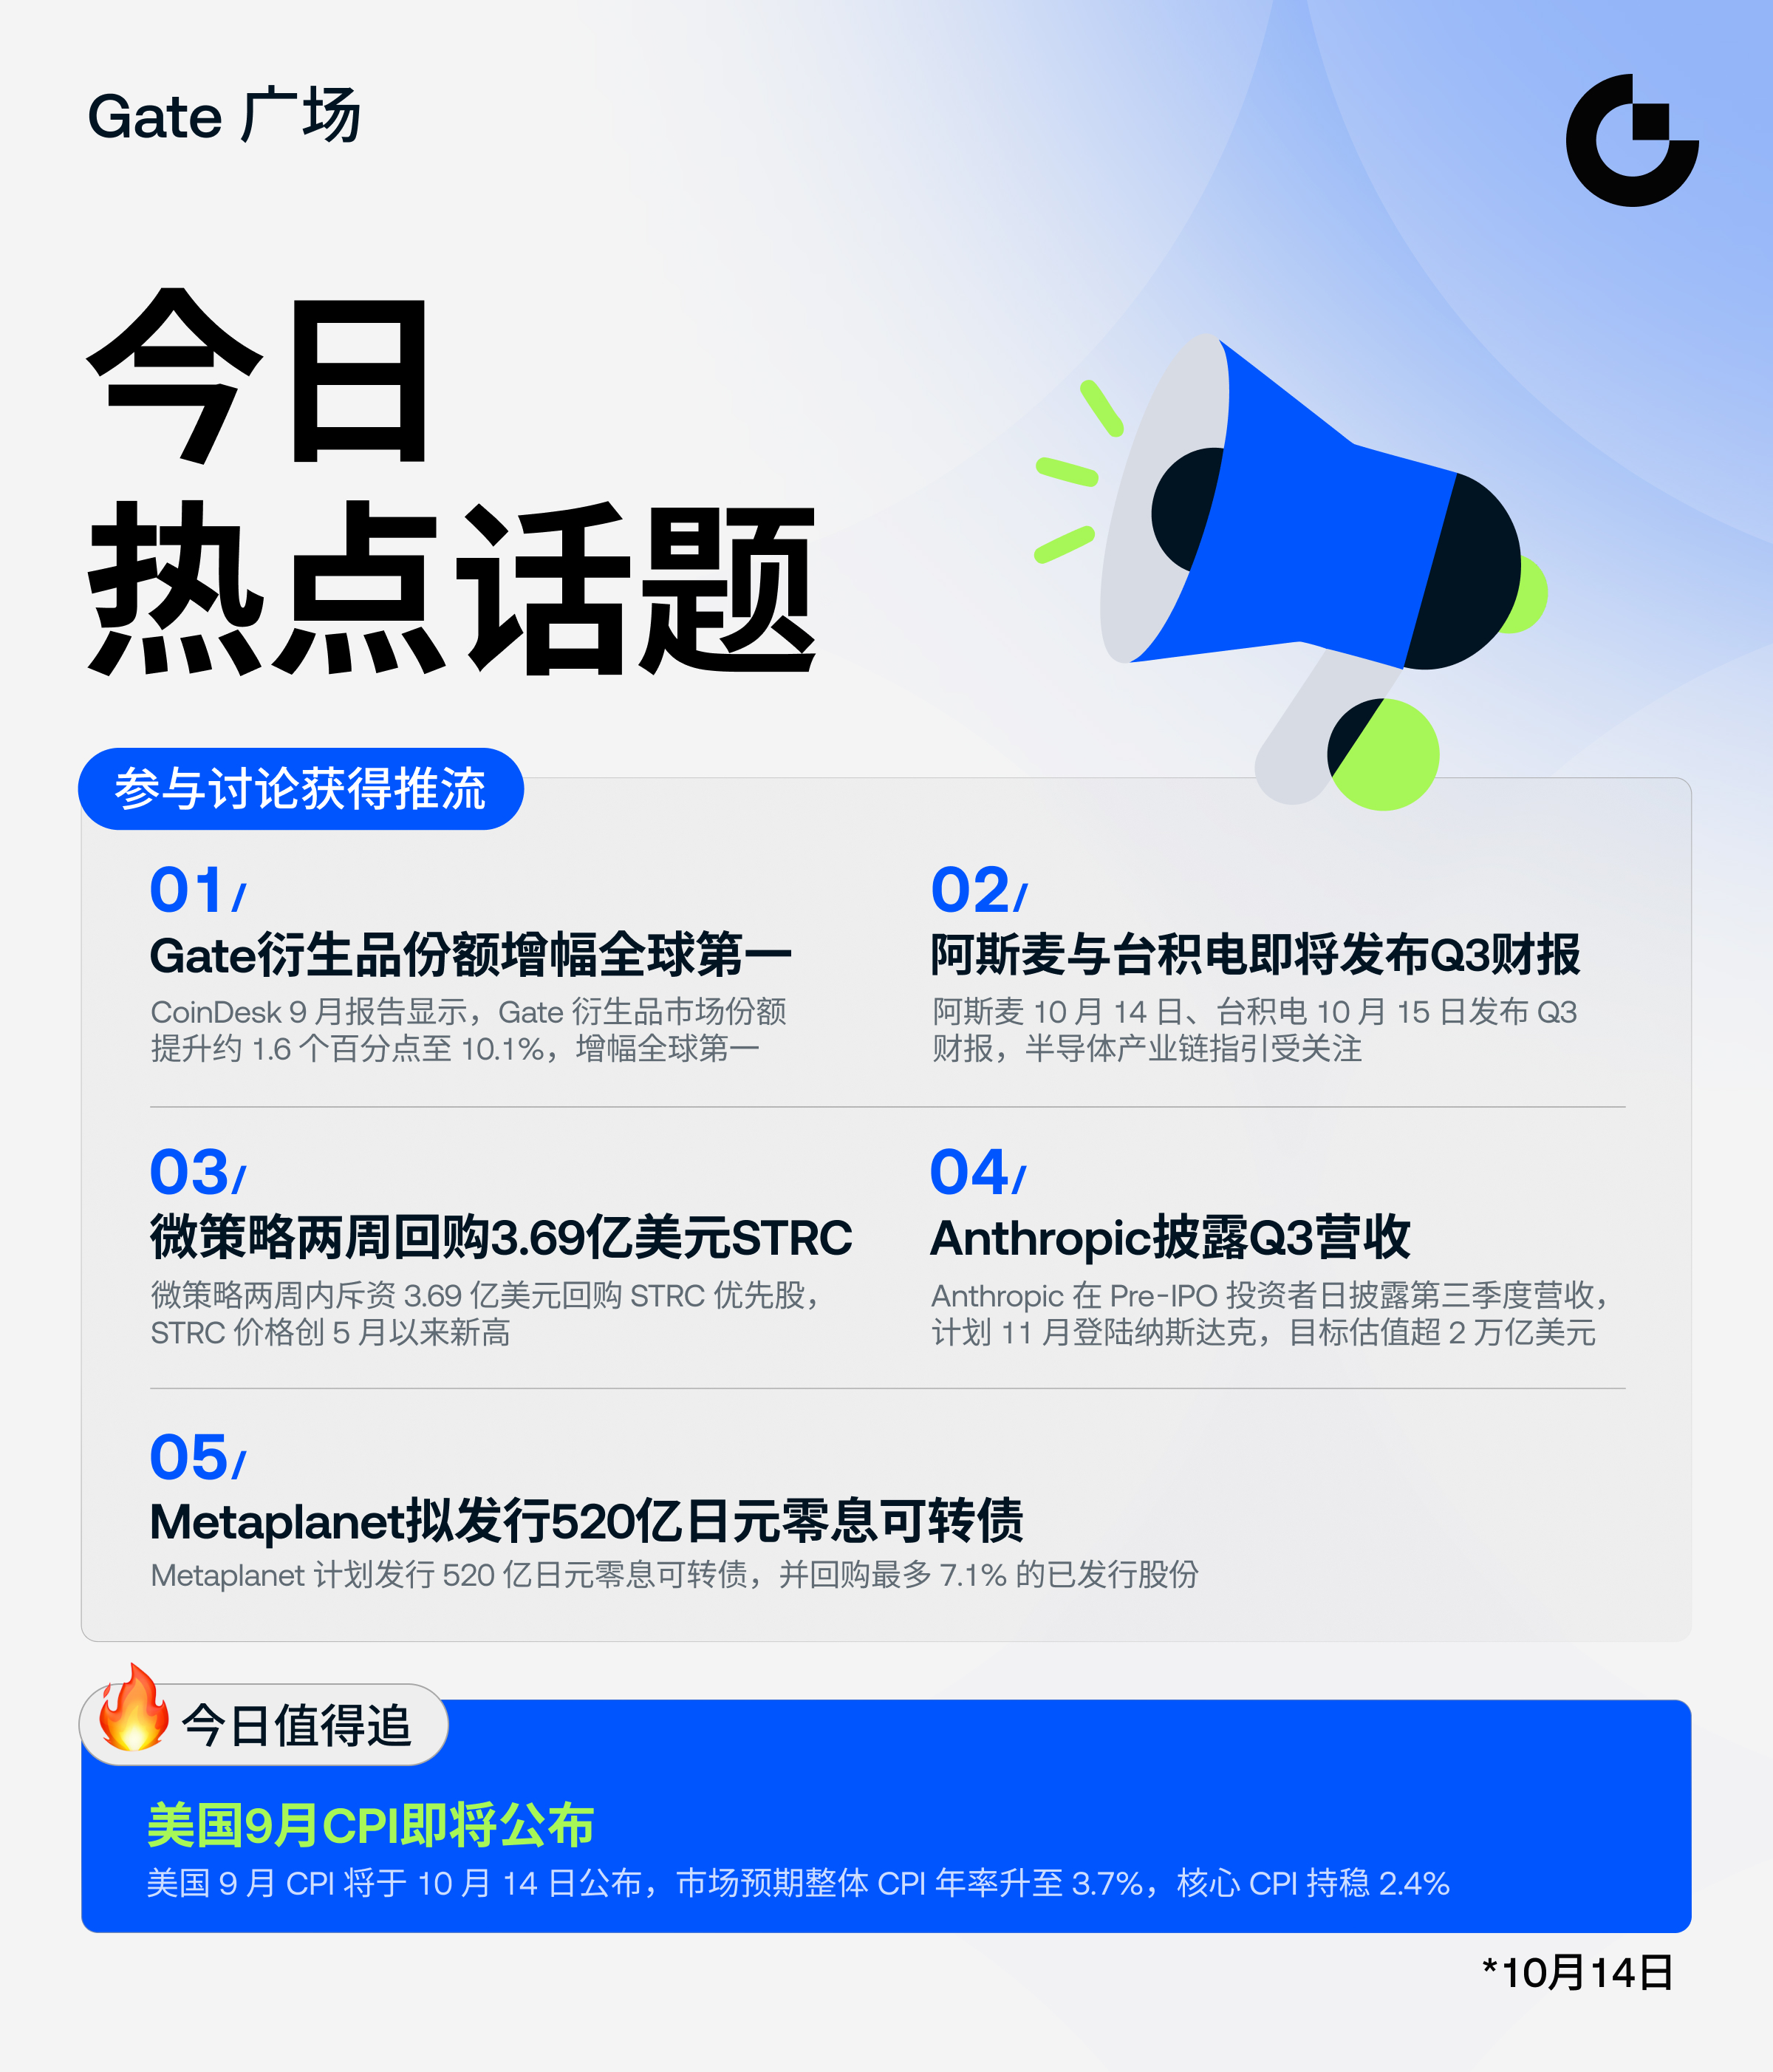
本ページは調査目的であり、投資助言ではありません。モデルは誤ることがあります。過去の実績は将来の成果を保証しません。