
樂
樂觀
樂觀 · 25%GOOGL
$268.91
情境價格
$320.210
-3.971 (-1.24%)收盤時
Alphabet Inc. is a holding company. The Company's segments include Google Services, Google Cloud, and Other Bets. The Google Services segment includes products and services such as ads, Android, Chrome, devices, Google Maps, Google Play, Search, and YouTube. The Google Cloud segment includes infrastructure and platform services, collaboration tools, and other services for enterprise customers. Its Other Bets segment is engaged in the sale of healthcare-related services and Internet services. Its Google Cloud provides enterprise-ready cloud services, including Google Cloud Platform and Google Workspace. Google Cloud Platform provides access to solutions such as artificial intelligence (AI) offerings, including its AI infrastructure, Vertex AI platform, and Gemini for Google Cloud; cybersecurity, and data and analytics. Google Workspace includes cloud-based communication and collaboration tools for enterprises, such as Calendar, Gmail, Docs, Drive, and Meet.
Alphabet Inc (GOOGL) is a good buy right now due to its strong financial performance, highlighted by a gross margin of 61.65% in Q2 2026 and a significant net income of $112.1 billion in the same quarter. The stock is currently priced at $340.59, which is below analyst price targets that range from $411 to $485, indicating substantial upside potential. The main risk is the RSI of 32.63, suggesting that the stock is currently oversold, but this could also present a buying opportunity as it may rebound.
Wells Fargo
$417
2026-10-06
Wells Fargo
2026-10-06
目標價
$417
Citi
$447
2026-10-01
Citi
2026-10-01
目標價
$447
Tigress Financial
$485
2026-09-17
Tigress Financial
2026-09-17
目標價
$485
Evercore ISI
$450
2026-09-16
Evercore ISI
2026-09-16
目標價
$450
Freedom Broker
$400
2026-07-23
Freedom Broker
2026-07-23
目標價
$400
情境價格取自當年最後一個月度預測區間。機率為固定的模型權重(25 / 50 / 25),不構成保證。

Concerns Over AI Trade Weigh on Nasdaq Performance
AI Infrastructure Market Turmoil Intensifies
Major Risks Loom for Stock Market Next Week Amid AI Trade Stumbles
Apple Set to Surpass Nvidia, Reclaim Title as World's Largest Company
Stocks Decline on Friday as Oil Prices Surge Amid Middle East Tensions
Alphabet Inc. is a holding company. The Company's segments include Google Services, Google Cloud, and Other Bets. The Google Services segment includes products and services such as ads, Android, Chrome, devices, Google Maps, Google Play, Search, and YouTube. The Google Cloud segment includes infrastructure and platform services, collaboration tools, and other services for enterprise customers. Its Other Bets segment is engaged in the sale of healthcare-related services and Internet services. Its Google Cloud provides enterprise-ready cloud services, including Google Cloud Platform and Google Workspace. Google Cloud Platform provides access to solutions such as artificial intelligence (AI) offerings, including its AI infrastructure, Vertex AI platform, and Gemini for Google Cloud; cybersecurity, and data and analytics. Google Workspace includes cloud-based communication and collaboration tools for enterprises, such as Calendar, Gmail, Docs, Drive, and Meet. It operates in the Technology sector (SERVICES-COMPUTER PROGRAMMING, DATA PROCESSING, ET industry).
Alphabet Inc (GOOGL) is a good buy right now due to its strong financial performance, highlighted by a gross margin of 61.65% in Q2 2026 and a significant net income of $112.1 billion in the same quarter. The stock is currently priced at $340.59, which is below analyst price targets that range from $411 to $485, indicating substantial upside potential. The main risk is the RSI of 32.63, suggesting that the stock is currently oversold, but this could also present a buying opportunity as it may rebound.
43 analysts cover GOOGL: 38 rate it Buy, 5 Hold and 0 Sell. The average price target is 374.25.
Hello everyone. Looking at today's market, as Big Tech earnings season is in full swing, it is clear that the market is at a particularly sensitive juncture. Tesla and Meta's results offer important clues not only for these two companies but also for the future of the entire AI ecosystem. Let us examine this situation with a calm mind from an investor's perspective. First, let us answer the question everyone is asking: do earnings beats always drive stock prices higher? The short answer is: no, absolutely not. In fact, according to recent Zacks research, nearly half (47.3%) of stocks that beat expectations still closed lower on the following trading day. Meta is a recent example. Although the company's revenue reached $64.6 billion, beating expectations and growing 26%, its stock price still faced downward pressure due to rising AI investment costs (2026 capex is projected at $135-145 billion) and one-time legal expenses. The market is no longer just asking "how much did you earn?" but "how effectively are you spending those earnings?" Tesla's situation is slightly different. Although both revenue and EPS beat expectations, its stock fell 3% in after-hours trading. The main reasons are fluctuations in automotive business margins and the fact that the autonomous driving (Robotaxi) narrative has not yet been materially reflected in the company's financial statements. So can AI investment deliver sustainable long-term growth? Over the past few weeks, this question is precisely what has kept the market volatile. Gartner analysts raised a compelling point: mathematically, the AI-related capital expenditure (capex) planned from 2027 to 2030 appears difficult to fully cover with the AI revenue expected from these investments. Meta's stock recently fell more than 7%, and Nvidia fell 4%, essentially because investors are asking: "So much money has been spent—when will it pay off?" However, let us not forget that the AI transformation is a marathon, not a sprint. Short-term profit-taking does not mean the long-term trend is over. Now to the core question: which tech giant am I most optimistic about? For me, the star of this earnings season will be the cloud business segment. Microsoft, Alphabet, and Amazon are scheduled to report results on October 28-29. CFRA analysts expect Google Cloud's growth rate to be between 85% and 90%, a clear sign that AI investment is beginning to translate into tangible revenue. If cloud revenue meets or exceeds expectations, market confidence in AI spending may recover. Apple and Nvidia also deserve special attention. Apple will report on November 2, which will reveal consumer demand for AI and hardware margins. Meanwhile, Nvidia will report on November 18, when we will get the clearest picture of the chip demand underpinning all these investments. In short, friends, the market is currently in a "digestion" phase. The AI narrative remains compelling, but investors now want to see actual financial returns from that narrative. Do not be intimidated by short-term volatility. What matters is being able to see traces of AI investment in these companies' balance sheets. I personally am eagerly awaiting the data the cloud giants will release next week. Do not make decisions based on headlines alone; be sure to do your own research. This article does not constitute investment advice. #ShareWeekly #USEarningsSeason
展開
$GOOGL going to zero, head for the exit and hand me your shares on the way out.
展開
$GOOGL is back below its 200-day moving average while its relative strength line continues to decline.
展開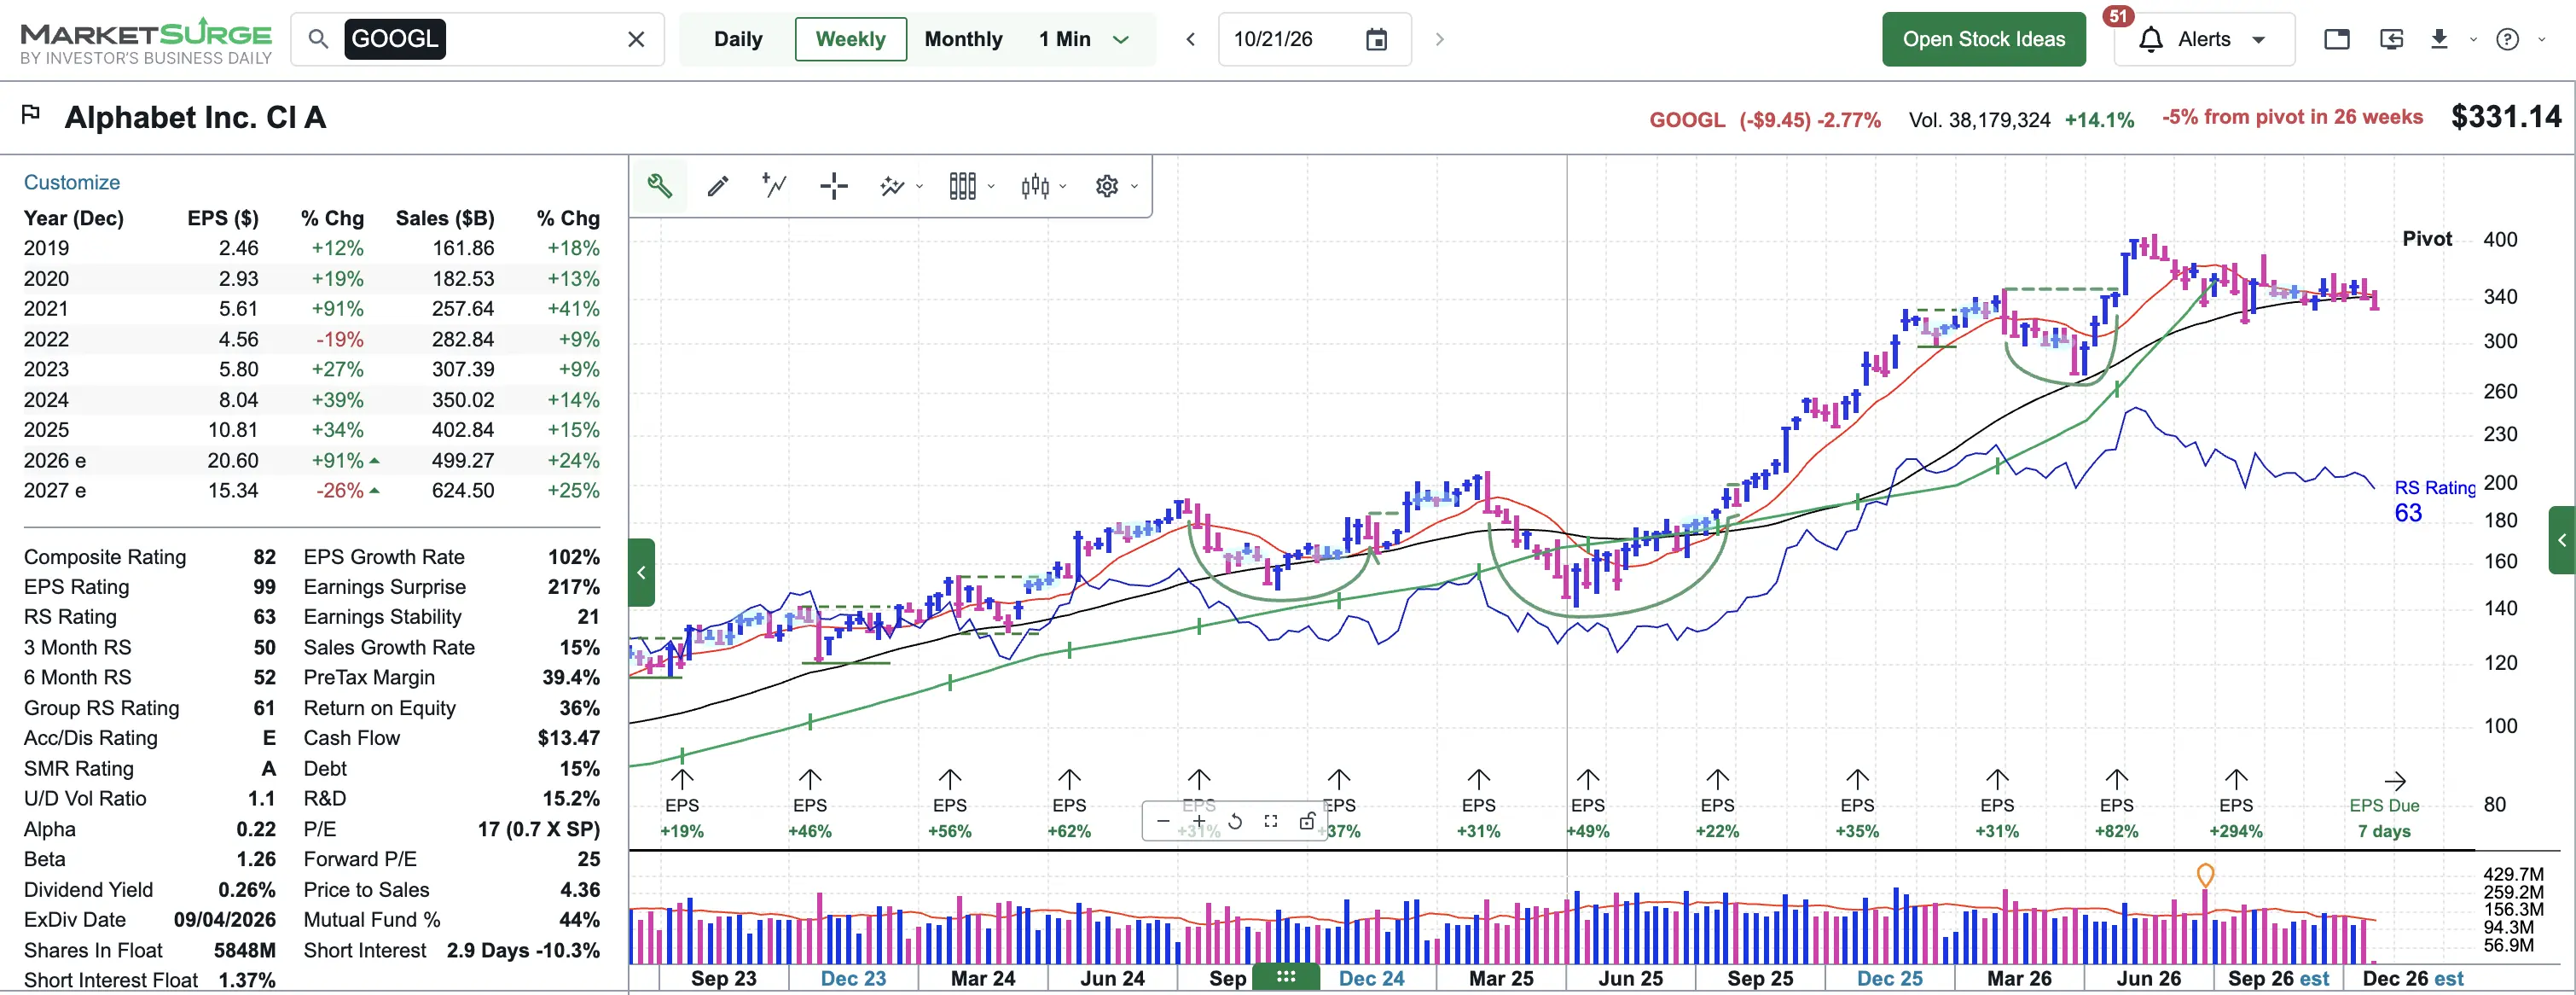
Netflix earned $0.87 per share, beating expectations, yet fell 5.7% after hours to 64.78, breaking below the post-earnings low from July. I'm not catching this falling knife. What I see: Q3 revenue was $12.87 billion, up nearly 12% year over year and in line with expectations; profit beat, but the company itself said part of that was due to timing shifts in expense recognition. Q4 revenue guidance is $13.44 billion, below the market expectation of $13.51 billion; full-year guidance is $51.1 billion, at the low end of the original range. Q4 margin guidance is about 26%, down sharply from 34.6% in Q3, and restructuring costs will be included. I think the market doesn't care how much was earned this quarter; it cares that growth keeps slowing and viewing time is being taken by YouTube and short-form video. Profit propped up by shifting expenses around will have to be paid back next quarter. What I'll do: no bottom-fishing; wait for the official U.S. market open tonight. A close back above 68.69 would mean the bad news has been absorbed; if it can't hold the July low of 65.08 on a close, that's a new leg down. Netflix is at just over 64 after hours. Would you buy at that price at tonight's open, yes or no? $NFLX $GOOGL #EarningsSeason #Netflix
展開本頁僅供研究參考,不構成投資建議。模型可能出錯。過往表現不代表未來結果。