
乐
乐观
乐观 · 25%STX
$185.26
情景价格
$639.010
-47.926 (-7.50%)收盘时
Seagate Technology Holdings plc provides mass-data storage infrastructure solution. The Company’s principal products are hard disk drives, commonly referred to as disk drives, hard drives (HDDs). In addition to HDDs, the Company produces a range of data storage products, including solid state drives (SSDs), solid state hybrid drives, storage subsystems, as well as a scalable edge-to-cloud mass data platform. Its HDD products are designed for mass capacity storage and legacy markets. Mass capacity storage involves use cases, such as hyperscale data centers and public clouds, as well as emerging use cases. The Company’s HDD and SSD product portfolio includes Serial Advanced Technology Attachment, Serial Attached SCSI and Non-Volatile Memory Express based designs to support a variety of mass capacity and legacy applications. Its systems portfolio includes storage subsystems for enterprises, cloud service providers, scale-out storage servers and original equipment manufacturers.
Seagate Technology Holdings PLC is currently trading at $639.01, which is significantly below its recent price target of $865 set by Wells Fargo. However, the stock has a low RSI of 11.83, indicating it is oversold, but the recent 5-day change of -18.39% suggests continued selling pressure. The company's gross margin has improved to 52.30%, and it reported a strong revenue growth of 34% year-over-year, which are positive signs for long-term investors. The main risk is the recent insider selling activity, which has increased by 345% over the last month, indicating potential lack of confidence from insiders.
Bernstein
—
2026-10-03
Bernstein
2026-10-03
目标价
—
Morgan Stanley
—
2026-10-02
Morgan Stanley
2026-10-02
目标价
—
Rosenblatt
—
2026-10-02
Rosenblatt
2026-10-02
目标价
—
Argus
$900
2026-07-30
Argus
2026-07-30
目标价
$900
TD Cowen
$850
2026-07-29
TD Cowen
2026-07-29
目标价
$850
情景价格取自当年最后一个月度预测区间。概率为固定的模型权重(25 / 50 / 25),不构成保证。
Market Volatility Amid Strong Bank Earnings
Wells Fargo Lowers Price Targets for Western Digital and Seagate
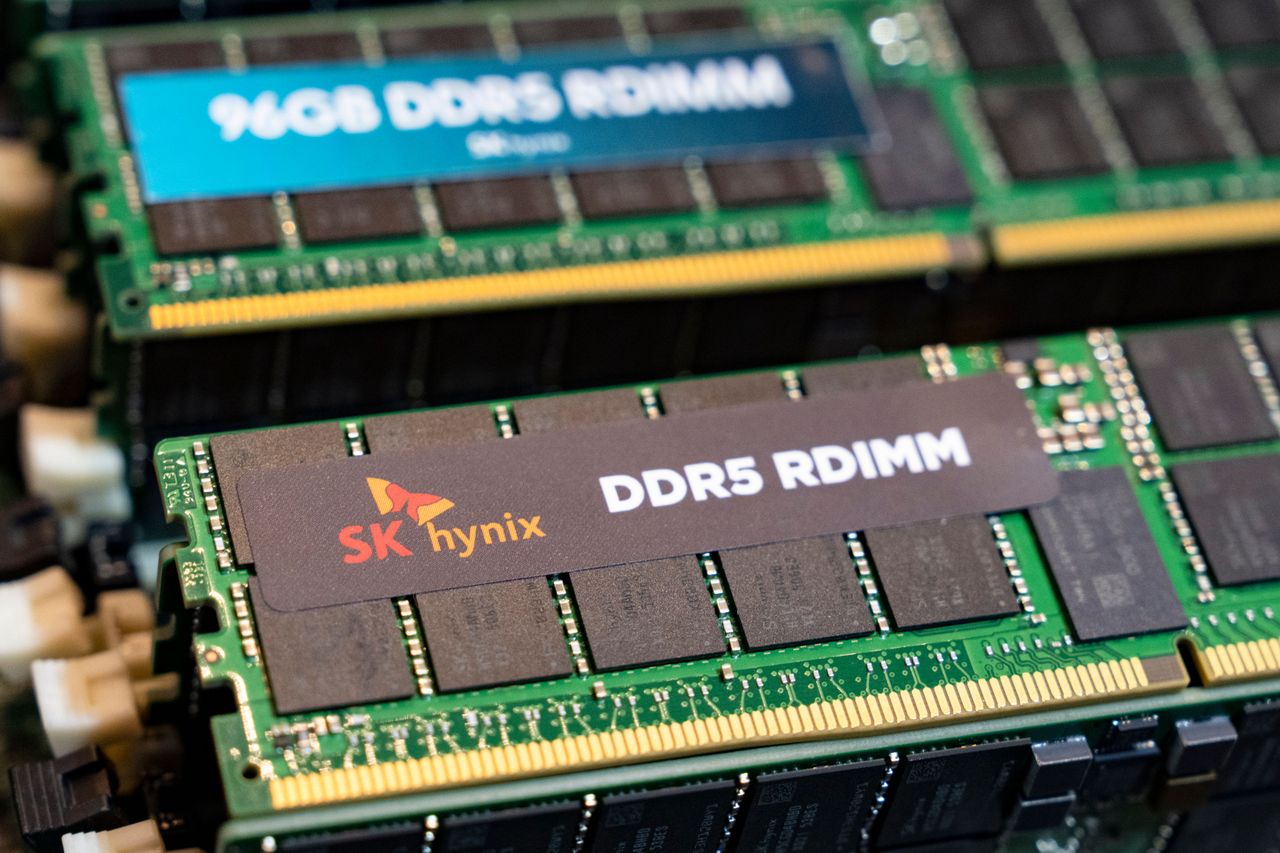
CXMT Targets DDR5 RDIMM Launch by Year-End Amid Market Concerns
Seagate Technology: Surge in AI Storage Demand
Apple Unveils HomeView Hub, Stock Rises 1%
Seagate Technology Holdings plc provides mass-data storage infrastructure solution. The Company’s principal products are hard disk drives, commonly referred to as disk drives, hard drives (HDDs). In addition to HDDs, the Company produces a range of data storage products, including solid state drives (SSDs), solid state hybrid drives, storage subsystems, as well as a scalable edge-to-cloud mass data platform. Its HDD products are designed for mass capacity storage and legacy markets. Mass capacity storage involves use cases, such as hyperscale data centers and public clouds, as well as emerging use cases. The Company’s HDD and SSD product portfolio includes Serial Advanced Technology Attachment, Serial Attached SCSI and Non-Volatile Memory Express based designs to support a variety of mass capacity and legacy applications. Its systems portfolio includes storage subsystems for enterprises, cloud service providers, scale-out storage servers and original equipment manufacturers. It operates in the Technology sector (COMPUTER STORAGE DEVICES industry).
Seagate Technology Holdings PLC is currently trading at $639.01, which is significantly below its recent price target of $865 set by Wells Fargo. However, the stock has a low RSI of 11.83, indicating it is oversold, but the recent 5-day change of -18.39% suggests continued selling pressure. The company's gross margin has improved to 52.30%, and it reported a strong revenue growth of 34% year-over-year, which are positive signs for long-term investors. The main risk is the recent insider selling activity, which has increased by 345% over the last month, indicating potential lack of confidence from insiders.
27 analysts cover STX: 3 rate it Buy, 19 Hold and 5 Sell. The average price target is 310.39.
$MHA $STX $ARB One of the most rewarding experiences has been recommending CY WATSON to a friend who wanted to explore crypto copy trading. After following his market insights and participating in copy trading, my friend recently received a profit payout that has brought him closer to a major life goal: owning a new home. Seeing him turn his trading journey into a meaningful milestone has been genuinely exciting, and it reminds me why I value CY WATSON's approach to market analysis and trading opportunities. His progress has also encouraged others around me to take a closer look at crypto copy trading. If you're interested in learning from his approach, where can you find CY WATSON's latest updates and discover more about his trading insights? His username is in the comments below for anyone who wants to take a look.
展开
#U.S. Memory Stocks Extend Losses #ShareWeekly AI memory stocks under pressure: the market is reassessing growth, competition, and profitability 💾 AI demand keeps growing, but the memory sector is facing a tougher test. On Friday, October 16, investors' concentrated bets on the AI infrastructure theme ran into another warning. Seagate Technology fell 4.9% to $657.41; Western Digital fell 4.6% to $339.84; Micron fell 5.6%. The Nasdaq Composite dropped 2.1%, reflecting broad pressure on tech stocks. The important shift is that investors are no longer focused only on AI demand forecasts. They are starting to ask a harder question: **if competition intensifies and market expectations cool, which companies can defend their margins?** Three developments driving the selloff 1. Valuations are being tested by higher expectations Memory stocks have benefited from expectations of strong AI-related spending, tight supply, and improving profitability. But after a large rally, if investors believe future growth is already reflected in valuations, even positive business news may not be enough to support the share price. The recent tech selloff has also heightened concerns about the financing and eventual returns of large-scale AI infrastructure investment. 2. Competition could challenge pricing power Reports that China's CXMT has made progress on higher-density DRAM designs have added to concerns about future memory chip competition. Meanwhile, reports that Toshiba plans to expand hard drive capacity have put the HDD supply outlook under scrutiny. These developments do not prove an imminent direct shock to the industry, but they raise new questions about long-term pricing and market share. 3. Different products carry different risks The memory industry is not a homogeneous sector. Micron is involved in DRAM, high-bandwidth memory, and NAND flash; SanDisk focuses on flash storage; Western Digital and Seagate focus on hard drives. Their earnings react differently to memory pricing, enterprise SSD demand, data center orders, and production capacity. 🔬 Where the next wave of opportunity may lie | Company | Key metrics to watch | |---|---| | **Micron (MU)** | HBM demand, memory pricing, and competition | | **SanDisk (SNDK)** | NAND pricing and enterprise SSD adoption | | **Western Digital (WDC)** | HDD supply, pricing, and customer demand | | **Seagate (STX)** | High-capacity HDD shipments and margins | The upcoming earnings reports from Western Digital and Seagate are especially important, because management guidance will help investors assess whether AI-related demand remains strong enough to support current supply and pricing expectations. ⚖️ Bull case and bear case Bull case AI workloads continue to grow, data center operators need more storage, and disciplined production helps support pricing power. As a result, the share price decline may reflect a valuation reset rather than a deterioration in underlying demand. Bear case New capacity, intensifying competition, and rising financing costs squeeze margins, while elevated expectations leave little room for error on performance. In this scenario, even if the memory market keeps growing, shareholder returns could be uneven. 🎯 Signals to watch next Rather than judging the entire sector based on a single trading day, investors may want to track four fundamental indicators: - Pricing: Are the economics of DRAM, HBM, NAND, and HDD continuing to improve? - Demand: Are cloud service and enterprise customers maintaining storage spending? - Margins: Is revenue growth translating into stronger operating profitability? - Supply: Is capacity expansion outpacing demand absorption? If these fundamentals remain healthy while prices stabilize and sentiment improves, confidence in a sustained recovery would be higher. Final view: the opportunity in AI storage has not disappeared, but the market demands stronger evidence that growth can translate into durable profits. The next leaders may be companies that combine technological relevance, pricing discipline, efficient production, and stable cash generation.
展开
#U.S. Memory Storage Sector Extends Losses #ShareWeekly AI memory stocks under pressure: the market is reassessing growth, competition, and profitability. 💾 AI demand keeps expanding, but investment in the memory sector is facing a tougher test. On Friday, October 16, another warning sign for investors heavily positioned in the AI infrastructure theme. Seagate Technology fell 4.9% to $657.41; Western Digital fell 4.6% to $339.84; Micron fell 5.6%. The Nasdaq Composite dropped 2.1%, reflecting broad pressure on tech stocks. The important shift is that investors are no longer focused only on AI demand forecasts. They are starting to ask a harder question: **if competition intensifies and market expectations cool, which companies can defend their margins?** Three developments driving the selloff 1. Valuations face higher expectations Memory stocks benefited from expectations of strong AI-related spending, tight supply, and improving profitability. But after sharp share-price gains, if investors believe future growth is already reflected in valuations, even positive business news may not be enough to support the stock price. The recent tech selloff has also raised concerns about the financing and eventual returns of large AI infrastructure investments. 2. Competition could challenge pricing power Reports that China's CXMT has made progress on higher-density DRAM designs have intensified concerns about future memory chip competition. Meanwhile, reports that Toshiba plans to expand hard drive manufacturing capacity have put the HDD supply outlook under scrutiny. These developments do not prove an imminent direct shock to the industry, but they do raise new questions about long-term pricing and market share. 3. Different products carry different risks The memory industry is not a single investment target. Micron is involved in DRAM, high-bandwidth memory, and NAND flash; SanDisk focuses on flash storage; Western Digital and Seagate focus on hard drives. Their earnings react differently to memory pricing, enterprise SSD demand, data center orders, and manufacturing capacity. 🔬 Where the next round of opportunities may appear | Company | Key metrics to watch | |---|---| | **Micron (MU)** | HBM demand, memory pricing, and competition | | **SanDisk (SNDK)** | NAND pricing and enterprise SSD adoption | | **Western Digital (WDC)** | HDD supply, pricing, and customer demand | | **Seagate (STX)** | High-capacity HDD shipments and margins | The upcoming earnings reports from Western Digital and Seagate are especially important, because management guidance can help investors assess whether AI-related demand remains strong enough to support current expectations for supply and pricing. ⚖️ Bull case and bear case Bull case AI workloads continue to expand, data center operators need more storage, and disciplined production helps support pricing power. As a result, the share-price decline may reflect a valuation reset rather than a deterioration in underlying demand. Bear case New capacity, intensifying competition, and rising financing costs squeeze margins, while elevated expectations leave little room for disappointing results. In this scenario, even if the memory market continues to grow, shareholder returns could be uneven. 🎯 Signals to watch next Rather than judging the sector's performance based on a single trading day, investors may want to track four fundamental indicators: - Pricing: Are the economics of DRAM, HBM, NAND, and HDD still supported? - Demand: Are cloud and enterprise customers maintaining storage spending? - Margins: Is revenue growth translating into stronger operating profitability? - Supply: Is capacity expansion outpacing demand absorption? If these fundamentals remain healthy while prices stabilize and sentiment improves, the case for a sustained recovery would be stronger. Final view: the opportunity in AI storage has not disappeared, but the market is demanding stronger evidence that growth can translate into durable profits. The next group of leaders may be companies that combine technological relevance, pricing discipline, efficient production, and stable cash generation.
展开
💾 AI is still developing, but are memory stocks already under pressure? Not long ago, memory was a hot sector the market chased. Now, the sector is under sustained pressure. Related stocks including Kioxia, SanDisk, Western Digital, and Seagate have pulled back one after another, while Micron has also seen significant volatility. This time, market concerns go beyond short-term profit-taking. 📉 Valuation: Has AI-driven growth expectation already been priced in? 🔥 Competition: Will new technologies and new players entering the market change the memory industry landscape? 📊 Divergence: Although Micron, SanDisk, and Western Digital are all memory stocks, why have their trajectories started to differ? The long-term logic of AI demand growth and short-term stock price moves are not necessarily the same thing. Which memory company are you watching most closely right now? Has this pullback changed your trading plan? Use #美股存储板块跌幅扩大 to head to Gate Square and share position changes, sector analysis, or trade reviews. 💬 After this pullback, what signal are you waiting for before rebuilding positions?
展开US memory stocks extend their decline: Is the AI trade losing momentum, or creating a new opportunity? US memory stocks have recently sold off, raising an important question: Is this just a healthy pullback after a strong AI-driven rally, or is the market starting to reassess the sector's earnings potential and future valuation? Companies like Micron, SanDisk, Western Digital, and Seagate have benefited from demand growth tied to AI infrastructure, cloud computing, and data center expansion. However, even strong sectors can experience sharp pullbacks when investors begin to worry about valuations, take profits, or question whether future earnings can support elevated share prices. In my view, the key is not to buy just because prices have fallen. Investors need to understand what is changing beneath the surface. 1. Micron (MU): AI memory demand under scrutiny Micron remains an important company to watch because of its exposure to DRAM, high-bandwidth memory (HBM), and advanced memory solutions used in AI infrastructure. AI accelerator demand can support HBM consumption, while traditional DRAM demand also depends on PCs, smartphones, and enterprise systems. Still, strong demand does not necessarily guarantee continued stock gains. I will be watching memory pricing, gross margin forecasts, capacity, and management's forward guidance. If earnings expectations remain resilient during the pullback, MU could regain attention. If forecasts weaken, the decline could last longer. 2. SanDisk (SNDK): NAND flash remains a key factor SanDisk is closely tied to NAND flash and solid-state drives (SSDs). Enterprise SSD adoption could benefit from growing demand to store and retrieve massive amounts of AI-generated data. However, NAND is a cyclical market. Changes in supply, inventory levels, and contract prices can significantly affect profitability. I will be watching whether NAND prices stabilize, whether enterprise demand continues to expand, and whether earnings expectations remain supported. A lower share price alone is not enough to prove that SNDK's valuation has become attractive. 3. Western Digital (WDC): The case for high-capacity HDDs Western Digital offers a different perspective, as high-capacity hard disk drives remain closely tied to cloud storage and large data centers. AI infrastructure needs not only high-speed memory and SSDs, but also massive space to store datasets, backups, and other information. Therefore, cloud providers' capital expenditure plans and demand for nearline HDDs are important indicators. Investors should watch shipment growth, pricing power, gross margins, and free cash flow to judge whether the company's fundamentals support its valuation. 4. Seagate (STX): Storage demand and valuation risk Seagate is another major beneficiary of high-capacity storage demand. As data center operators expand infrastructure, demand for efficient high-capacity drives could remain an important long-term driver. However, investors must distinguish between genuine earnings growth and expectations already reflected in the share price. I will be watching order trends, product mix, margins, and management's outlook on future demand. What could trigger a sustained recovery? I will be watching three main signals: - Fundamental stabilization: Memory and NAND prices stop weakening, while earnings expectations and company guidance remain stable. - Technical confirmation: Stocks form higher lows, reclaim important moving averages, and volume improves. - Reasonable valuation: Expected earnings growth can support current prices even under a less optimistic market scenario. The broader macroeconomic environment also matters. Rate expectations, US Treasury yields, tech sector sentiment, and corporate spending plans all influence how investors value AI-related companies. My final take I remain positive on the long-term opportunity in the storage sector, but I will avoid treating MU, SNDK, WDC, and STX as identical investments. DRAM, HBM, NAND flash, and hard disk drives each have different demand drivers, competitive dynamics, and supply cycles. Pullbacks driven by profit-taking may create opportunities. Declines caused by weakening demand, falling prices, or deteriorating earnings guidance require more caution. For now, I will prioritize fundamental evidence, valuation discipline, and confirmation from price action rather than rushing to buy the dip. #USMemoryStocksExtendLosses #ContentMining #PlanYourTradesThisWeek
展开
本页仅供研究参考,不构成投资建议。模型可能出错。过往表现不代表未来结果。