
乐
乐观
乐观 · 25%AAPL
$269.88
情景价格
$347.725
-0.487 (-0.14%)收盘时
Apple Inc. designs, manufactures and markets smartphones, personal computers, tablets, wearables and accessories, and sells a variety of related services. Its product categories include iPhone, Mac, iPad, Wearables, Home and Accessories. Its services include advertising, AppleCare, cloud services, digital content, and payment services. The Company operates various platforms, including the App Store, that allow customers to discover and download applications and digital content, such as books, music, video, games and podcasts. It also offers digital content through subscription-based services, including Apple Arcade, Apple Fitness+, Apple Music, Apple News+, and Apple TV+. Its wearables include smartwatches, wireless headphones, and spatial computers. Its products include iPhone 16 Pro, iPhone 16, iPhone 15, iPhone 14, iPhone SE, MacBook Air, MacBook Pro, iMac, Mac mini, Mac Studio, Mac Pro, iPad Pro, iPad Air, AirPods, AirPods Pro, AirPods Max, Apple TV, Apple Vision Pro and others.
Apple Inc is a good buy right now due to its current price of $347.725, which is below the average analyst target of $370, indicating potential upside. Additionally, the company's gross margin has improved to 50.06%, reflecting strong profitability. However, a risk to consider is the insider selling activity, which has increased by 190.95% over the last month, suggesting some caution from insiders.
情景价格取自当年最后一个月度预测区间。概率为固定的模型权重(25 / 50 / 25),不构成保证。
Apple's Market Cap Reaches $5 Trillion Amidst Strong Profitability
Apple's Smart Home Launch and Luxury Market Decline
Market Stagnation Sparks Diverging Investor Sentiment
Apple and Alphabet: Forever Stocks in AI Investment
Future of Smart Homes and Flying Cars Discussed
Apple Inc. designs, manufactures and markets smartphones, personal computers, tablets, wearables and accessories, and sells a variety of related services. Its product categories include iPhone, Mac, iPad, Wearables, Home and Accessories. Its services include advertising, AppleCare, cloud services, digital content, and payment services. The Company operates various platforms, including the App Store, that allow customers to discover and download applications and digital content, such as books, music, video, games and podcasts. It also offers digital content through subscription-based services, including Apple Arcade, Apple Fitness+, Apple Music, Apple News+, and Apple TV+. Its wearables include smartwatches, wireless headphones, and spatial computers. Its products include iPhone 16 Pro, iPhone 16, iPhone 15, iPhone 14, iPhone SE, MacBook Air, MacBook Pro, iMac, Mac mini, Mac Studio, Mac Pro, iPad Pro, iPad Air, AirPods, AirPods Pro, AirPods Max, Apple TV, Apple Vision Pro and others. It operates in the Technology sector (ELECTRONIC COMPUTERS industry).
Apple Inc is a good buy right now due to its current price of $347.725, which is below the average analyst target of $370, indicating potential upside. Additionally, the company's gross margin has improved to 50.06%, reflecting strong profitability. However, a risk to consider is the insider selling activity, which has increased by 190.95% over the last month, suggesting some caution from insiders.

Thanks to the stranger. I post updates just to earn a little extra from traffic. My ability is limited, so I pick stable types; only holding positions long term makes money. I feel bad seeing people follow along, lose money, and leave. I run a long-term public record so we can learn from each other.
展开
I used an iPhone duo for a few days. Here are my thoughts: Pros - The outer screen width is great for typing, much better than the iPhone 17 pro max I used before - I was surprised by how practical this outer screen form factor is - Touch ID is not an issue because I wear an Apple Watch and can unlock with it - The inner screen looks really nice when used with optimized apps - Battery life is surprising The speakers are very powerful - I'm left-handed, but I don't find this to be a problem Cons - The camera is clearly not as good as the 17pm - Many apps, including Apple's own apps, are not yet optimized for it - Sometimes I accidentally press the camera button when unfolding the phone - I miss the action button on the Pro Max - Even optimized apps like x still have quite a few issues Also, if you open and close a foldable phone by pressing on the hinge, that's not a smart way to do it
展开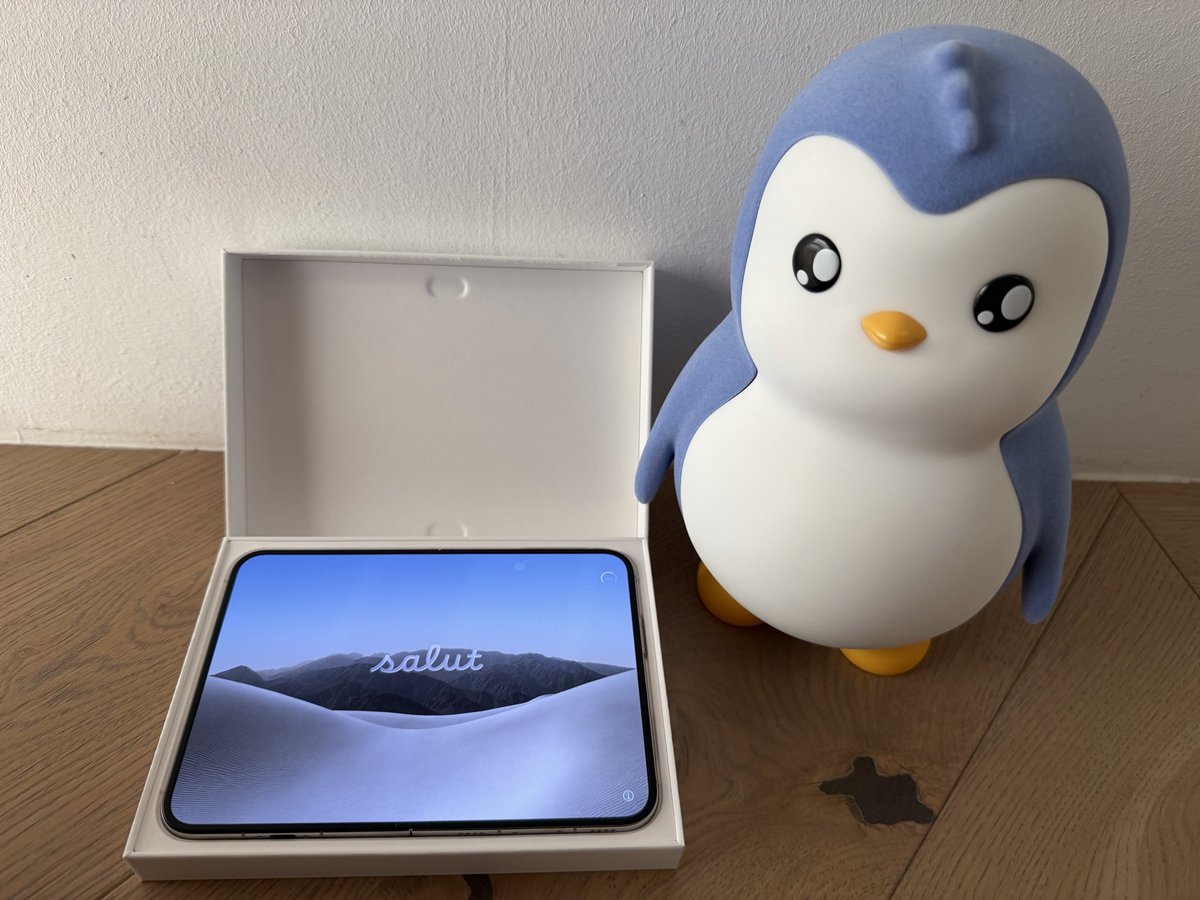
I have a bad feeling about this. The next 10 days may be the toughest stretch for the crypto market this year. 10/27 Israel election, 10/28 Fed rate decision plus Google & Microsoft earnings, 10/29 ECB rate decision, 10/30 BOJ rate decision, 11/2 Apple earnings, 11/3 US midterm elections. Place your bets, everyone.
展开
#USEarningsSeason #USStocksEarningsSeason #ShareWeekly $AAPL $TSLA $META Meta revenue beat expectations but still closed down about 7%. Tesla EPS beat expectations but closed down about 3%. The tech index fell 2.6% on the same trading day. My view: the standard for this earnings season is no longer whether results beat expectations, but cash flow and what these expenditures actually delivered. 1. For now, an earnings beat is not a buy signal Meta's third-quarter revenue was about $64.6 billion, up 26% year over year and above expectations. Tesla reported EPS of $0.48 versus market expectations of about $0.45. Both companies were sold off. The selloff after positive news shows the market is focused on what was paid for the growth, not whether the numbers cleared the expected threshold. 2. Meta's problem is where the money comes from A detailed report showed Meta's capital expenditure this quarter was about $34.9 billion, while operating cash flow was about $32.8 billion, so free cash flow fell to about -$2.1 billion. My calculation: capital expenditure rose about 80% year over year while revenue grew 26%, and capital expenditure was about 54% of revenue. There was also $9.9 billion in legal-related expenses, and the company announced a new non-voting share class to help fund AI. Next-quarter revenue guidance ($73B to $76B) was strong, but that answers the growth question, not the funding question. 3. Tesla cut spending and still did not win market recognition Gross margin recovered to 19.6% from 16.8% in the prior quarter, capital expenditure fell from $5.8 billion to about $4.7 billion, and free cash flow was positive. But revenue was flat at about $28 billion, and operating profit reportedly fell about 56% as AI and Optimus-related costs grew faster than gross profit. My read: the lower capital expenditure plan was seen as a sign of doubt about the robotics business rather than a reassuring signal. 4. Where my charts stand (from my daily chart) META 645: about 0.3% above my support at 643.44, below three moving averages, RSI near 39. Room to my 776.54 level is about 20%. NVDA 212: 1.35% above support at 209.46, with about 14% room to resistance at 242.56. RSI near 38.5. TSLA 373: 4.6% to 390.41 above and 6.5% to 349.04 below. This setup is not worth entering early for me. AAPL 348.5: 0.3% below my 349.43 level, RSI near 65. The only strong chart among the four. 5. The calendar decides the next move Microsoft and Alphabet report on October 28, Amazon on October 29, and Apple on November 2 after the US market close. Nvidia is expected to report around November 18, but I have not seen a confirmed date. Its guidance is about $108B (plus or minus 2%), while last quarter's actual came in about 6% above guidance. If that performance repeats, the result would be about $114B (my calculation, for illustration only). The market's threshold is an earnings beat plus a clear explanation of how spending will be funded. My view: this earnings season, I will not treat an earnings beat as a positive. Cash flow, the funding source for capital expenditure, and guidance are the scoring criteria. Before the October 28 and 29 reports, I will not chase strength; the levels I am watching are META 643.44 and NVDA 209.46. A daily close below either level would change my view. Not financial advice. Do you now care more about an EPS beat or free cash flow? Which do you think breaks support first: META at 643 or NVDA at 209?
展开
本页仅供研究参考,不构成投资建议。模型可能出错。过往表现不代表未来结果。