
乐
乐观
乐观 · 25%MSFT
$508.39
情景价格
$521.910
-8.090 (-1.55%)收盘时
Microsoft Corporation is a technology company. The Company develops and supports software, services, devices, and solutions. The Productivity and Business Processes segment consists of products and services in its portfolio of productivity, communication, and information services. This segment primarily includes Microsoft 365 Commercial products and cloud services, Microsoft 365 Consumer products and cloud services, LinkedIn, and Dynamics products and cloud services. The Intelligent Cloud segment consists of server products and cloud services, including Azure and other cloud services comprising cloud and AI consumption-based services, GitHub cloud services, Health and Life Sciences cloud services, and other cloud services; and Server products consist of SQL Server, Windows Server, Visual Studio, System Center, related Client Access Licenses, and other on-premises offerings. The More Personal Computing segment primarily comprises Windows and Devices, XBOX, and Search advertising.
Microsoft is currently a hold. The stock is priced at $524.51, with a forward P/E ratio of 25.13, indicating it may be fairly valued for long-term investors. However, the RSI is at 42.61, suggesting it is nearing oversold conditions, which could lead to a potential rebound. The main risk is the upcoming earnings report on October 28, where expectations are set at an EPS of 4.71, which could impact the stock's performance depending on the results.
Freedom Broker
$625
2026-10-30
Freedom Broker
2026-10-30
目标价
$625
Griffin Securities
—
2026-10-29
Griffin Securities
2026-10-29
目标价
—
Scotiabank
$650
2026-10-29
Scotiabank
2026-10-29
目标价
$650
UBS
$700
2026-10-29
UBS
2026-10-29
目标价
$700
Raymond James
$650
2026-10-29
Raymond James
2026-10-29
目标价
$650
情景价格取自当年最后一个月度预测区间。概率为固定的模型权重(25 / 50 / 25),不构成保证。
Microsoft Reports Strong Q1 2027 Earnings with Azure Growth
Corporate AI Investments Yield Financial Benefits

AI Drives Revenue Growth for Major Corporations
Palantir Technologies Stock Soars Nearly 700% Over Five Years Amid AI Boom
OpenAI Lowers Funding Target to $20 Billion Amid Market Scrutiny
Microsoft Corporation is a technology company. The Company develops and supports software, services, devices, and solutions. The Productivity and Business Processes segment consists of products and services in its portfolio of productivity, communication, and information services. This segment primarily includes Microsoft 365 Commercial products and cloud services, Microsoft 365 Consumer products and cloud services, LinkedIn, and Dynamics products and cloud services. The Intelligent Cloud segment consists of server products and cloud services, including Azure and other cloud services comprising cloud and AI consumption-based services, GitHub cloud services, Health and Life Sciences cloud services, and other cloud services; and Server products consist of SQL Server, Windows Server, Visual Studio, System Center, related Client Access Licenses, and other on-premises offerings. The More Personal Computing segment primarily comprises Windows and Devices, XBOX, and Search advertising. It operates in the Technology sector (SERVICES-PREPACKAGED SOFTWARE industry).
Microsoft is currently a hold. The stock is priced at $524.51, with a forward P/E ratio of 25.13, indicating it may be fairly valued for long-term investors. However, the RSI is at 42.61, suggesting it is nearing oversold conditions, which could lead to a potential rebound. The main risk is the upcoming earnings report on October 28, where expectations are set at an EPS of 4.71, which could impact the stock's performance depending on the results.
34 analysts cover MSFT: 27 rate it Buy, 6 Hold and 1 Sell. The average price target is 631.36.
Microsoft Xbox CEO Asha Sharma has set a goal of surpassing Sony and Nintendo in profit margin by 2030, while Xbox will invest in Minecraft and expand into film, TV, and other derivative businesses. However, U.S. Xbox Series sales fell 27% year-over-year in September, hitting a record low, and revenue dropped 10% in the most recent quarter. The competitors' operating margins are 9.9% and nearly 16%, respectively, while Xbox is dealing with record-low sales, declining revenue, and studios being merged or closed — stabilize the current quarter first before talking about surpassing anyone by 2030. $BTC #QuantExpert# Let's talk about quant and the market — what's your view?
展开
Microsoft's $677 billion commercial backlog shows how much demand is building around its cloud and artificial intelligence services. The figure increased 73% year over year, giving the company a substantial base of contracted revenue expected to be recognized in future periods. Revenue also reached $92.3 billion in the first quarter of fiscal 2027, up 19%, while Microsoft Cloud revenue climbed 30% to $63.9 billion. Azure contributed strongly, with revenue rising 48% to $33.17 billion. However, the cost of supporting this growth is becoming an important part of the earnings story. Microsoft's additions to property and equipment reached $39.37 billion during the quarter, compared with $19.39 billion a year earlier. That is an increase of approximately 103%, considerably faster than the growth in cloud revenue. The spending reflects the need for more data centers, computing equipment and infrastructure to handle rising AI and cloud workloads. This difference does not mean the investment is failing to generate returns. New facilities take time to become operational and contribute to revenue. However, it means Microsoft is committing substantial capital before receiving the full financial benefits. The company also reported delays in third-party capacity deliveries, showing that infrastructure availability could affect how quickly it meets customer demand. Cash flow provides another way to assess the expansion. Operating cash flow increased to $58 billion from $45.06 billion, but after property and equipment additions, free cash flow stood at approximately $18.63 billion, down from $25.66 billion a year earlier. Microsoft is still generating significant cash, although its infrastructure spending is taking a larger share. The earnings figures also require some context. GAAP net income increased 32% to $36.63 billion, partly reflecting a more favorable comparison in its OpenAI investment results. On an adjusted basis, net income grew 18% to $36.42 billion, offering a more measured view of operating performance. For technology stocks, Microsoft's spending remains an important signal for semiconductor and data center suppliers. However, stronger demand does not automatically translate into higher earnings across the supply chain. Microsoft's shares initially gained more than 3% after the announcement but closed October 30 at $521.91, down 1.55%. The $677 billion backlog confirms substantial customer commitments. The bigger test now is whether Microsoft can turn those commitments into revenue and cash generation quickly enough to justify the rising cost of AI infrastructure. $MSFT
展开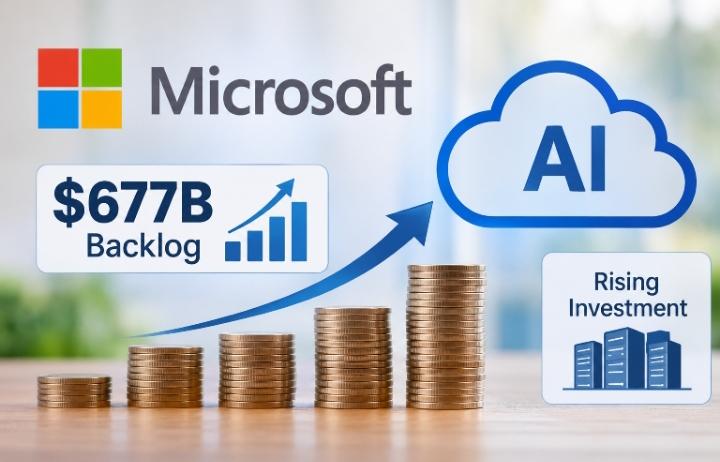
#GoogleCloudSurges103%ButStockFalls #ShareWeekly In Q3 2026, Google Cloud revenue surged 103% year-over-year to $30.7 billion, one of the strongest growth performances among major cloud service providers. Alphabet's total revenue grew 25% to $127.6 billion. Cloud operating income more than tripled, and segment margin expanded to 36.2%. TPU system sales and enterprise AI demand were clear growth drivers. On the surface, these growth figures look outstanding. However, the market reaction was the opposite. Alphabet shares fell about 10% in after-hours trading and closed down about 12.6% the following session, wiping hundreds of billions of dollars off its market value. Net income fell 25% to $26.17 billion. Diluted EPS was $2.12, well below expectations. After capital expenditures reached $51.4 billion, free cash flow turned sharply negative to -$9.07 billion. Operating cash flow was $42.3 billion, still insufficient to cover the massive spending. This contrast is at the heart of the current debate: for investors right now, is AI-driven growth more important, or are profitability and cash flow more important? The growth camp's argument is straightforward. Google Cloud more than doubled, backlog reached $561 billion, and management expects to recognize more than 55% of it as revenue over the next 24 months. Eighteen product lines currently each generate more than $1 billion in annual revenue. AI infrastructure and solutions are clearly favored by enterprise customers. In a multi-year technology shift, companies that capture market share early often keep compounding value for years. Pure growth investors argue that temporarily consuming cash is the necessary price of building dominance in a market that could reach hundreds of billions of dollars annually. Right now, profitability and cash flow factors carry more weight for most investors. In an environment of higher rates and persistently high real yields, the market has less patience for long-term investment stories that have not yet achieved sustained positive free cash flow. Alphabet spent more on real estate and equipment than cash generated from operations. Free cash flow swung from positive $24.5 billion a year earlier to an outflow of $9.07 billion. Search advertising remains the largest profit engine, but grew only 12%, a clear slowdown. AI Mode queries currently monetize at a lower rate than traditional search, adding pressure to the core business that has historically funded everything else. Investors are also comparing Alphabet with peers. Microsoft, reporting around the same time, delivered positive free cash flow above expectations, and its stock rose accordingly. The contrast highlights that with capital intensity this high, growth alone is no longer enough. Full-year capex guidance remains high at $195 billion to $205 billion, and management said 2027 spending will be significantly higher. This trend raises questions about how long cash burn will last and when these investments will show returns in free cash flow. History offers a useful perspective. Tech companies that successfully navigated heavy investment phases eventually achieved both growth and cash generation. Those unable to convert growth into improved unit economics and better cash conversion experienced prolonged valuation compression. Alphabet still generates substantial operating income, and cloud margins are expanding. The question is timing and visibility. Markets tend to reward companies that can clearly demonstrate a path from heavy investment to a cash flow inflection point within a reasonable timeframe. For now, the message from the stock reaction is clear. Cloud growth of 103% was not enough to offset a 25% decline in net income and a $9 billion free cash flow deficit. Investors are prioritizing profitability metrics and cash conversion over pure revenue acceleration. Growth still matters, but when the monetization timeline looks long and capital intensity stays high, the valuation multiple assigned to that growth gets discounted. Looking ahead, the next few quarters will be decisive. Market observers will focus on whether cloud margins can continue expanding, whether search monetization can stabilize or improve as AI features mature, and whether free cash flow can begin to recover even as absolute capex remains high. If Alphabet can show improved cash conversion while cloud growth remains strong, the market will likely re-rate the stock higher. Until then, headline growth alone carries less weight than profitability and cash flow. This earnings report reflects a broader shift in tech investor preferences. In a world of higher rates, capital has become more selective. Companies that combine rapid growth with a credible path to cash creation are rewarded. Companies that deliver growth alone face stricter scrutiny and lower valuation multiples until the cash flow outlook improves. #GateSquareHalloween
展开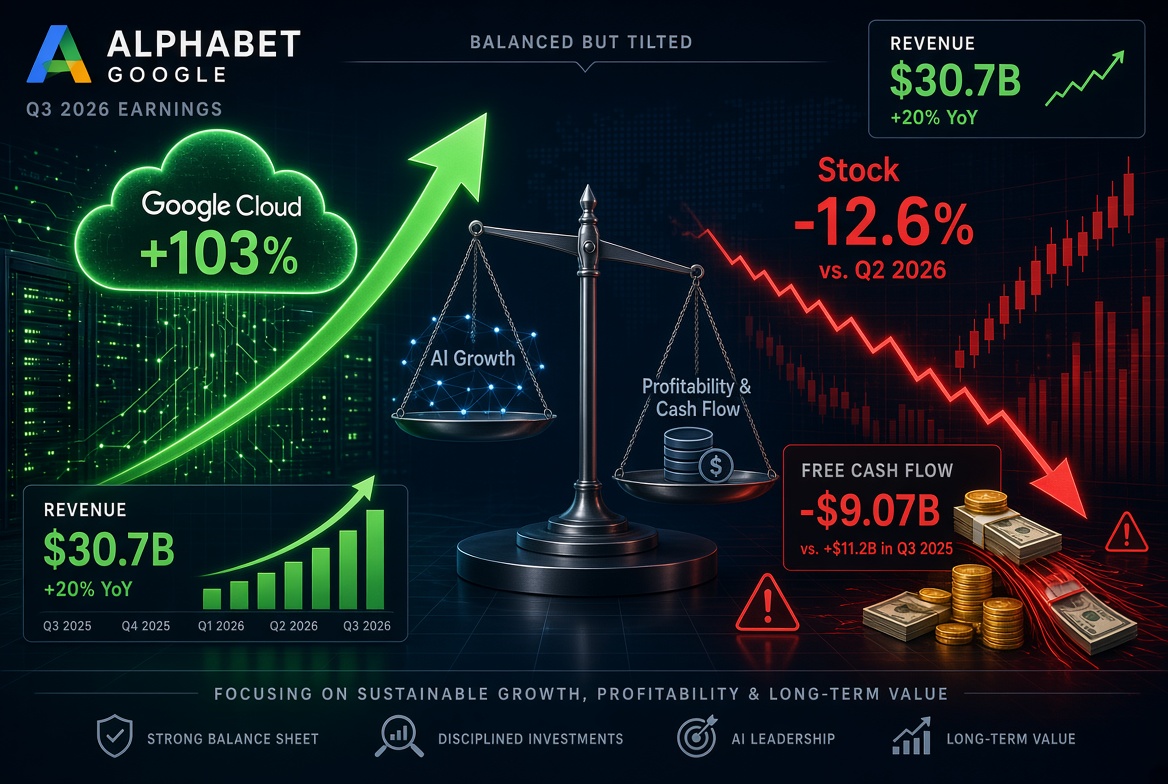
The November Outlook & Plenty of Trade Ideas. With tech correcting into the midterms, which stocks are setting up for a move and what are the key market levels? $GOOGL $MSFT $META $ZS and a breakout in $TRGP fully assessed, plus much more for your November watchlists.
展开本页仅供研究参考,不构成投资建议。模型可能出错。过往表现不代表未来结果。