
強
強気
強気 · 25%TSLA
$370.03
シナリオ価格
$391.450
+20.238 (+5.17%)終値時点
Tesla, Inc. designs, develops, manufactures, sells and leases high-performance fully electric vehicles and energy generation and storage systems, and offers services related to its products. Its segments include automotive, and energy generation and storage. The automotive segment includes the design, development, manufacturing, sales and leasing of high-performance fully electric vehicles, and sales of automotive regulatory credits. It also includes sales of used vehicles, non-warranty maintenance services and collisions, part sales, paid supercharging, insurance services revenue and retail merchandise sales. The energy generation and storage segment include the design, manufacture, installation, sales and leasing of solar energy generation and energy storage products and related services and sales of solar energy systems incentives. Its consumer vehicles include the Model 3, Y, S, X and Cybertruck. Its lithium-ion battery energy storage products include Powerwall and Megapack.
Tesla Inc is a good buy right now at a current price of $372.22, especially considering its recent cash flow surprise of $1.53 billion in Q3, which exceeded expectations of a $4.92 billion cash burn. The company's forward P/E ratio of 158.73 suggests that while it is currently expensive, the growth potential driven by its AI and robotics initiatives could justify this valuation. However, the main risk is its recent earnings miss, reporting an EPS of 0.20 against an estimate of 0.22, which resulted in a -3.08% price change post-earnings.
Jefferies
$400
2026-10-12
Jefferies
2026-10-12
目標株価
$400
Tigress Financial
$550
2026-10-08
Tigress Financial
2026-10-08
目標株価
$550
UBS
$391
2026-10-07
UBS
2026-10-07
目標株価
$391
JPMorgan
$415
2026-10-03
JPMorgan
2026-10-03
目標株価
$415
JPMorgan
$415
2026-09-28
JPMorgan
2026-09-28
目標株価
$415
シナリオ価格は本年の最終月次予想レンジです。確率はモデルの固定ウェイト(25 / 50 / 25)であり、保証ではありません。
Tesla's Q3 Earnings Analysis: Challenges and Opportunities
Tesla Cuts 2026 Capex Forecast by Over $5 Billion
U.S. Manufacturing Robotics Adoption on the Rise
Defense Contractors See Stock Gains Amid Upgrades
Analysis of Tesla and SpaceX Merger Prospects
Tesla, Inc. designs, develops, manufactures, sells and leases high-performance fully electric vehicles and energy generation and storage systems, and offers services related to its products. Its segments include automotive, and energy generation and storage. The automotive segment includes the design, development, manufacturing, sales and leasing of high-performance fully electric vehicles, and sales of automotive regulatory credits. It also includes sales of used vehicles, non-warranty maintenance services and collisions, part sales, paid supercharging, insurance services revenue and retail merchandise sales. The energy generation and storage segment include the design, manufacture, installation, sales and leasing of solar energy generation and energy storage products and related services and sales of solar energy systems incentives. Its consumer vehicles include the Model 3, Y, S, X and Cybertruck. Its lithium-ion battery energy storage products include Powerwall and Megapack. It operates in the Consumer Cyclicals sector (MOTOR VEHICLES & PASSENGER CAR BODIES industry).
Tesla Inc is a good buy right now at a current price of $372.22, especially considering its recent cash flow surprise of $1.53 billion in Q3, which exceeded expectations of a $4.92 billion cash burn. The company's forward P/E ratio of 158.73 suggests that while it is currently expensive, the growth potential driven by its AI and robotics initiatives could justify this valuation. However, the main risk is its recent earnings miss, reporting an EPS of 0.20 against an estimate of 0.22, which resulted in a -3.08% price change post-earnings.
23 analysts cover TSLA: 8 rate it Buy, 8 Hold and 7 Sell. The average price target is 401.93.
Tesla is down 20% this year while the other six sisters are all rising, and this divergence is no accident. The market is starting to stop buying the "AI and robots" story; if cars aren't selling, they just aren't selling, and no story is big enough to hold up the valuation. Whether $TSLA is a tech stock or an overvalued car company will be clear from next week's earnings report. Those watching should pay attention.
もっと見る
#USEarningsSeason Can AI-driven growth support tech giants' market valuations? As US earnings season begins, all eyes are on Tesla, Microsoft, Alphabet, Amazon, Apple, Meta, and NVIDIA. The real question, however, is not only whether these companies can beat earnings expectations, but whether their results can support current market valuations. From late October through November, US tech giants report quarterly results one after another, and market volatility around large-cap tech stocks often intensifies. Institutional and retail investors are closely watching whether massive AI capital spending is translating into corresponding revenue growth, whether enterprise cloud spending can be sustained, and whether valuation multiples are supported by fundamentals. Key points to watch: AI and NVIDIA: Strong AI demand remains the main growth driver; however, investors will closely watch revenue growth, margins, and the sustainability of future demand. Microsoft and Alphabet: Cloud growth and AI commercialization will be key factors in determining whether these companies' valuations remain attractive. Amazon: AWS performance, operating margins, and returns on AI infrastructure investment all deserve close attention. Tesla and Meta: Tesla's margin and delivery expectations, as well as Meta's advertising revenue growth and AI investment, could trigger significant swings in their respective share prices. Tech giants' earnings schedule and key drivers Tesla (TSLA) October 21, 2026 | Automotive gross margin, Full Self-Driving (FSD) adoption, Robotaxi timeline updates. Meta Platforms (META) October 21, 2026 | Advertising revenue efficiency, Llama AI infrastructure spending, Family of Apps user engagement. Microsoft (MSFT) October 28, 2026 | Azure cloud revenue growth, Copilot commercialization across enterprise suites. Apple (AAPL) November 2, 2026 | iPhone upgrade cycle, Apple Intelligence feature rollout, Services segment margins. My trading strategy: I will avoid chasing the first price spike that often follows earnings releases. Instead, I will wait for confirmation from price action, volume, company forward guidance, and the broader market's reaction to results. Even if a company beats expectations, its stock can still fall if forward guidance disappoints. Likewise, even if reported results are slightly below expectations, the stock can still rise if investors had expected worse (that is, they had already "priced in" a weaker outcome). In summary, AI remains a strong long-term theme; however, rather than blindly buying every tech stock, it is better to focus more on selectivity and risk management. The biggest opportunities may belong to companies that demonstrate sustainable growth and can convert AI investment into actual profit. $MSFT $TSLA $GOOGL $NVDA $AAPL
もっと見る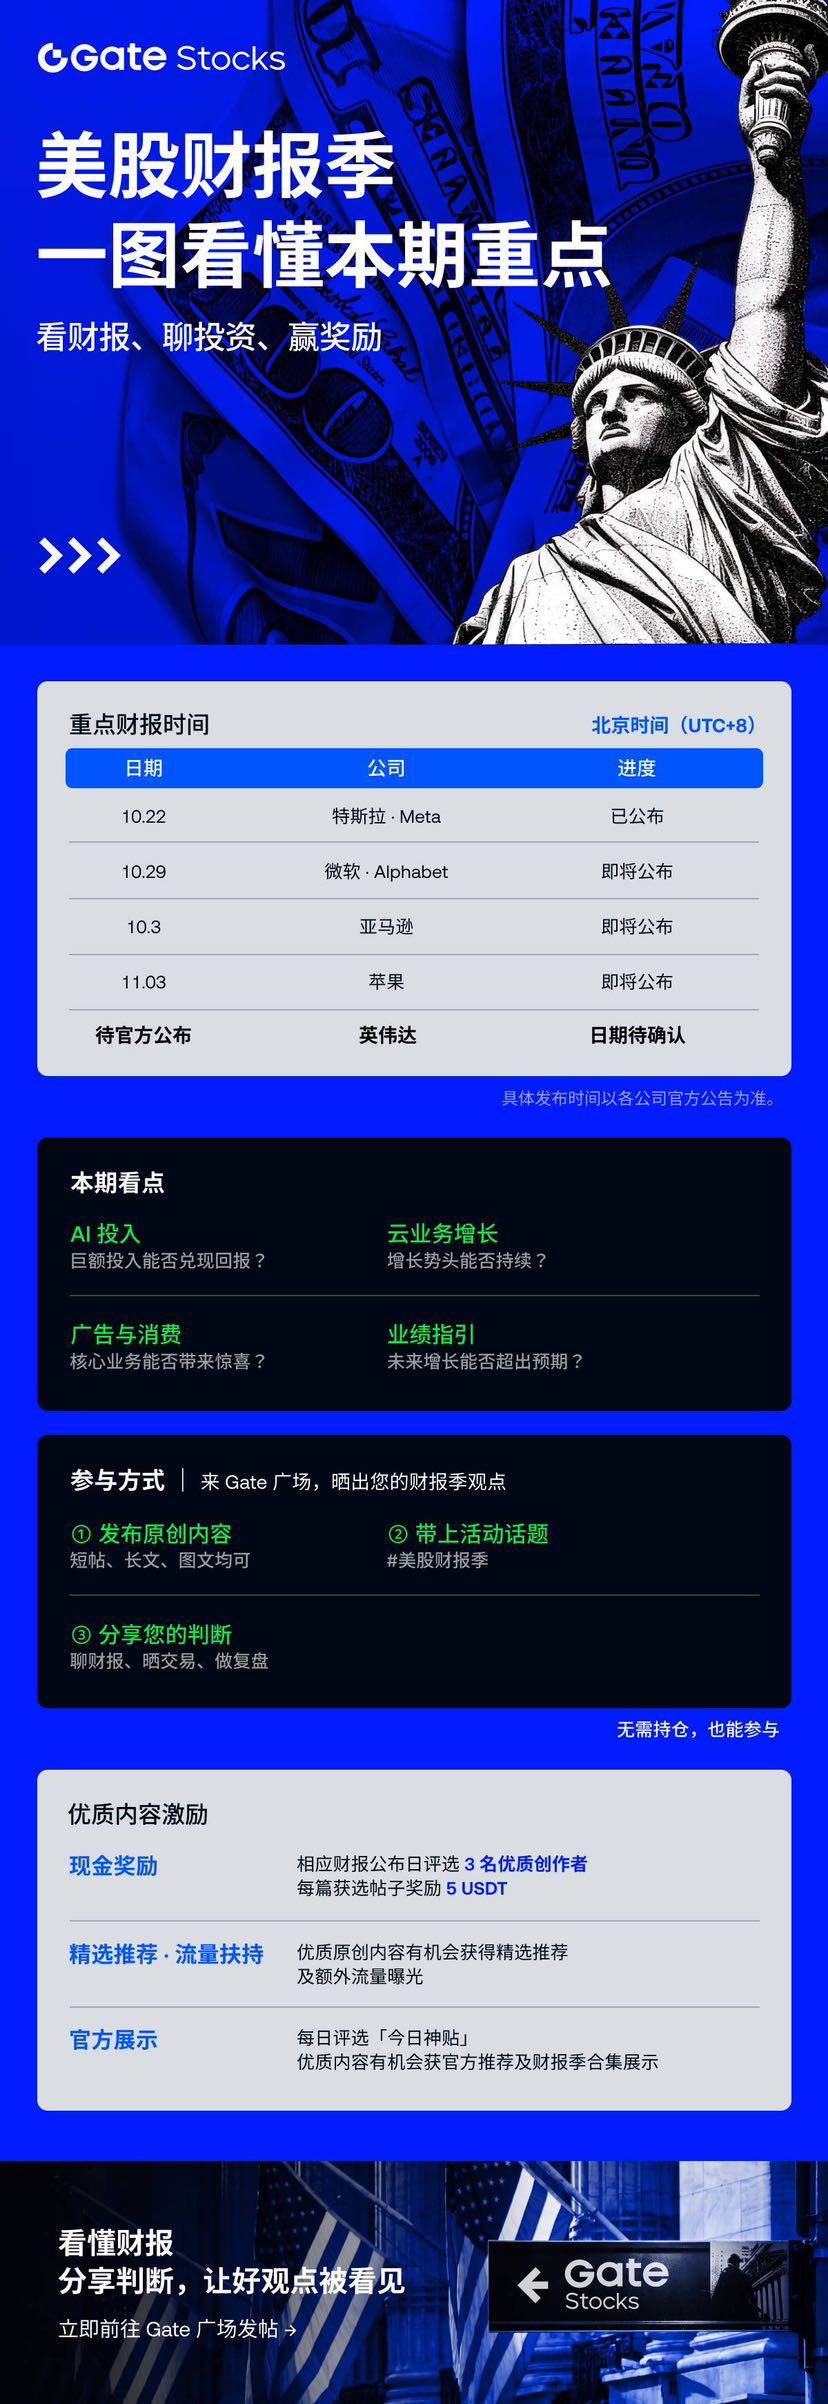
SEC's 2027 examination priorities The SEC's inspection division has listed tokenization, market infrastructure, and "superintelligence" as priorities for 2027. The plan covers more than 34,000 market participants, including advisers, brokers, funds, and clearing agencies. The plan also focuses on cybersecurity, customer data protection, private funds and lending, complex strategies, and protecting retail investors facing high-risk, illiquid products. The SEC may adjust its focus as markets change. $TSLA $MU #ShareWeekly
もっと見る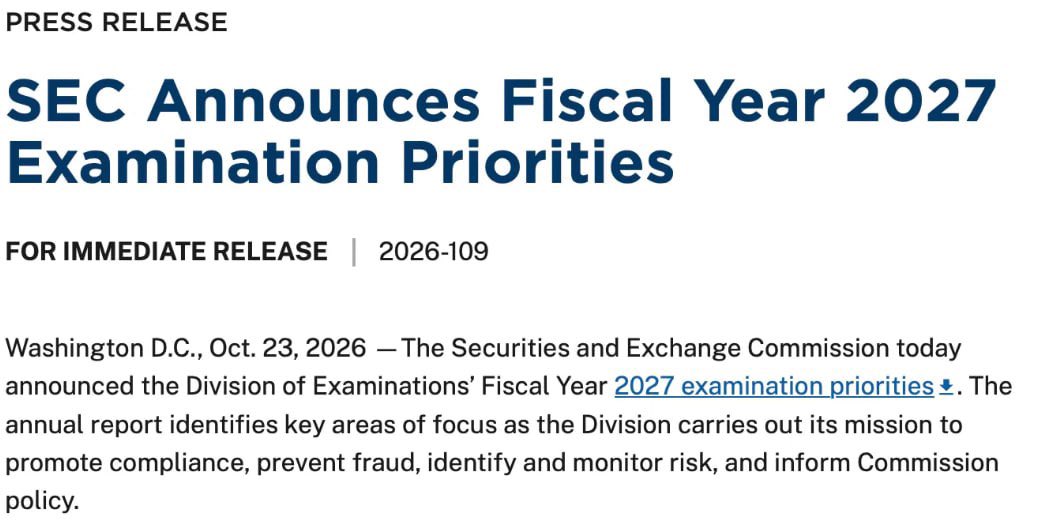
$TSLA is back above its 200-day moving average, while its relative strength line continues to rise, making higher lows and higher highs.
もっと見る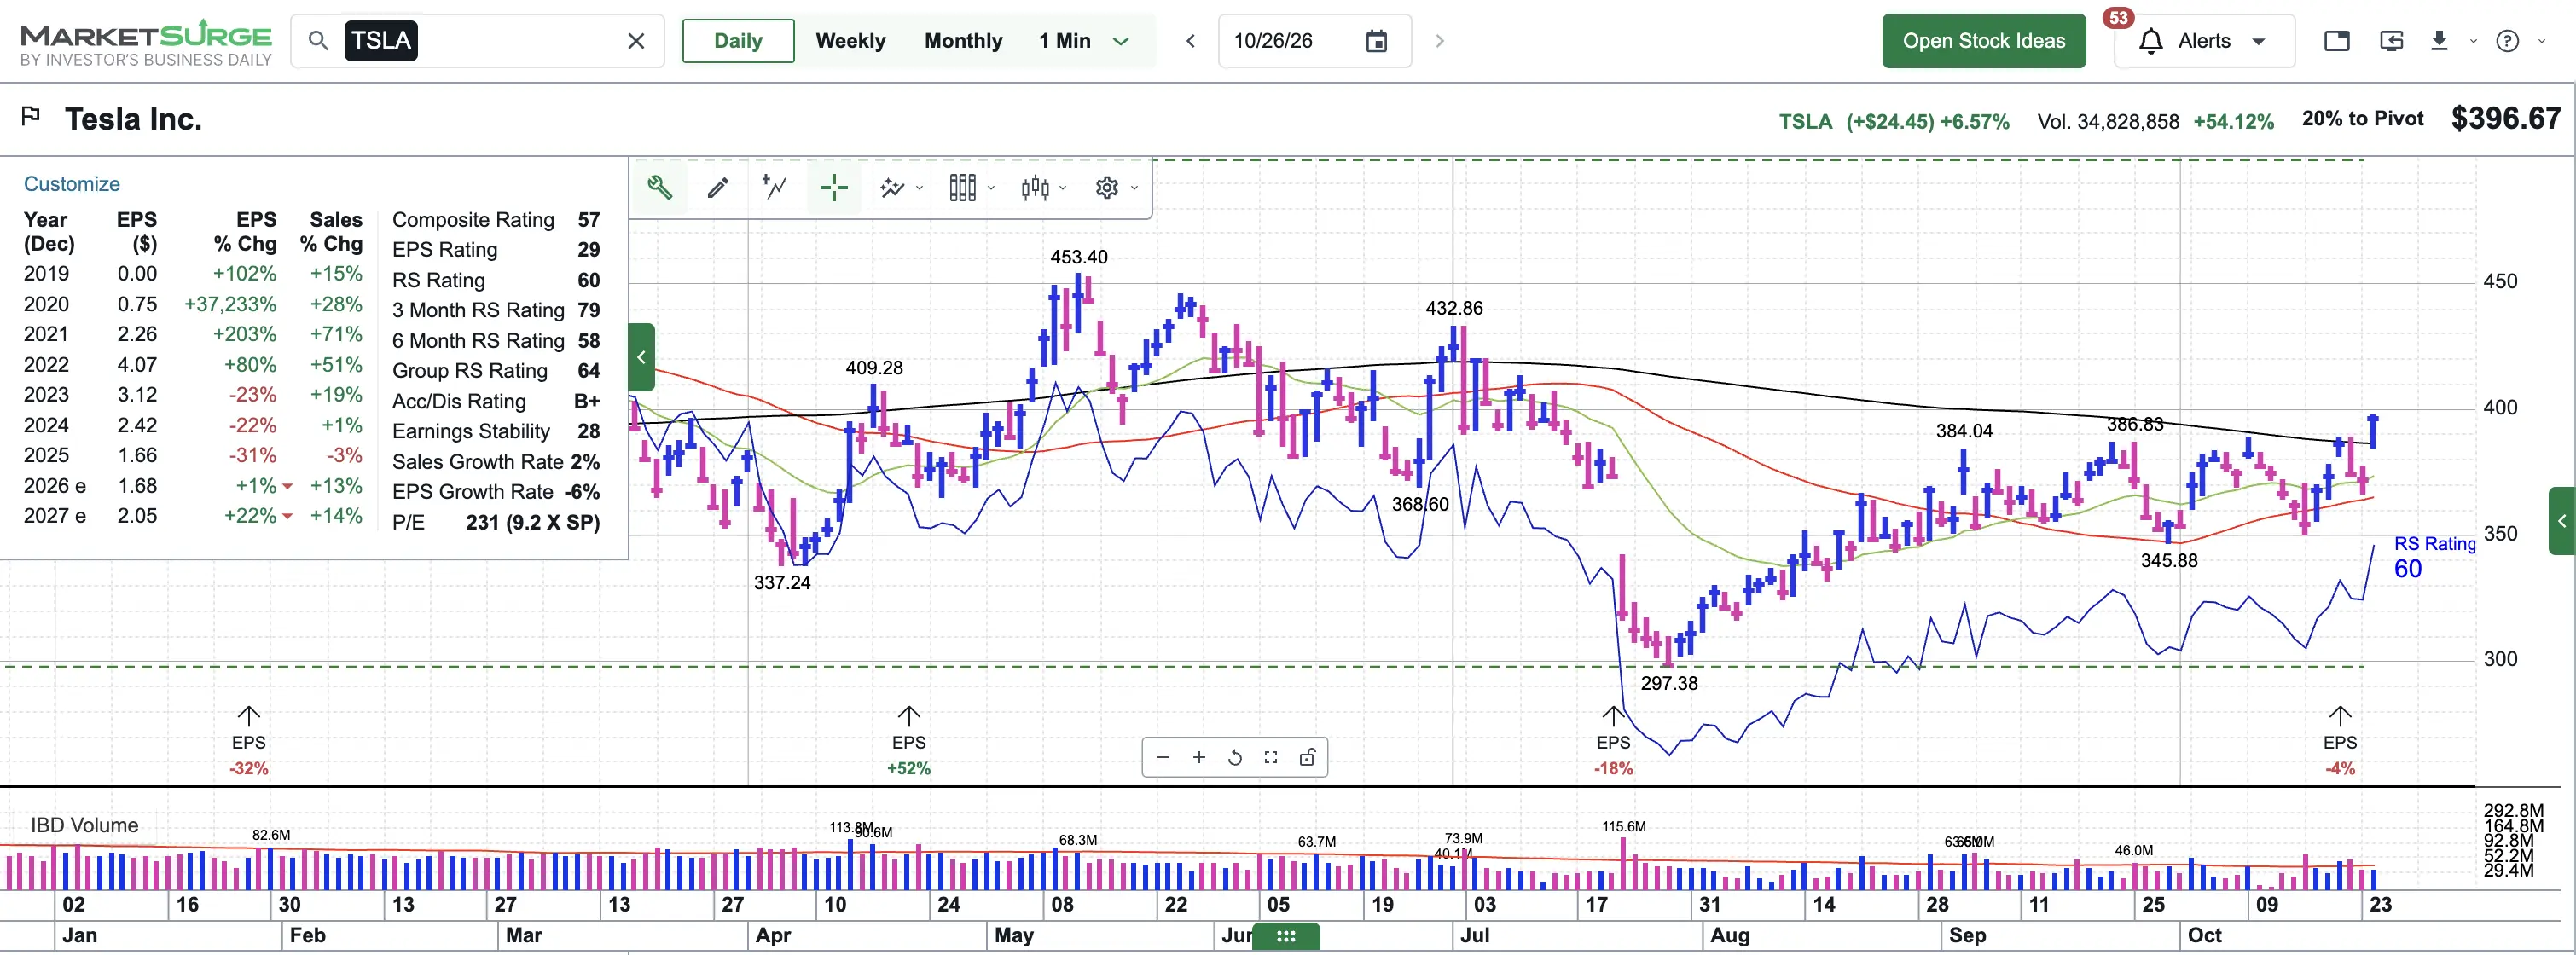
本ページは調査目的であり、投資助言ではありません。モデルは誤ることがあります。過去の実績は将来の成果を保証しません。