A
Allen Holding Inc.
+ 持有SPCX
+13.94%
3個月報酬率
$147.960
+1.953 (+1.32%)收盤時
Space Exploration Technologies Corp. designs, manufactures, launches, and operates products and services built on technologies, including rockets and spacecraft. The Company's segments include Space, Connectivity, and AI. Its Space segment designs, manufactures, and launches reusable rockets to provide access to space. Its Connectivity segment operates broadband data and communications network powered by approximately 10,200 Starlink broadband and mobile satellites in Low-Earth orbit, delivering connectivity to consumer, enterprises, and government customers over 167 countries, territories, and other markets. In its AI (artificial intelligence) segment, it operates a vertically integrated AI platform spanning its truth-seeking frontier model Grok, AI solutions for consumer and enterprise customers, X-its real-time information, entertainment, and free-speech platform and AI computational infrastructure.
Space Exploration Technologies Corp (SPCX) is currently trading at $146.03, which is significantly lower than the analyst price targets of $230 to $300. However, the stock has a low Relative Strength Index (RSI) of 27.46, indicating it may be oversold, but the recent performance shows a 5-day change of -10.17% and a year-to-date change of +569.56%. The main risk is the negative earnings trend with a forward P/E of 200 and a net income loss of $541 million in Q2 2026. While there are potential catalysts from upcoming earnings and analyst optimism, the current volatility and market sentiment suggest holding rather than buying.
SpaceX's Record IPO Faces Shareholder Lockup Expiry Pressure
Zelenskyy to Meet US Envoys Amid Rising Tensions
Comparing Tesla and SpaceX's Performance Over the Next Five Years
Tech Stocks Rebound as Investors Return to Market
Nasdaq Rises, 3M and GM Show Diverging Performance
Space Exploration Technologies Corp. designs, manufactures, launches, and operates products and services built on technologies, including rockets and spacecraft. The Company's segments include Space, Connectivity, and AI. Its Space segment designs, manufactures, and launches reusable rockets to provide access to space. Its Connectivity segment operates broadband data and communications network powered by approximately 10,200 Starlink broadband and mobile satellites in Low-Earth orbit, delivering connectivity to consumer, enterprises, and government customers over 167 countries, territories, and other markets. In its AI (artificial intelligence) segment, it operates a vertically integrated AI platform spanning its truth-seeking frontier model Grok, AI solutions for consumer and enterprise customers, X-its real-time information, entertainment, and free-speech platform and AI computational infrastructure. It operates in the Technology sector.
Space Exploration Technologies Corp (SPCX) is currently trading at $146.03, which is significantly lower than the analyst price targets of $230 to $300. However, the stock has a low Relative Strength Index (RSI) of 27.46, indicating it may be oversold, but the recent performance shows a 5-day change of -10.17% and a year-to-date change of +569.56%. The main risk is the negative earnings trend with a forward P/E of 200 and a net income loss of $541 million in Q2 2026. While there are potential catalysts from upcoming earnings and analyst optimism, the current volatility and market sentiment suggest holding rather than buying.
🚀 #EarningsSeason SpaceX stock jumped in after-hours trading as soon as its earnings came out! Last night, Musk's SpaceX (SPCX) delivered a fairly explosive third-quarter report: 📈 Revenue up 161% year over year, reaching $14.58 billion 💰 Net profit reached $4.4 billion 🔥 After the report was released, the stock rose about 5.15% in after-hours trading But what's most worth watching isn't just how much the stock rose, but the logic behind it: the AI computing power business is becoming a new growth engine. This also makes me think about a question: During earnings season, are we buying past performance or future expectations? Sometimes a company's results really are good, but the stock price has already risen in advance; sometimes earnings only slightly beat expectations, yet the market may still deliver a surprise. So good earnings don't necessarily mean the stock will rise. The key is also how high the market's expectations were beforehand, and how much premium capital is willing to pay for future growth. Do you think this rally in SpaceX reflects strong performance, or is the AI story once again igniting market sentiment? $SPCX
展開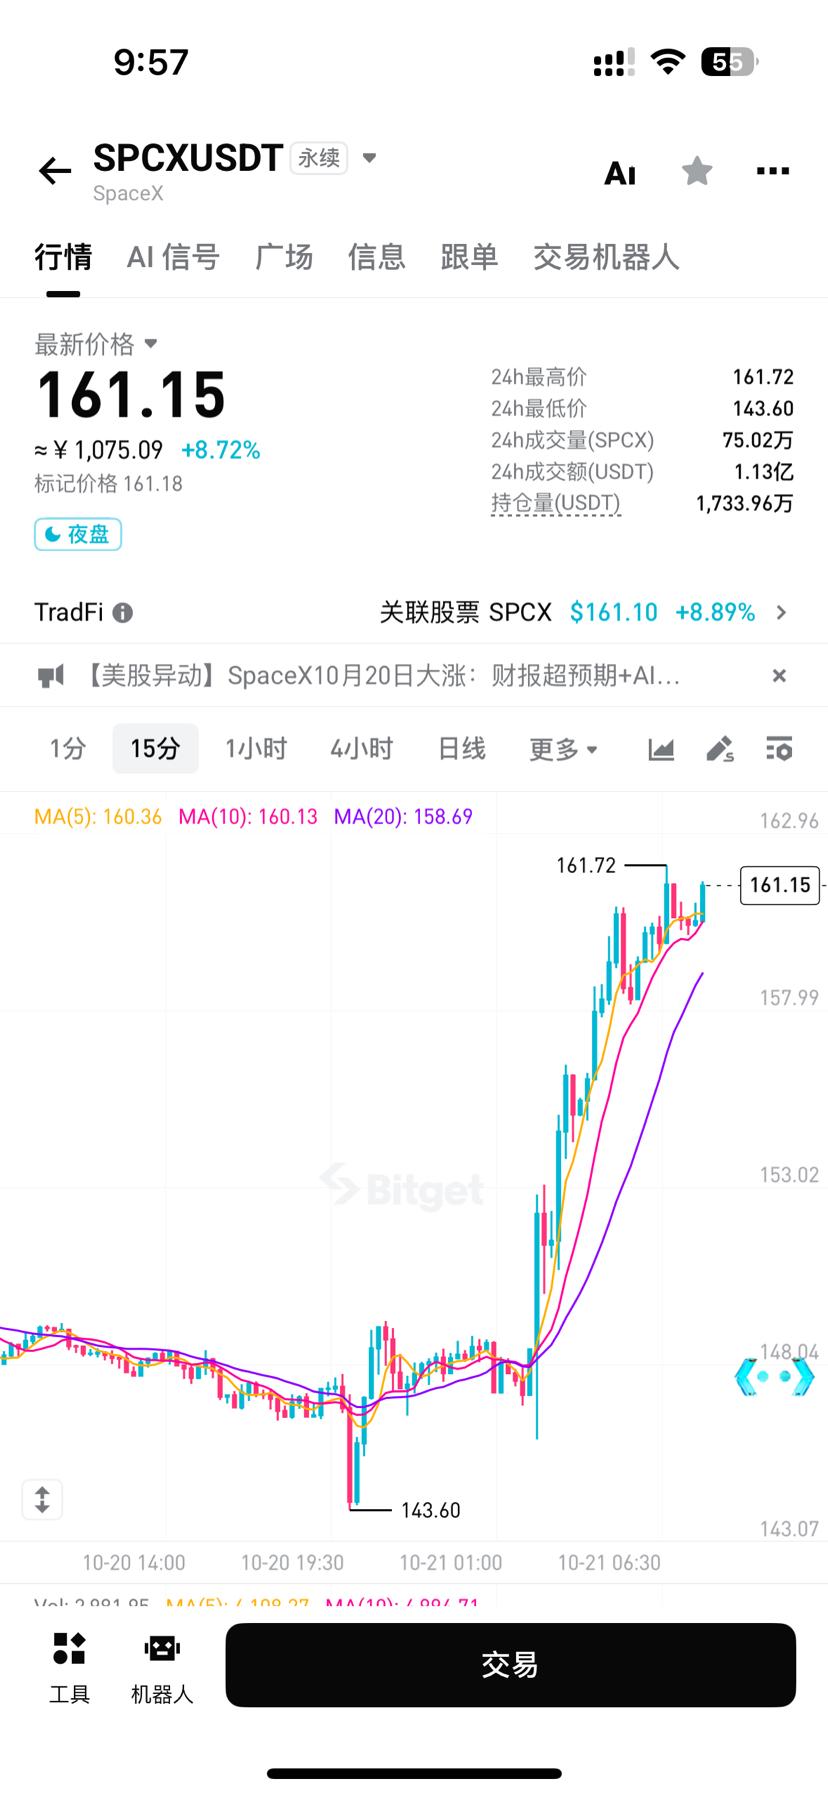
#Strive Holdings Surpass 25,000 BTC #ShareWeekly Here is an analysis of the core market dynamics and signals from these recent developments: 1. Strive's Bitcoin treasury strategy (36,818 BTC) Strive acquired 1,223 BTC for approximately $100M at an average price of about $81,734 per coin, bringing its total reserves to 36,818 BTC (valued at over $3 billion). * Institutional recognition and supply absorption: Dedicated treasury vehicles continue to buy, reflecting organized and price-insensitive demand. Strive actively absorbs exchange liquidity supply by aggressively issuing equity and capital market instruments (such as its $630M preferred stock offering) to purchase spot Bitcoin. * Macro signal: Continued corporate accumulation reinforces the view that institutions see Bitcoin as a long-term strategic reserve asset to hedge against fiat dilution. This indicates market confidence in prices rising above $80,000. * Impact on expectations: As Strive consolidates its position as one of the largest publicly traded BTC holders, it creates upward pressure on the baseline price floor and encourages other mid-market treasury projects to follow this model. 2. Tesla Q3 earnings: Deliveries and margin outlook The market will closely assess whether Tesla's margin trends can keep pace with growing volume expectations: * Automotive margins (excluding credits): Analysts are watching whether lower production costs (RAM improvements, battery cell scaling, Cybertruck production efficiency gains) can offset the significant price cuts and promotional incentives adopted this quarter. * FSD and AI monetization: Any upside surprise could come from high-margin recurring software revenue (Full Self-Driving subscriptions/transfers) and clear details on the regulatory roadmap for Robotaxi operations. * Delivery rebound: Meeting or exceeding delivery targets would indicate stable global baseline demand, but market focus remains entirely on the non-GAAP gross margin trajectory. 3. SpaceX performance: Revenue and Starlink growth momentum Although SpaceX is not yet public, its valuation metrics depend heavily on Starlink expansion and launch frequency: * Starlink growth engine: Starlink accounts for the majority of total revenue. Reaching key active subscriber milestones (and expanding into enterprise, maritime, and aviation segments) is critical to achieving operating leverage. * Free cash flow generation: Strong subscriber growth translates directly into predictable high-margin subscription cash flow, offsetting substantial capital expenditure for Starship development and Starlink constellation deployment. * Valuation impact: Sustained operational execution will reinforce private market pricing and maintain positive sentiment across the broader tech supply chain. 4. Market micro trends: Gate and Unitree Robotics * Gate transparency report: In crypto infrastructure, monthly proof-of-reserves and transparency updates are key indicators of platform liquidity and user trust. High reserve coverage ratios (>100%) help stabilize counterparty risk across the broader exchange landscape. * Unitree Robotics up 18%: Momentum in embodied AI and humanoid robotics reflects increasing institutional capital allocation to the convergence of hardware and AI. Unitree's rally highlights investor enthusiasm for mass-market commercialization of humanoid robots and low-cost quadruped robot manufacturing. My take: Strive's continued accumulation of 36,818 $BTC reinforces the long-term Bitcoin treasury narrative. It shows growing corporate confidence in Bitcoin as a treasury asset, though sustained buying alone does not guarantee price appreciation. The key question is whether other companies will adopt the same strategy. Tesla's Q3 report will hinge on delivery growth, automotive margins, and forward guidance. Strong deliveries combined with margin improvement could lift market sentiment, while weak demand or pricing pressure could weigh on expectations. For SpaceX, revenue growth and Starlink's expanding user base are the key metrics. The market will watch whether subscriber growth can translate into stronger recurring revenue and sustainable profitability. Meanwhile, Gate's September transparency report is important for assessing reserve transparency and user confidence, while Unitree Robotics' 18% gain highlights investor interest in robotics and embodied AI. My overall view: corporate Bitcoin accumulation, electric vehicles, satellite connectivity, exchange transparency, and robotics are five distinct themes, but they share one common driver: investor confidence in long-term growth. The real catalyst will be the fundamentals behind the headlines, not just the headlines themselves. $MU $SPCX $TSLA $BTC
展開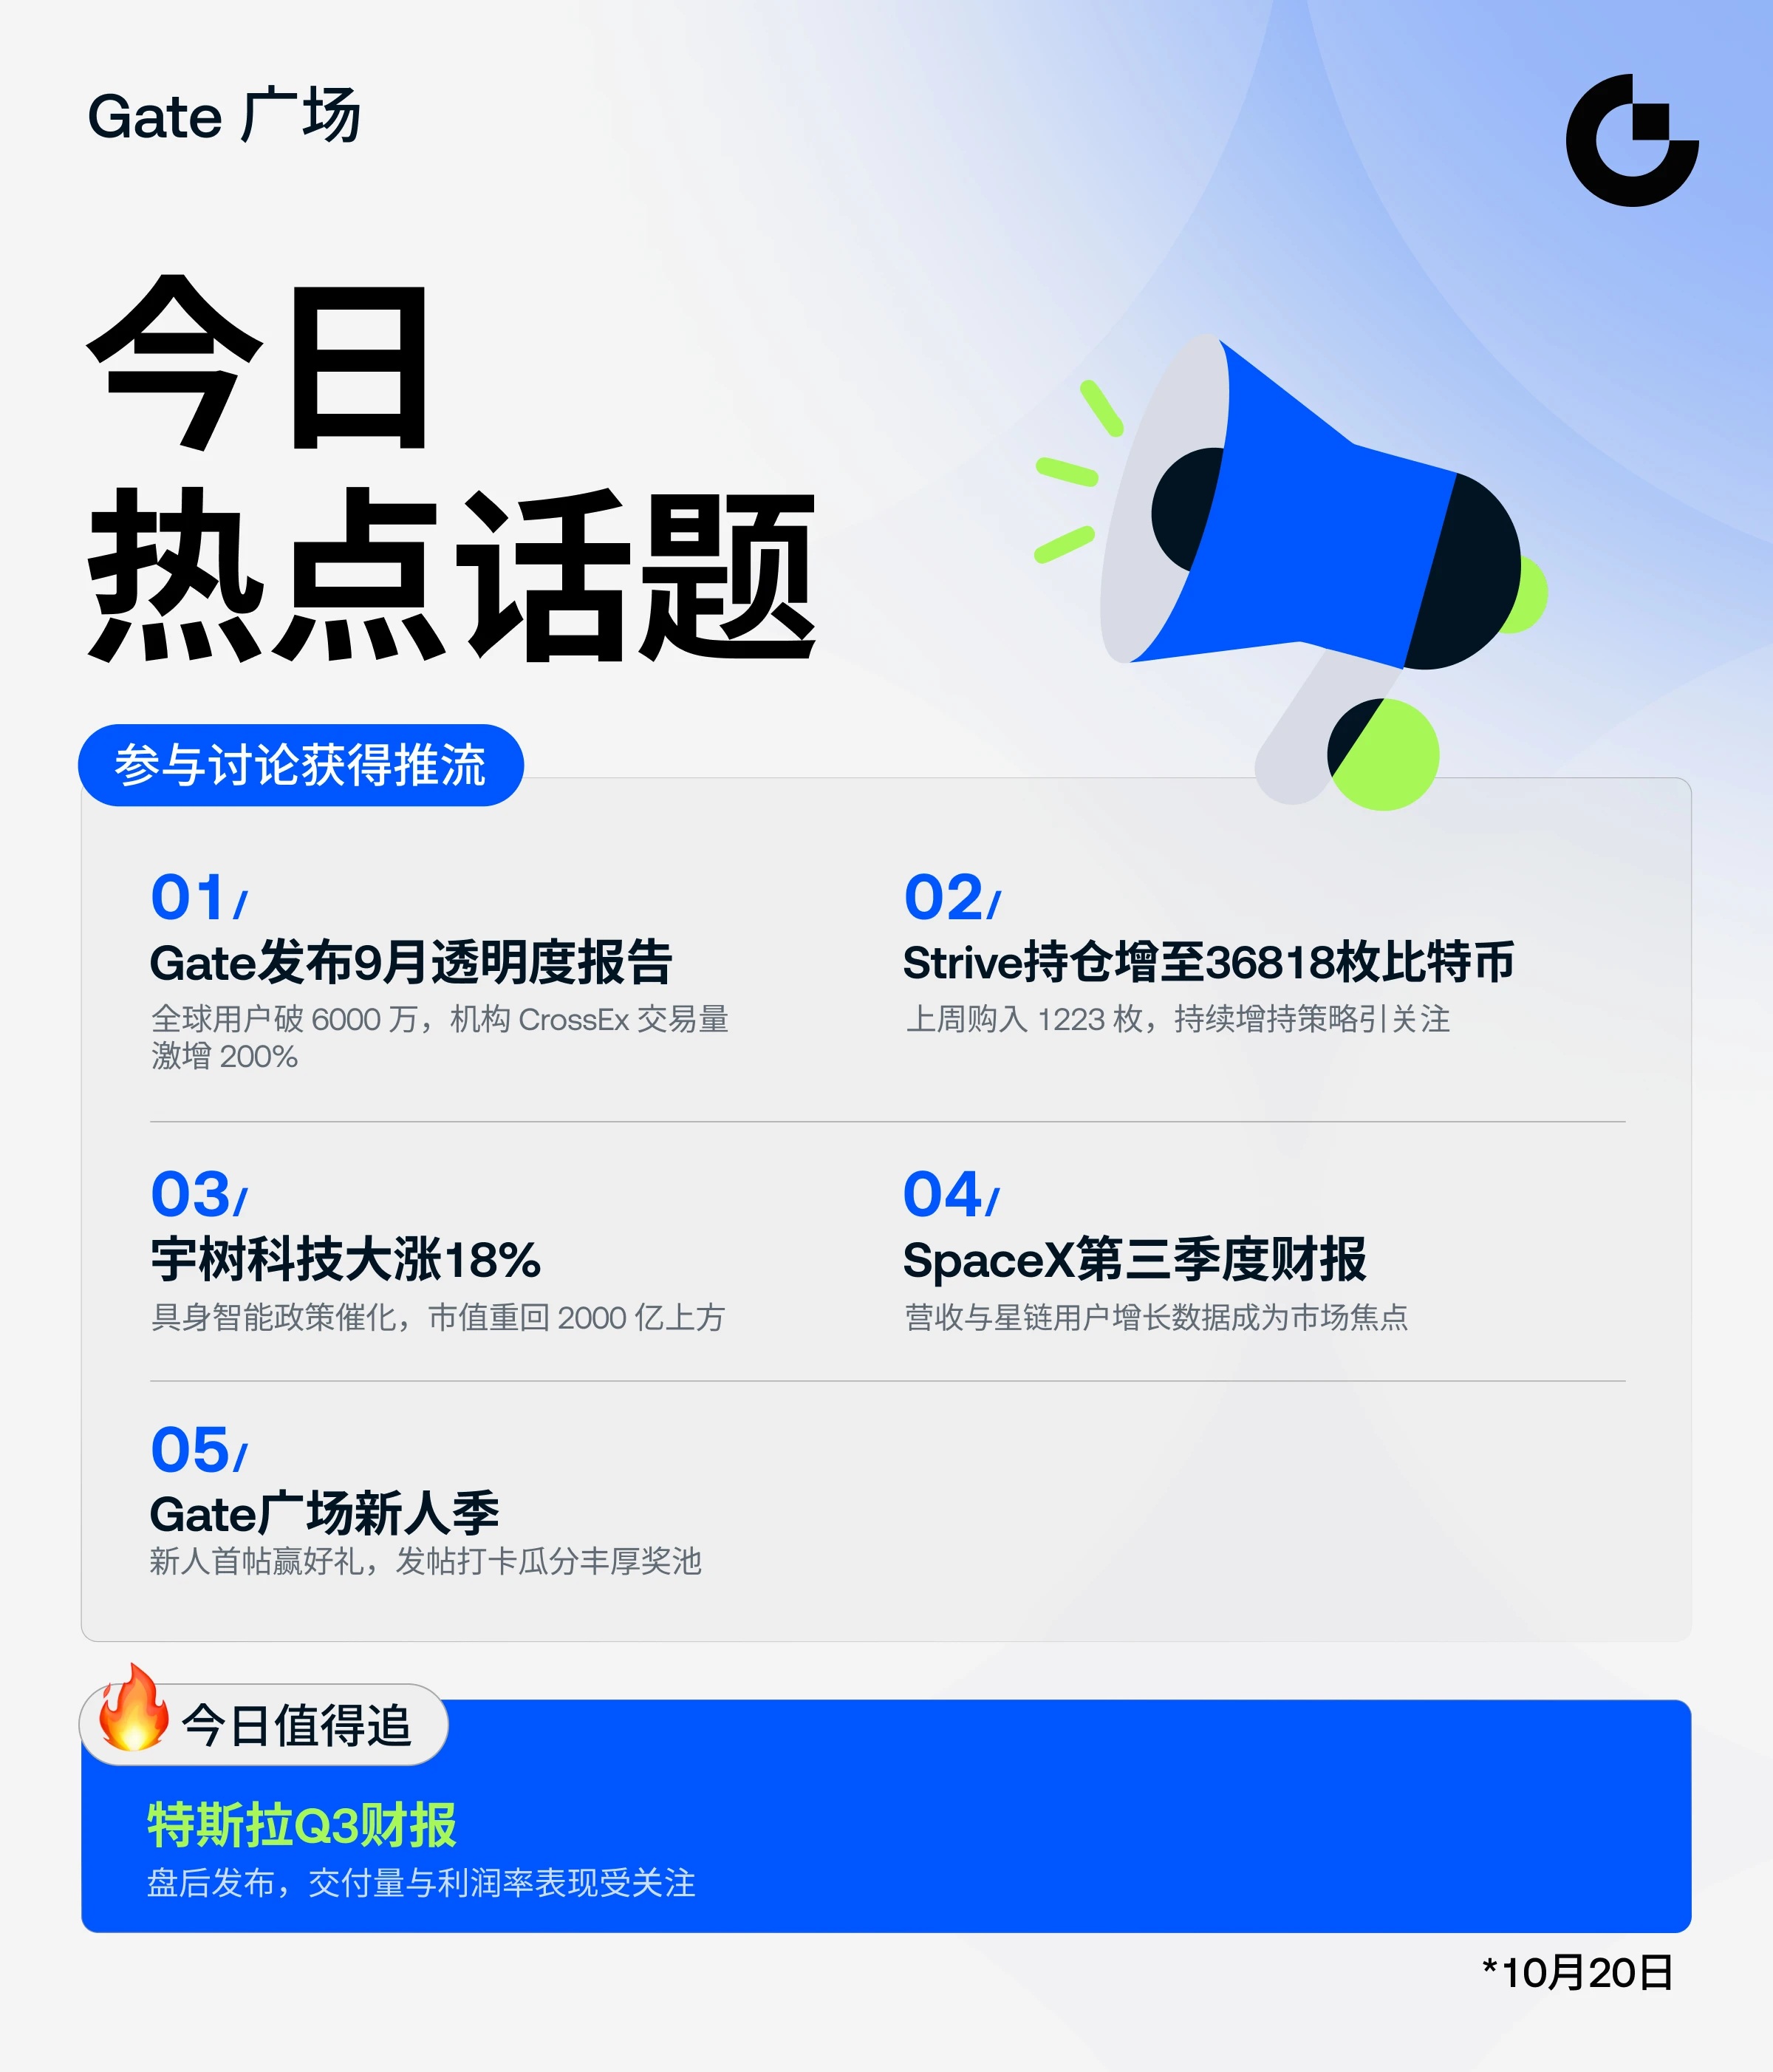
$BTC $SPCX SPCX (SpaceX) Q3 Earnings Highlights ✅ Key Data (2026 Q3) - Revenue $14.575 billion, up 161% year-over-year - Net profit $4.404 billion, turning profitable (a loss of $1.054 billion in the same period last year) - Adjusted EBITDA $8.809 billion, up 306% year-over-year 🔥 Biggest highlight: Superintelligence (AI) business revenue $7.56 billion, up 830% year-over-year, surpassing Starlink for the first time to become the largest revenue source, driven by cloud orders, the Cursor acquisition, and computing power business. Starlink continues steady growth; the rocket launch business contributed incremental gains. #EarningsSeason #JPMorganPredictsBitcoinToLeadForNextDecade #BTC (BTCUSDT)
展開
本頁僅供研究參考,不構成投資建議。模型可能出錯。過往表現不代表未來結果。