
乐
乐观
乐观 · 25%ADBE
$567.01
情景价格
$263.820
-6.569 (-2.49%)收盘时
Adobe Inc. is a global technology company. The Company's Solutions enable digital experiences, starting with the first creative spark, to the creation and development of all content and media, to the personalized delivery across every channel. Its segments include Digital Media, Digital Experience, and Publishing and Advertising. The Digital Media segment provides products and services that allow individuals, teams, businesses, and enterprises to create, publish, and promote content, and to work with documents and creative content across different workflows. The Digital Experience segment provides an integrated platform set of products, services and solutions that enable businesses to create, manage, execute, measure, monetize & optimize customer experiences. The Publishing and Advertising segment contains legacy products and services that address diverse market opportunities, including eLearning solutions, technical document publishing, web conferencing, document and forms platforms.
Adobe Inc is not a good buy right now. The current price is $245.20, which is above the recent analyst downgrade target of $225 from Wells Fargo. The stock has a forward P/E of 8.726, indicating potential undervaluation, but the negative sentiment from analysts and a significant insider selling increase of 3770.10% raises concerns. Additionally, the stock is down 26.43% year-to-date, reflecting ongoing challenges in growth and market confidence.
情景价格取自当年最后一个月度预测区间。概率为固定的模型权重(25 / 50 / 25),不构成保证。
Adobe vs. Salesforce: Cloud Market Dominance Analysis
Investment Analysis: Adobe vs. CrowdStrike
Investment Comparison: Adobe vs. Arista Networks Amid AI Shift
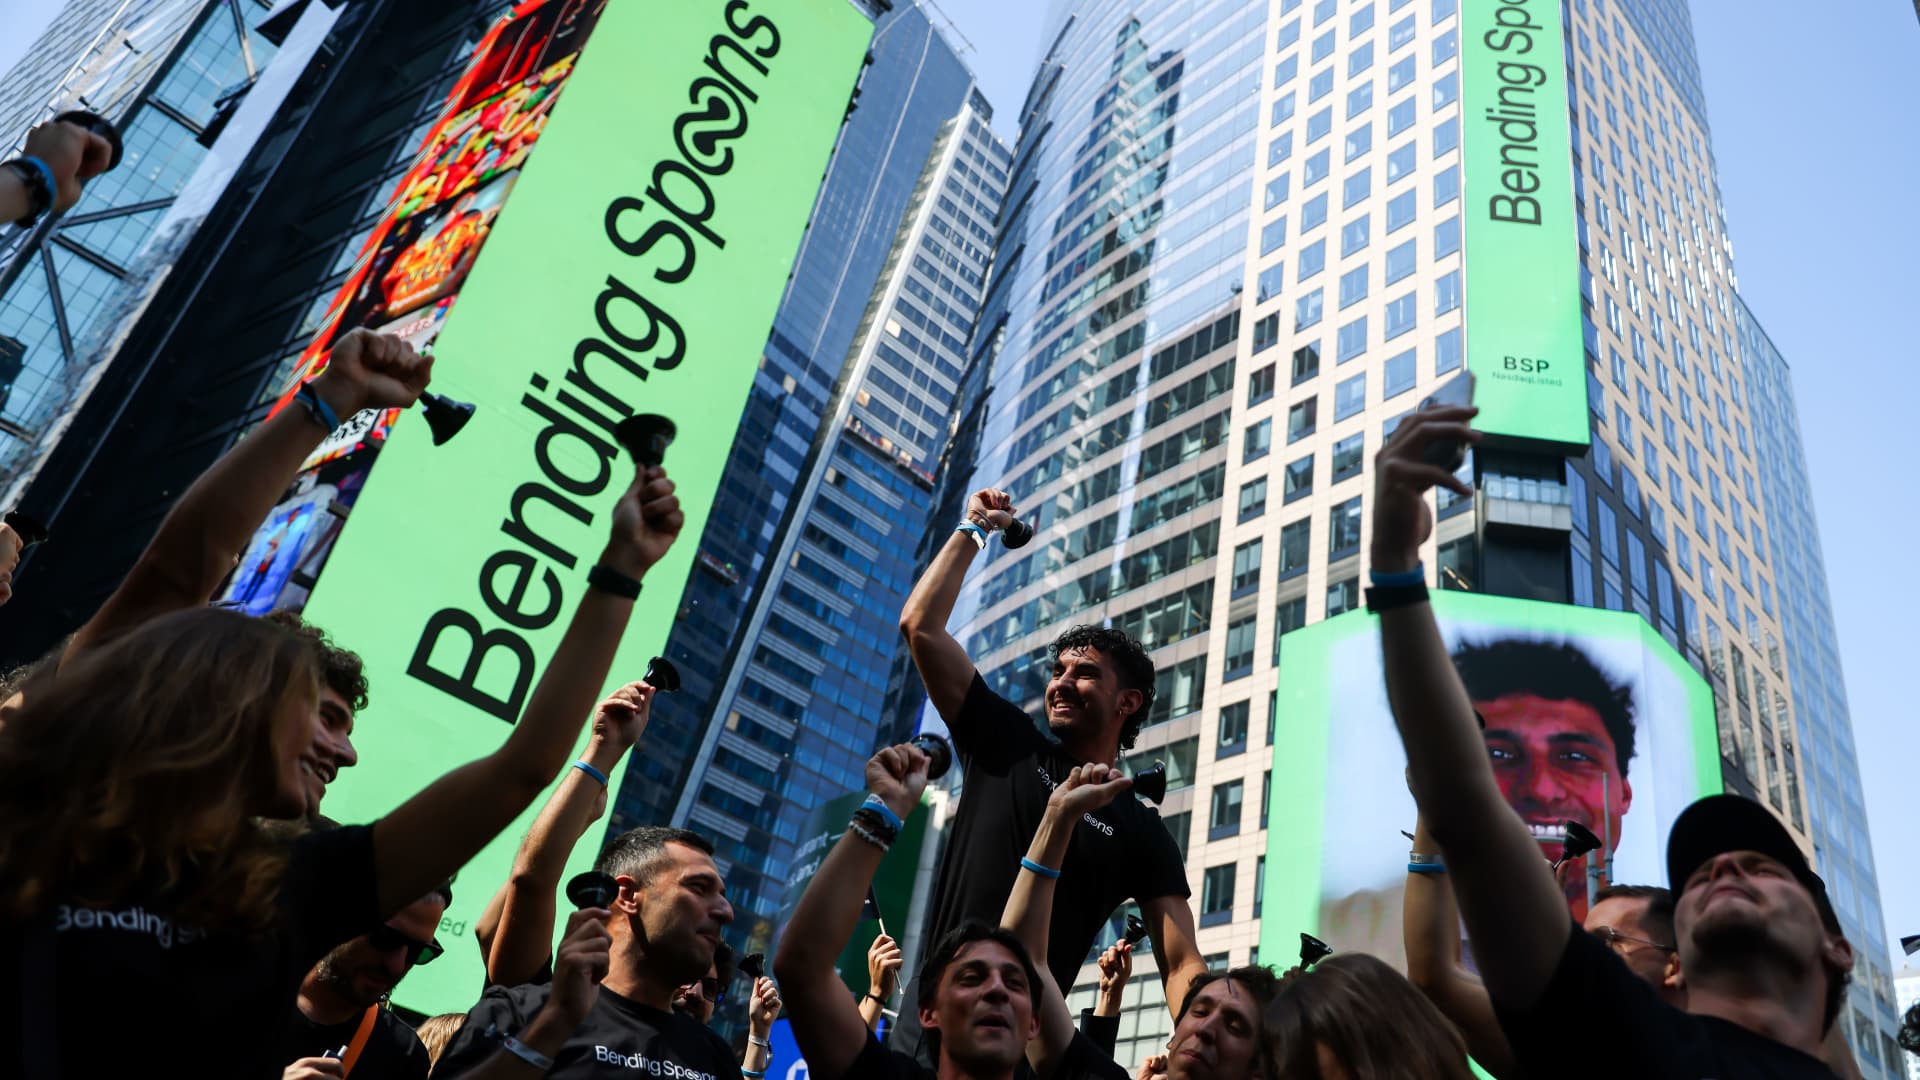
Bending Spoons Secures Buffett Investment Post-IPO

Bending Spoons Accelerates Software Acquisitions Amid AI Boom
Adobe Inc. is a global technology company. The Company's Solutions enable digital experiences, starting with the first creative spark, to the creation and development of all content and media, to the personalized delivery across every channel. Its segments include Digital Media, Digital Experience, and Publishing and Advertising. The Digital Media segment provides products and services that allow individuals, teams, businesses, and enterprises to create, publish, and promote content, and to work with documents and creative content across different workflows. The Digital Experience segment provides an integrated platform set of products, services and solutions that enable businesses to create, manage, execute, measure, monetize & optimize customer experiences. The Publishing and Advertising segment contains legacy products and services that address diverse market opportunities, including eLearning solutions, technical document publishing, web conferencing, document and forms platforms. It operates in the Technology sector (SERVICES-PREPACKAGED SOFTWARE industry).
Adobe Inc is not a good buy right now. The current price is $245.20, which is above the recent analyst downgrade target of $225 from Wells Fargo. The stock has a forward P/E of 8.726, indicating potential undervaluation, but the negative sentiment from analysts and a significant insider selling increase of 3770.10% raises concerns. Additionally, the stock is down 26.43% year-to-date, reflecting ongoing challenges in growth and market confidence.
$ADBE has one billion users, and the stock is still down 29.6% YTD, even though the company beat third-quarter profit and revenue estimates and raised its full-year financial outlook. Morningstar gives $ADBE a 4-star rating and a fair value estimate of $344 per share, viewing the stock as currently undervalued.
展开
$ADBE Adobe price target raised to $255 from $225 at UBS UBS raised the firm's price target on Adobe to $255 from $225 and keeps a Neutral rating on the shares.
展开$ADBE JPMorgan lowered its Adobe price target to $315 from $340 while keeping an Overweight rating on the shares. The company's fiscal Q3 results were "robust and beat expectations modestly," the analyst tells investors in a research note. However, JPMorgan says Adobe's Q4 revenue outlook tracked modestly below consensus given its focus on user acquisition. Despite a deceleration in revenue growth in fiscal 2027, the shares are inexpensive and offer a "low bar for upsides to the share price from a recovery in monetization," contends the firm.
展开
本页仅供研究参考,不构成投资建议。模型可能出错。过往表现不代表未来结果。