
B
Bull
Bull · 25%ULCC
$5.65
Scenario price
$5.580
-0.098 (-1.76%)At close
Frontier Group Holdings, Inc. is a holding company. The Company operates through its subsidiary, Frontier Airlines, Inc., which is an ultra-low-cost carrier company. The Company offers flights throughout the United States and to select near international destinations in the Americas. It has a fleet of approximately 176 Airbus single-aisle aircraft, consisting of overe A320ceos, 89 A320neos, 21 A321ceos and 60 A321neos. The Company primarily provides air transportation for passengers. It provides passenger airline service primarily to leisure travelers. It combines its fares with flexible optional services for an additional cost. Such additional options include carry-on and checked baggage, advance seat selection, extended-legroom premium seats, priority boarding and ticket changes and cancellations, as well as bundled options combining various optional services. The Company serves approximately 100 airports throughout the United States and international destinations in the Americas.
Frontier Group Holdings Inc is not a good buy right now due to several concerning factors. The current price is $5.86, which is below the recently downgraded analyst price target of $6. Additionally, the stock has a low RSI of 37.99, indicating it is oversold and may not have immediate upward momentum. The company has also faced significant profitability challenges, with a net income loss of $90 million in Q2 2026 and a forward P/E of 11.70, suggesting potential overvaluation given its current financial struggles. The main risk is the high insider selling activity, which has increased by 1398.78% over the last month, signaling a lack of confidence from those closest to the company.
Scenario prices are the last monthly forecast band of the current year. Probabilities are fixed model weights (25 / 50 / 25), not guarantees.
Frontier Airlines Plans to Introduce First-Class Seats
Frontier Airlines Launches Flexible Cancel for Any Reason Service
High-Flying Stocks Facing Challenges
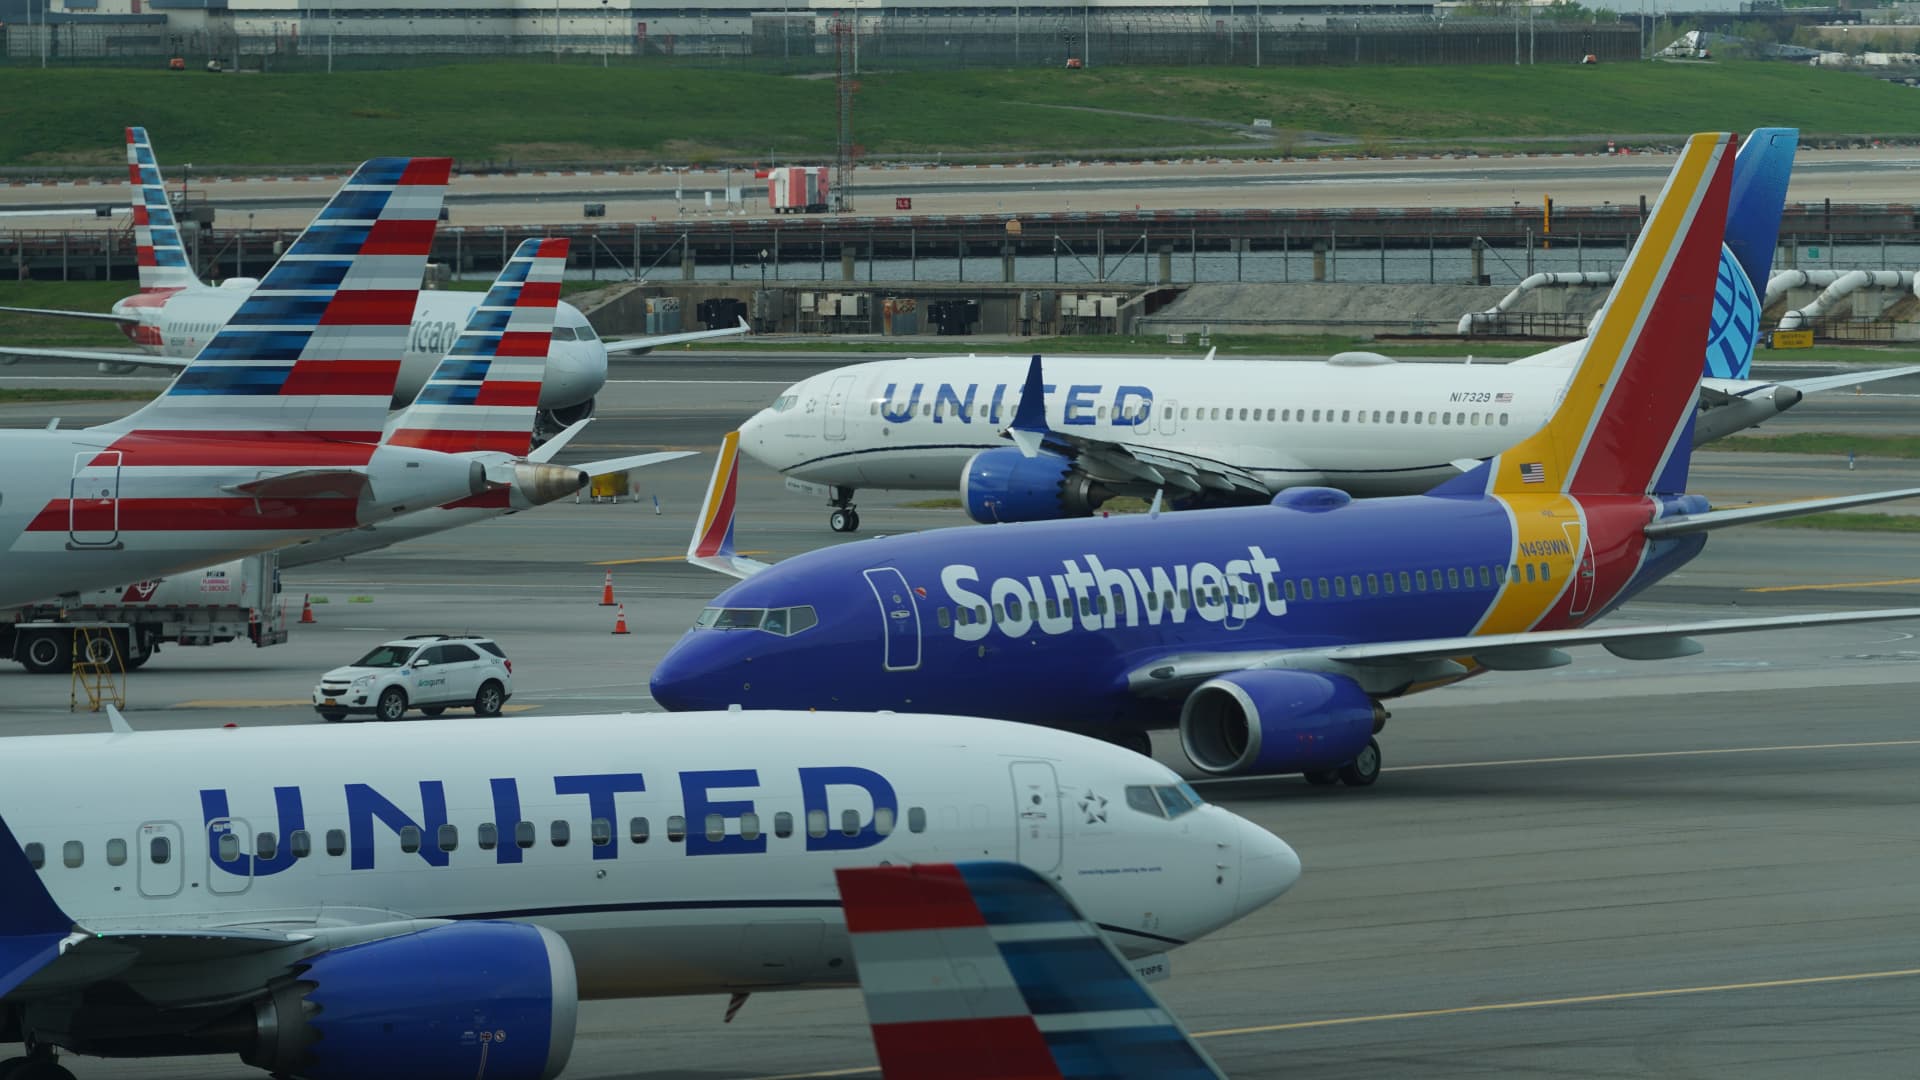
U.S. Airfares Surge 26.5% Amid Rising Costs
Frontier Group Holdings Q2 2026 Earnings Call Highlights
Frontier Group Holdings, Inc. is a holding company. The Company operates through its subsidiary, Frontier Airlines, Inc., which is an ultra-low-cost carrier company. The Company offers flights throughout the United States and to select near international destinations in the Americas. It has a fleet of approximately 176 Airbus single-aisle aircraft, consisting of overe A320ceos, 89 A320neos, 21 A321ceos and 60 A321neos. The Company primarily provides air transportation for passengers. It provides passenger airline service primarily to leisure travelers. It combines its fares with flexible optional services for an additional cost. Such additional options include carry-on and checked baggage, advance seat selection, extended-legroom premium seats, priority boarding and ticket changes and cancellations, as well as bundled options combining various optional services. The Company serves approximately 100 airports throughout the United States and international destinations in the Americas. It operates in the Industrials sector (AIR TRANSPORTATION, SCHEDULED industry).
Frontier Group Holdings Inc is not a good buy right now due to several concerning factors. The current price is $5.86, which is below the recently downgraded analyst price target of $6. Additionally, the stock has a low RSI of 37.99, indicating it is oversold and may not have immediate upward momentum. The company has also faced significant profitability challenges, with a net income loss of $90 million in Q2 2026 and a forward P/E of 11.70, suggesting potential overvaluation given its current financial struggles. The main risk is the high insider selling activity, which has increased by 1398.78% over the last month, signaling a lack of confidence from those closest to the company.
No posts yet
Sign up or log in to join the discussionThis page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.