強
強気
強気 · 25%UAA
$6.69
シナリオ価格
$4.880
+0.220 (+4.50%)終値時点
Under Armour, Inc. is an inventor, marketer and distributor of branded athletic performance apparel, footwear and accessories for men, women and youth. Its primary business operates in four geographic segments: North America, comprising the United States and Canada, Europe, the Middle East and Africa (EMEA), Asia-Pacific, and Latin America. Its apparel comes in three primary fit types: compression (tight fit), fitted (athletic fit) and loose (relaxed fit). Its footwear includes products for running, training, basketball, cleated sports, recovery and outdoor applications, as well as casual use. Its accessories primarily include athletic performance gloves, bags, headwear and socks. It sells its apparel, footwear and accessories in North America through wholesale and direct-to-consumer channels. It sells its apparel, footwear and accessories in EMEA primarily through wholesale customers and independent distributors, along with e-commerce Websites and brand and factory house stores.
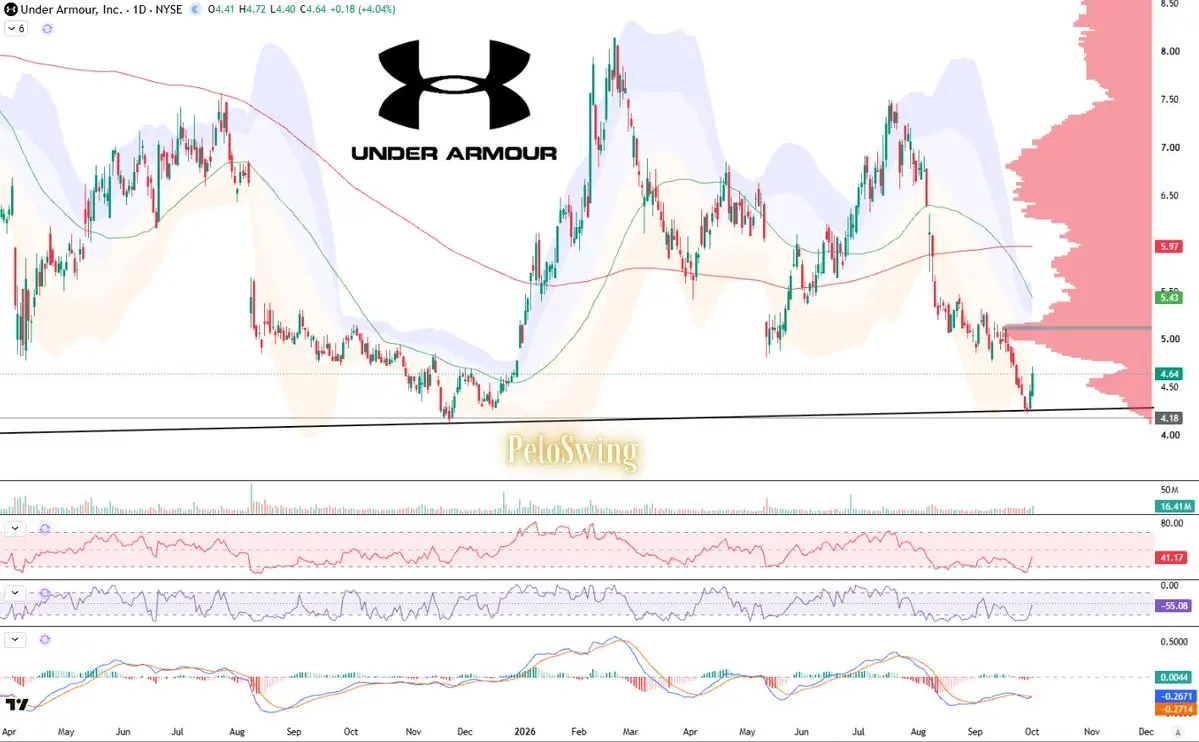
Under Armour Inc (UAA) is currently priced at $4.74, which is below several analyst price targets, including $5.50 from Baird and $8 from Williams Trading. However, the stock has a low RSI of 42.617, indicating it is nearing oversold territory, but it is not yet a strong buy signal. The company has shown a significant decline in net income, with a net loss of $430.83 million in Q3 2026, which raises concerns about its profitability. The forward P/E ratio is high at 47.39, suggesting that the stock may be overvalued relative to its earnings potential. The main risk is the company's declining gross margin, which has dropped to 42.29% in Q4 2026 from 57.01% in Q1 2026, indicating potential challenges in maintaining profitability. Overall, while there are some positive indicators, the risks currently outweigh the potential rewards, leading to a recommendation to hold.
Baird
$5.50
2026-09-14
Baird
2026-09-14
目標株価
$5.50
Morgan Stanley
$4
2026-09-10
Morgan Stanley
2026-09-10
目標株価
$4
Barclays
$5
2026-08-11
Barclays
2026-08-11
目標株価
$5
UBS
$9
2026-08-10
UBS
2026-08-10
目標株価
$9
BofA
—
2026-08-10
BofA
2026-08-10
目標株価
—
シナリオ価格は本年の最終月次予想レンジです。確率はモデルの固定ウェイト(25 / 50 / 25)であり、保証ではありません。
Luxury E-commerce Market Expands Rapidly
Curry Urges Focus on Basketball Essence in WNBA Leadership Transition
Kylian Mbappé Joins On Sportswear, Nike Loses Endorsement
AI Development Slowdown Triggers Market Volatility
Key Wall Street Rating Updates on Monday
Under Armour, Inc. is an inventor, marketer and distributor of branded athletic performance apparel, footwear and accessories for men, women and youth. Its primary business operates in four geographic segments: North America, comprising the United States and Canada, Europe, the Middle East and Africa (EMEA), Asia-Pacific, and Latin America. Its apparel comes in three primary fit types: compression (tight fit), fitted (athletic fit) and loose (relaxed fit). Its footwear includes products for running, training, basketball, cleated sports, recovery and outdoor applications, as well as casual use. Its accessories primarily include athletic performance gloves, bags, headwear and socks. It sells its apparel, footwear and accessories in North America through wholesale and direct-to-consumer channels. It sells its apparel, footwear and accessories in EMEA primarily through wholesale customers and independent distributors, along with e-commerce Websites and brand and factory house stores. It operates in the Consumer Cyclicals sector (APPAREL & OTHER FINISHD PRODS OF FABRICS & SIMILAR industry).
Under Armour Inc (UAA) is currently priced at $4.74, which is below several analyst price targets, including $5.50 from Baird and $8 from Williams Trading. However, the stock has a low RSI of 42.617, indicating it is nearing oversold territory, but it is not yet a strong buy signal. The company has shown a significant decline in net income, with a net loss of $430.83 million in Q3 2026, which raises concerns about its profitability. The forward P/E ratio is high at 47.39, suggesting that the stock may be overvalued relative to its earnings potential. The main risk is the company's declining gross margin, which has dropped to 42.29% in Q4 2026 from 57.01% in Q1 2026, indicating potential challenges in maintaining profitability. Overall, while there are some positive indicators, the risks currently outweigh the potential rewards, leading to a recommendation to hold.
33 analysts cover UAA: 4 rate it Buy, 19 Hold and 10 Sell. The average price target is 5.69.
本ページは調査目的であり、投資助言ではありません。モデルは誤ることがあります。過去の実績は将来の成果を保証しません。