
M
Manning & Napier Advisors, LLC
+ Con en carteraWFG
+6.49%
Rentabilidad a 3 meses
$67.020
+0.637 (+0.95%)Al cierre
West Fraser Timber Co. Ltd. is a Canada-based diversified wood products company. The Company is engaged in manufacturing, selling, marketing and distributing lumber, engineered wood products such as oriented strand board (OSB), laminated veneer lumber (LVL), medium-density fiberboard (MDF), plywood, particleboard, pulp, newsprint, wood chips and other residuals. Its products are used in home construction, repair and remodeling, industrial applications, paper and tissue. Its segments include Lumber, North America engineered wood products (NA EWP), Pulp & Paper and Europe EWP. The Company’s business comprises lumber mills, OSB facilities, plywood facilities, MDF facilities, particleboard facilities, LVL facilities, veneer facilities, and pulp and paper mills. The Company operates approximately 58 facilities in Canada, the United States, the United Kingdom and Europe.
West Fraser Timber Co Ltd is currently a hold. The stock is priced at $65.40, with a forward P/E of 51.81, indicating high valuation concerns. The RSI is at 49.99, suggesting the stock is neither overbought nor oversold, while the gross margin has decreased to 17.29%, reflecting profitability challenges. The main risk is the company's significant net loss of $188 million in Q1 2026, which raises concerns about its financial health and future earnings potential.
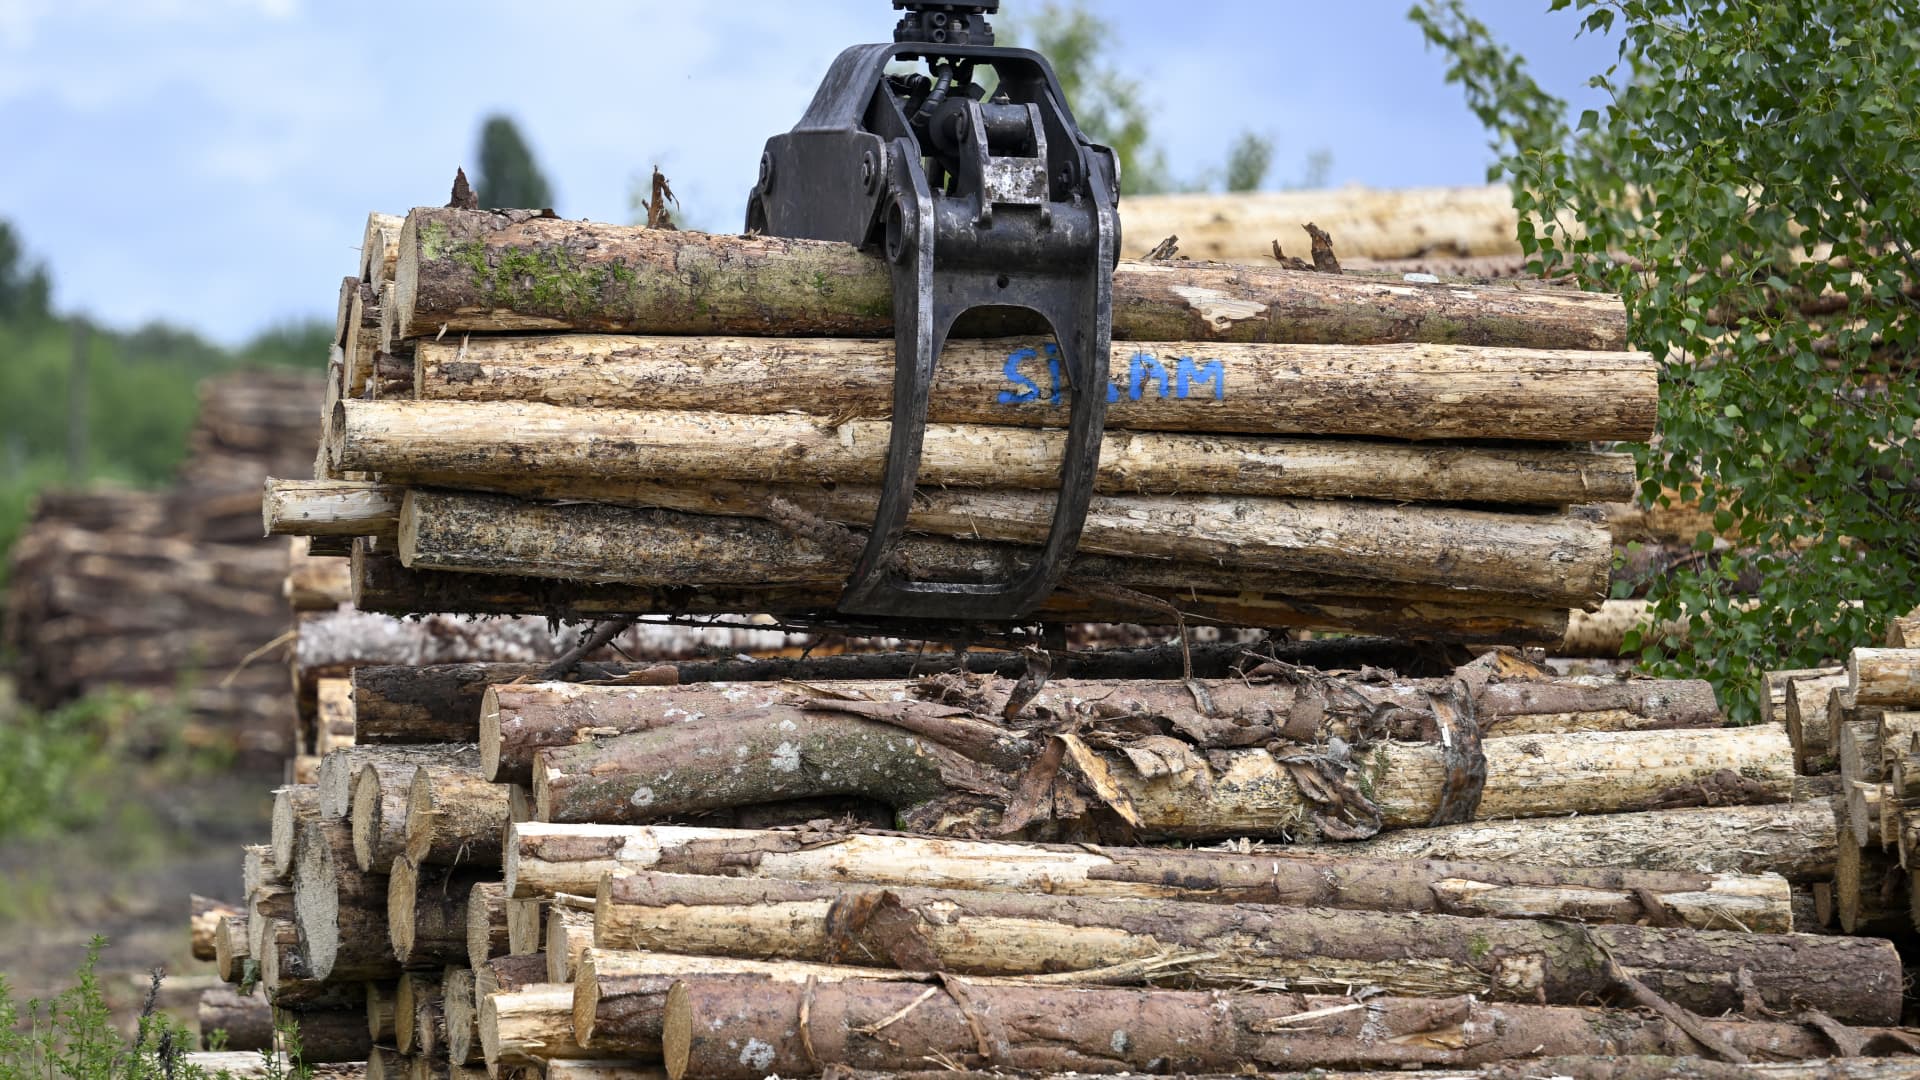
Market Trends in Timber Investment Analysis

West Fraser to Host Analyst Conference Call on Q3 Results
West Fraser Secures $500 Million Term Loan for Financial Flexibility

West Fraser Secures $500 Million Term Loan to Enhance Liquidity
West Fraser Timber Reports Wider Q2 Loss
West Fraser Timber Co. Ltd. is a Canada-based diversified wood products company. The Company is engaged in manufacturing, selling, marketing and distributing lumber, engineered wood products such as oriented strand board (OSB), laminated veneer lumber (LVL), medium-density fiberboard (MDF), plywood, particleboard, pulp, newsprint, wood chips and other residuals. Its products are used in home construction, repair and remodeling, industrial applications, paper and tissue. Its segments include Lumber, North America engineered wood products (NA EWP), Pulp & Paper and Europe EWP. The Company’s business comprises lumber mills, OSB facilities, plywood facilities, MDF facilities, particleboard facilities, LVL facilities, veneer facilities, and pulp and paper mills. The Company operates approximately 58 facilities in Canada, the United States, the United Kingdom and Europe. It operates in the Basic Materials sector (SAWMILLS AND PLANING MILLS, GENERAL industry).
West Fraser Timber Co Ltd is currently a hold. The stock is priced at $65.40, with a forward P/E of 51.81, indicating high valuation concerns. The RSI is at 49.99, suggesting the stock is neither overbought nor oversold, while the gross margin has decreased to 17.29%, reflecting profitability challenges. The main risk is the company's significant net loss of $188 million in Q1 2026, which raises concerns about its financial health and future earnings potential.
Aún no hay publicaciones
Regístrate o inicia sesión para participarEsta página es solo para investigación y no constituye asesoramiento de inversión. Los modelos pueden equivocarse. El rendimiento pasado no garantiza resultados futuros.