U
Uber Technologies, Inc.
+ Con en carteraLIME
-16.87%
Rentabilidad a 3 meses
$26.190
-0.621 (-2.37%)Al cierre
Neutron Holdings, Inc. is engaged in the shared micromobility business. The Company provides convenient and reliable short-term rentals of e-scooters and e-bikes at an affordable price. Its platform combines proprietary hardware and software, data, tech-enabled operations, and government relations expertise. It operates in approximately 230 cities across 29 countries. Its Proprietary Hardware includes electric vehicle fleet consisting of e-scooters, e-bikes, and seated e-scooters, and operates on a free-floating model. Its proprietary technology stack seamlessly connects our hardware, software, and operations through the Rider App for riders, the Lime Supply App, and an Internet of Things (IoT) - enabled hardware system. Its platform harnesses data, such as rider behavior, operational workflows, and hardware/software diagnostics.
Lime appears to be a good buy right now due to its recent revenue growth, with Q2 2026 revenue reported at $304 million, a 24% increase year-over-year, and a gross margin of 26.21%. Additionally, analysts have set a price target of $40, suggesting a potential upside of 53% from the current price. However, the company is facing risks with a negative net income of $61.29 million for Q1 2026, which could impact investor sentiment.
Lime Reports Record Q2 2026 Revenue of $304 Million
Latest Wall Street Rating Updates
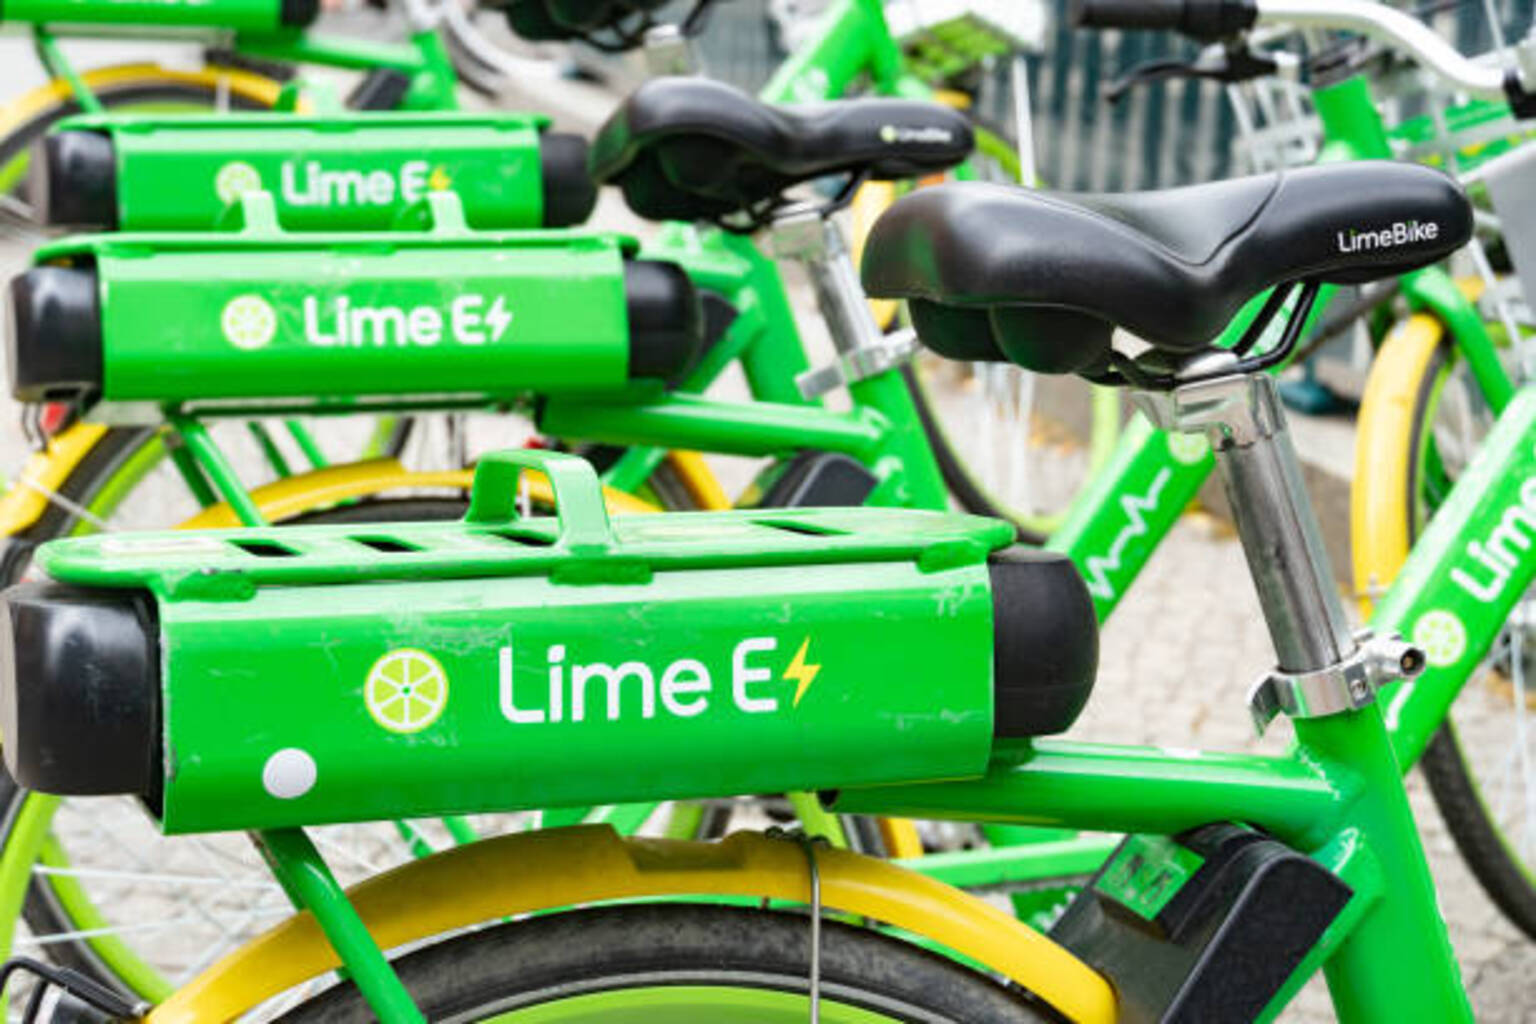
Lime's IPO Raises Over $170M, Valued at $1.66B
Three Major IPOs and Four SPACs Priced This Week
Chip Valuation Pullback Drags Tech Stocks Down
Neutron Holdings, Inc. is engaged in the shared micromobility business. The Company provides convenient and reliable short-term rentals of e-scooters and e-bikes at an affordable price. Its platform combines proprietary hardware and software, data, tech-enabled operations, and government relations expertise. It operates in approximately 230 cities across 29 countries. Its Proprietary Hardware includes electric vehicle fleet consisting of e-scooters, e-bikes, and seated e-scooters, and operates on a free-floating model. Its proprietary technology stack seamlessly connects our hardware, software, and operations through the Rider App for riders, the Lime Supply App, and an Internet of Things (IoT) - enabled hardware system. Its platform harnesses data, such as rider behavior, operational workflows, and hardware/software diagnostics. It operates in the Consumer Cyclicals sector.
Lime appears to be a good buy right now due to its recent revenue growth, with Q2 2026 revenue reported at $304 million, a 24% increase year-over-year, and a gross margin of 26.21%. Additionally, analysts have set a price target of $40, suggesting a potential upside of 53% from the current price. However, the company is facing risks with a negative net income of $61.29 million for Q1 2026, which could impact investor sentiment.
Aún no hay publicaciones
Regístrate o inicia sesión para participarEsta página es solo para investigación y no constituye asesoramiento de inversión. Los modelos pueden equivocarse. El rendimiento pasado no garantiza resultados futuros.