
P
Pt. Biro Klasifikasi Indonesia (Persero)
+ HältTLK
-26.27%
3-Monats-Rendite
$11.030
-1.510 (-13.69%)Zum Schluss
PT Telkom Indonesia (Persero) Tbk is an Indonesia-based telecommunication company. The Company is engaged in information and communication technology (ICT) services and telecommunications networks. Its segments include B2C, B2B Infra, B2B ICT, International, and Others. Its Business to Consumer (B2C) segment, comprises provision of telecommunications services to individual/residential customers, including mobile and fixed broadband services. Business-to-Business ICT (B2B ICT) provides system integration services, information technology services, and digital solutions to corporate and institutional customers. Its Business-to-Business Infrastructure (B2B Infra) offers management, and maintenance of telecommunications infrastructure, including telecommunications towers, fiber optic networks, backbone, data centers, and satellites. Its international Business segment provides international connectivity services and wholesale services to telecommunications operators and customers abroad.
Telkom Indonesia (TLK) is not a good buy right now due to significant recent losses and negative growth indicators. The stock has dropped 47.68% year-to-date and 14.03% over the last five days, indicating a strong downward trend. Additionally, the RSI is at a very low 10.385, suggesting the stock is oversold, but this could also indicate continued weakness. The forward P/E ratio is 10.101, which is relatively low, but given the recent earnings miss where the reported EPS was 0.36 against an estimate of 0.53, there are concerns about the company's ability to meet future expectations. The main risk is the company's declining revenue growth and the potential negative impact of the corruption case involving its subsidiary, which could further affect investor confidence.
BofA
—
2025-11-24
BofA
2025-11-24
Kursziel
—
New Street
$3500
2025-06-18
New Street
2025-06-18
Kursziel
$3500
B of A Securities
—
2023-09-20
B of A Securities
2023-09-20
Kursziel
—
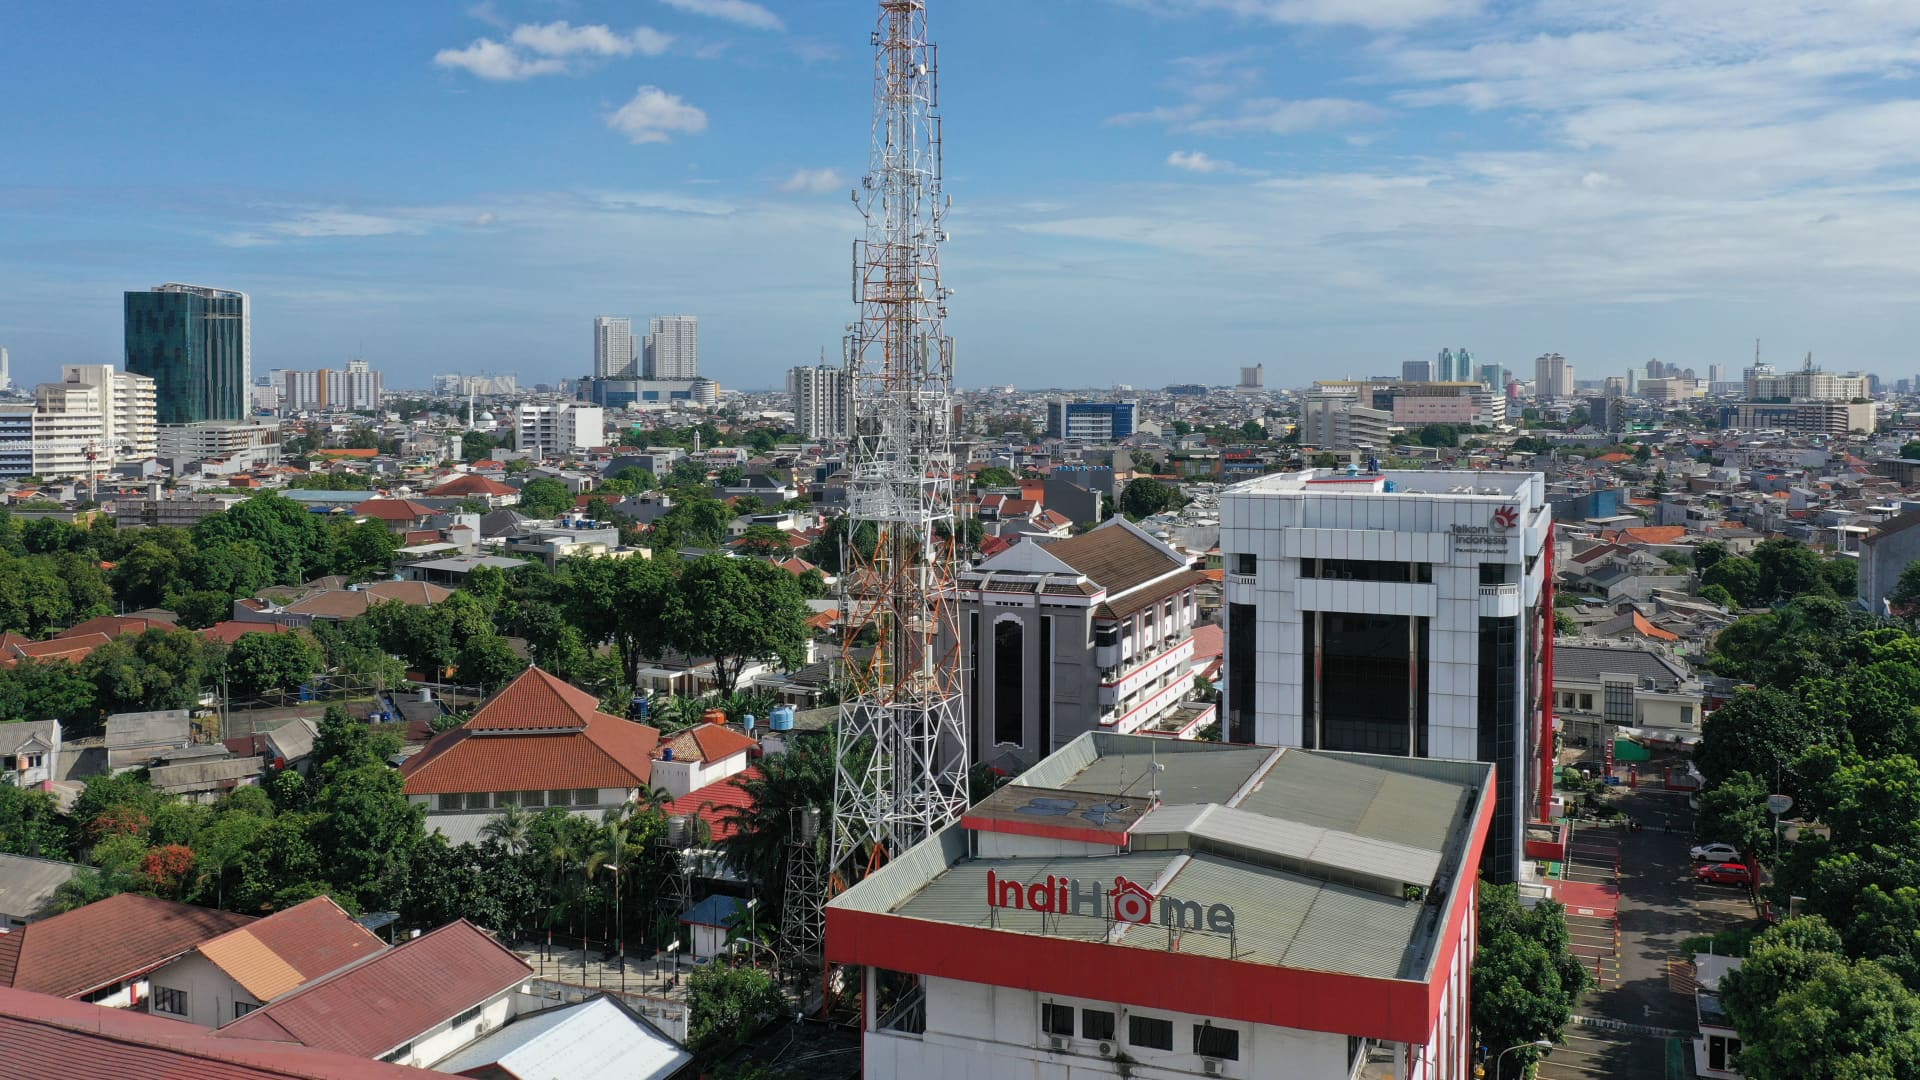
Indonesian Telecom Giant Weighs Sale of Venture Capital Firm
Asian Equities Rise as ADRs Track Higher in the US
Telekomunikasi Indonesia Q1 Financial Results

Telkom Indonesia Files 2025 Annual Report

Telkom Indonesia Files 2025 Annual Report
PT Telkom Indonesia (Persero) Tbk is an Indonesia-based telecommunication company. The Company is engaged in information and communication technology (ICT) services and telecommunications networks. Its segments include B2C, B2B Infra, B2B ICT, International, and Others. Its Business to Consumer (B2C) segment, comprises provision of telecommunications services to individual/residential customers, including mobile and fixed broadband services. Business-to-Business ICT (B2B ICT) provides system integration services, information technology services, and digital solutions to corporate and institutional customers. Its Business-to-Business Infrastructure (B2B Infra) offers management, and maintenance of telecommunications infrastructure, including telecommunications towers, fiber optic networks, backbone, data centers, and satellites. Its international Business segment provides international connectivity services and wholesale services to telecommunications operators and customers abroad. It operates in the Technology sector (TELEPHONE COMMUNICATIONS, EXCEPT RADIOTELEPHONE industry).
Telkom Indonesia (TLK) is not a good buy right now due to significant recent losses and negative growth indicators. The stock has dropped 47.68% year-to-date and 14.03% over the last five days, indicating a strong downward trend. Additionally, the RSI is at a very low 10.385, suggesting the stock is oversold, but this could also indicate continued weakness. The forward P/E ratio is 10.101, which is relatively low, but given the recent earnings miss where the reported EPS was 0.36 against an estimate of 0.53, there are concerns about the company's ability to meet future expectations. The main risk is the company's declining revenue growth and the potential negative impact of the corruption case involving its subsidiary, which could further affect investor confidence.
1 analysts cover TLK: 0 rate it Buy, 1 Hold and 0 Sell.
Noch keine Beiträge
Registriere dich oder melde dich an, um mitzudiskutierenDiese Seite dient nur der Recherche und ist keine Anlageberatung. Modelle können falsch liegen. Vergangene Wertentwicklung ist kein Indikator für die Zukunft.