A
Allen Holding Inc.
+ HältSPCX
+13.94%
3-Monats-Rendite
$147.960
+1.953 (+1.32%)Zum Schluss
Space Exploration Technologies Corp. designs, manufactures, launches, and operates products and services built on technologies, including rockets and spacecraft. The Company's segments include Space, Connectivity, and AI. Its Space segment designs, manufactures, and launches reusable rockets to provide access to space. Its Connectivity segment operates broadband data and communications network powered by approximately 10,200 Starlink broadband and mobile satellites in Low-Earth orbit, delivering connectivity to consumer, enterprises, and government customers over 167 countries, territories, and other markets. In its AI (artificial intelligence) segment, it operates a vertically integrated AI platform spanning its truth-seeking frontier model Grok, AI solutions for consumer and enterprise customers, X-its real-time information, entertainment, and free-speech platform and AI computational infrastructure.
Space Exploration Technologies Corp (SPCX) is currently trading at $146.03, which is significantly lower than the analyst price targets of $230 to $300. However, the stock has a low Relative Strength Index (RSI) of 27.46, indicating it may be oversold, but the recent performance shows a 5-day change of -10.17% and a year-to-date change of +569.56%. The main risk is the negative earnings trend with a forward P/E of 200 and a net income loss of $541 million in Q2 2026. While there are potential catalysts from upcoming earnings and analyst optimism, the current volatility and market sentiment suggest holding rather than buying.
SpaceX's Record IPO Faces Shareholder Lockup Expiry Pressure
SpaceX Earnings Preview: Stock Volatility Expectations
SpaceX Stock Surges 35%: Key Factors Behind the Recovery
Latest Wall Street Ratings Overview
AI Stocks Retreat in Asia and Europe; Elice IPO Plummets Over 30%
Space Exploration Technologies Corp. designs, manufactures, launches, and operates products and services built on technologies, including rockets and spacecraft. The Company's segments include Space, Connectivity, and AI. Its Space segment designs, manufactures, and launches reusable rockets to provide access to space. Its Connectivity segment operates broadband data and communications network powered by approximately 10,200 Starlink broadband and mobile satellites in Low-Earth orbit, delivering connectivity to consumer, enterprises, and government customers over 167 countries, territories, and other markets. In its AI (artificial intelligence) segment, it operates a vertically integrated AI platform spanning its truth-seeking frontier model Grok, AI solutions for consumer and enterprise customers, X-its real-time information, entertainment, and free-speech platform and AI computational infrastructure. It operates in the Technology sector.
Space Exploration Technologies Corp (SPCX) is currently trading at $146.03, which is significantly lower than the analyst price targets of $230 to $300. However, the stock has a low Relative Strength Index (RSI) of 27.46, indicating it may be oversold, but the recent performance shows a 5-day change of -10.17% and a year-to-date change of +569.56%. The main risk is the negative earnings trend with a forward P/E of 200 and a net income loss of $541 million in Q2 2026. While there are potential catalysts from upcoming earnings and analyst optimism, the current volatility and market sentiment suggest holding rather than buying.
SpaceX surges 830%! $SpaceX delivers better-than-expected quarterly results SpaceX's latest quarterly report significantly beat market expectations, marking a strong turnaround. After posting a $1.1 billion loss in the same period last year, the company recorded $4.4 billion in net profit this quarter; adjusted EBITDA reached $8.8 billion, up 306% year over year and far above Bloomberg's prior consensus estimate of $1.7 billion. The growth breakout came from the Super Intelligence SI segment, with quarterly revenue of nearly $7.6 billion, up 830% year over year, accounting for more than half of total revenue. With cloud business deployment, the completed Cursor acquisition, and Grok Bot product scaling, compute capacity expanded to 1.7 gigawatts. The growth momentum of this new business has already outpaced the traditional space business. Starlink, the long-standing core business, remained solid, with quarterly revenue of $5.2 billion, up 69% year over year, and global paying users exceeding 13.6 million, continuing to provide a stable base of revenue. In one sentence, the company's transformation: people used to see it only as a rocket and satellite internet space company, but it has now become a giant running dual mainlines of AI compute plus space infrastructure. After the results landed, SPCX rose nearly 10% in a single day. I mentioned two days earlier that SPCX earnings were about to be released, and I wonder if any friends noticed. The space business was once SpaceX's signature claim to fame, but AI compute is its core growth engine for the future. Of course, in the overseas AI race, OpenAI, Claude, and Gemini still dominate, and how much market share SpaceX can ultimately capture will require continued observation. Based on this current report, its growth momentum is indeed very strong. #StockEarningsSeason #SwitzerlandApprovesFirstBitcoinETF
Mehr anzeigen
Explosive! Domestic chipmaker overtakes Samsung, major players slam in 7 million U, bulls and bears in a fierce battle! News is the gunpowder, the K-line is the barrel, and capital flow is the hand that pulls the trigger. $SAMSUNG rebounds to 168, and the 170 level overhead is heavy resistance! Yangtze Memory's market share hits 38.5% to overtake Samsung; Samsung is scrambling to upgrade its Xi'an plant but is being constrained by the US. Trade ideas: Long: buy on a pullback near 160-162. Short: short on a rebound near 170-172. The market humbles everyone who thinks they can't be wrong! $MU $SPCX #GateLatestReserveRatioReaches118.49% #TeslaQ3Earnings
Mehr anzeigen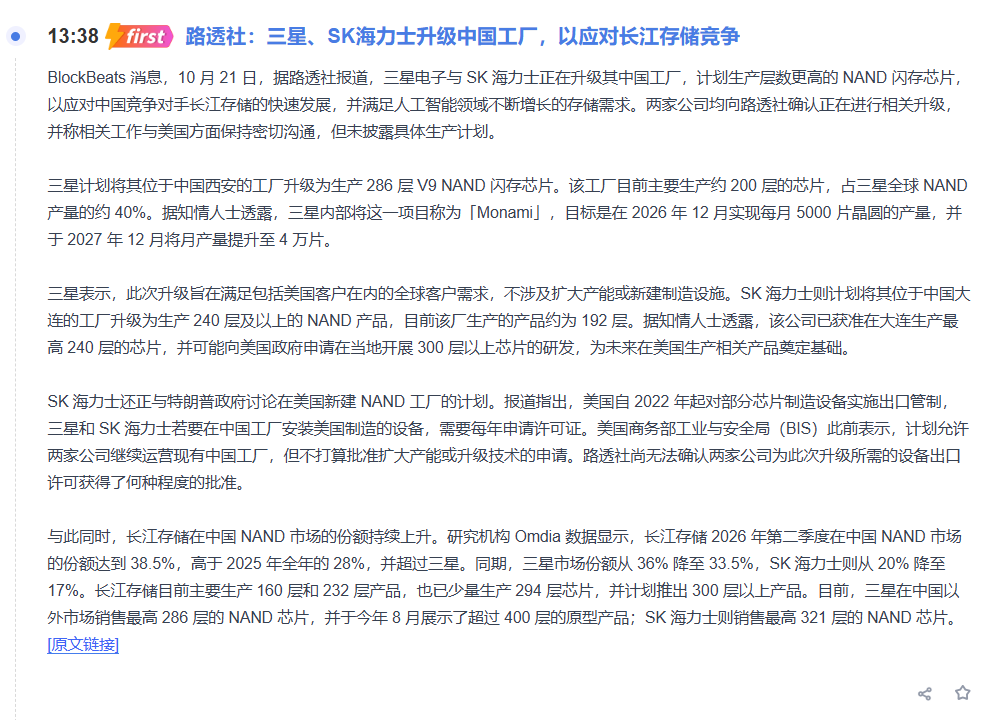
$SPCX earnings are out, and results are beating market expectations across the board — is the rocket about to take off??? This earnings report isn't just a slight beat — it's a full-scale blowout! Revenue, profit, and earnings quality all came in well above market expectations, showing that the market fundamentals have undergone a qualitative shift. The profit logic has now been delivered, and the loss pressure the market had been worried about has been removed. The business is improving and attracting a lot of capital attention. Although this rally was driven by the earnings report, the report was released after the US market close, so there's a high probability of another push at tonight's open. So Nan Ge chose to open a long position at the current price of 161.38, with a stop loss at 157.5 and a target of 164. #EarningsSeason #ZcashUp8.5in24Hours #NEARVoteProposesCuttingAnnualInflationTo1.6%
Mehr anzeigen
Musk made a big move! SPCX is surging, don't rush to chase it—the main players have a much bigger game going on! A screen full of good news is often bait. Candlesticks can be faked, but real money in positions doesn't lie. On the one-hour chart, SPCX got a double boost from the merger and earnings and shot up over 7% in one go. Don't be fooled by the $440 million that poured in within an hour—there's danger hidden underneath. Right now the long-to-short ratio across the market is as high as 4.3 to 1, with retail all chasing the rally, but look at the whale data: smart money is quietly opening 20x short positions. My view: the main players just finished liquidating the shorts, and next they'll likely turn around and hunt the longs. I suggest not stubbornly chasing the high! Strategy-wise, short into strength—wait for a bounce to the 163-165 area for a light short attempt, and if it falls back to 154-157 and stabilizes, then consider a short-term long. Where exactly are those 10x leverage whales with millions in unrealized profit lying in wait? Like and follow, and next time I'll take you to copy the whales' bottom! $SPCX $TSLA $DOGE #TeslaQ3Earnings
Mehr anzeigen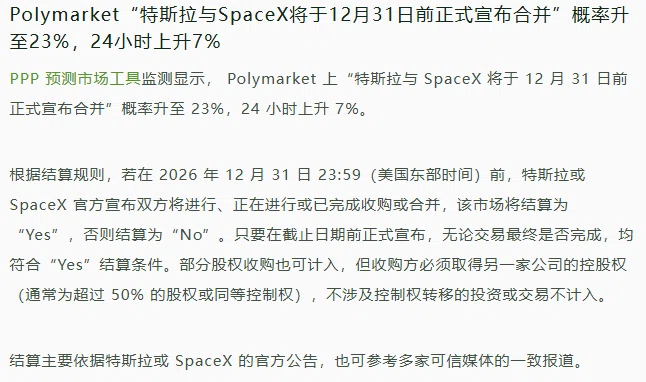
SpaceX earnings call interpretation (1) After the SPCX Q3 report, Musk and several executives said quite a bit on the call. Here I'll focus on the key points. Starship and Starlink are both fine and can provide solid cash flow. Let's consider AI and compute leasing together. SPCX's AI revenue is also based on existing compute, so let's just calculate efficiency on a consistent basis. Base price set at $50 billion/GW. Compared with Q2, the Q3 SI revenue increment was $5 billion, and high-speed growth is expected to continue in Q4. What I care about most is capex. Q4 plans call for $35-40 billion in spending, adding roughly 1GW of compute. The logic: by the end of October it will reach 2.2GW, up 0.5GW from the end of Q3, and the probability of reaching 2.7GW by the end of December is fairly high. From this we can infer that SPCX's capex to add 1GW of compute is just under $40 billion. Then extrapolating, the capex needed for 10GW of compute in 2027 could be between $350-400 billion. Averaged monthly, that is $29.17-33.33 billion, while the Q1 2027 revenue guidance given on the call is $33-37 billion, or about $11-12.3 billion per month on average. The gap will continuously draw down SPCX free cash flow. So the $40 billion borrowing plan implemented in Q4 will be a key step in executing compute buildout.
Mehr anzeigen
Diese Seite dient nur der Recherche und ist keine Anlageberatung. Modelle können falsch liegen. Vergangene Wertentwicklung ist kein Indikator für die Zukunft.