$16.380
+0.369 (+2.25%)Zum Schluss
- Hoch
- 16.920
- Eröffnung
- 16.080
- Volumengewichteter Durchschnittskurs
- 16.43
- Volumen
- 558.50K
- Marktkap.
- —
- Tief
- 16.000
- Umsatz
- 9.18M
- EV/EBITDA, TTM
- -23.04
Once Upon a Farm, PBC is engaged in the manufacturing, distribution, marketing and related sale of nutrient-packed, delicious food for babies and kids of on-the-go parents under the brand name, Once Upon a Farm. Its products as offered for Babies, Kids and Toddlers. Its products includemelts, fruit and veggie puffs, frozen meals, refrigerated oat bar, refrigerated pouches and variety packs. Its variety packs include Carter’s Baby & Toddler Favorites, Carter’s Big Kid Favorites, Carter’s Baby & Toddler Snack Sampler, 9ct, Farmer's Finest, Winter Favorites, Refrigerated Bar Sampler, Green Checkered Pouch Cooler 2-Pack, Dairy-Free Smoothie, Fruit & Veggie Puff, Refrigerated Protein Bar, Baby Best Sellers and others. Its meals include Organic Pasta Meals Cauli-fredo & Spinach, Organic Pasta Meals Pomodoro, Veggie Pot Pie, Papaya Sunrise, Banana Berry Acai and others. Its Refrigerated Oat Bars include Apple Cinnamon Oat Bar, Banana Chocolate Oat Bar, Blueberry Oat Bar and others.
KI-Analyse of Once Upon A Farm PBC (OFRM)
KaufenOnce Upon a Farm (OFRM) is a good buy right now due to its recent positive developments and growth potential. The current price is $17.36, and analysts have set a target price of $24.50, indicating a potential upside of approximately 46%. Additionally, the company has gained WIC eligibility in California, which could significantly expand its market reach and sales. However, the main risk is the negative net income trend, with a reported loss of $15.8 million in Q1 2026, which investors should monitor closely.
Bewertungskennzahlen
Event-Zeitleiste
News
 5.010-05PRnewswire
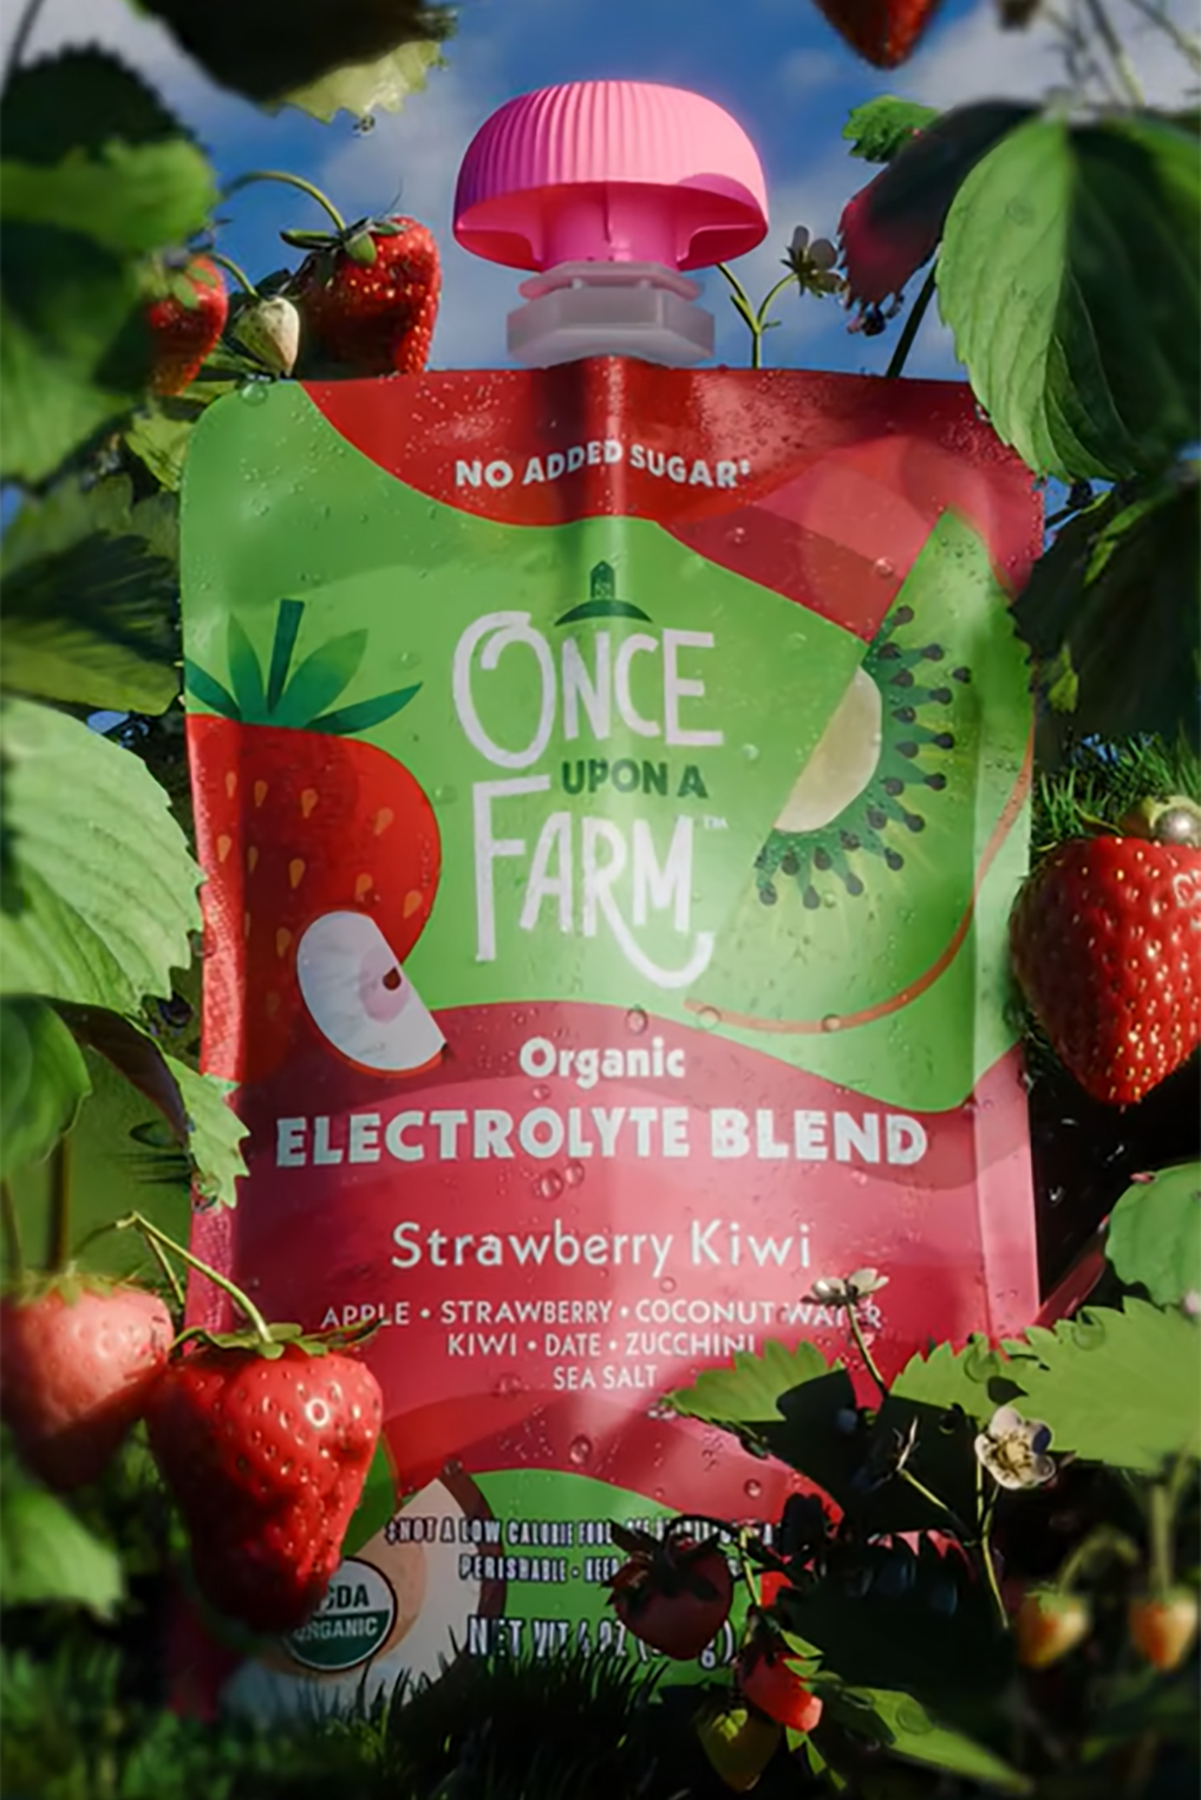
Once Upon a Farm Launches New Electrolyte Blends for Kids
 5.010-05PRnewswire
Once Upon a Farm Launches Electrolyte Blends for Kids
 5.010-05Newsfilter
Once Upon a Farm Launches Electrolyte Blends for Kids
- 8.506-08Newsfilter
Once Upon a Farm Releases 2025 Impact Report Highlighting Nutrition Initiatives
 6.505-28seekingalpha
Baron Small Cap Fund Underperforms in Q1 2026
OFRM FAQ – beantwortet von Alphio AI
Once Upon a Farm, PBC is engaged in the manufacturing, distribution, marketing and related sale of nutrient-packed, delicious food for babies and kids of on-the-go parents under the brand name, Once Upon a Farm. Its products as offered for Babies, Kids and Toddlers. Its products includemelts, fruit and veggie puffs, frozen meals, refrigerated oat bar, refrigerated pouches and variety packs. Its variety packs include Carter’s Baby & Toddler Favorites, Carter’s Big Kid Favorites, Carter’s Baby & Toddler Snack Sampler, 9ct, Farmer's Finest, Winter Favorites, Refrigerated Bar Sampler, Green Checkered Pouch Cooler 2-Pack, Dairy-Free Smoothie, Fruit & Veggie Puff, Refrigerated Protein Bar, Baby Best Sellers and others. Its meals include Organic Pasta Meals Cauli-fredo & Spinach, Organic Pasta Meals Pomodoro, Veggie Pot Pie, Papaya Sunrise, Banana Berry Acai and others. Its Refrigerated Oat Bars include Apple Cinnamon Oat Bar, Banana Chocolate Oat Bar, Blueberry Oat Bar and others. It operates in the Consumer Non-Cyclicals sector.
Once Upon a Farm (OFRM) is a good buy right now due to its recent positive developments and growth potential. The current price is $17.36, and analysts have set a target price of $24.50, indicating a potential upside of approximately 46%. Additionally, the company has gained WIC eligibility in California, which could significantly expand its market reach and sales. However, the main risk is the negative net income trend, with a reported loss of $15.8 million in Q1 2026, which investors should monitor closely.
Community
Mehr ↗Noch keine Beiträge
Registriere dich oder melde dich an, um mitzudiskutierenDiese Seite dient nur der Recherche und ist keine Anlageberatung. Modelle können falsch liegen. Vergangene Wertentwicklung ist kein Indikator für die Zukunft.