
樂
樂觀
樂觀 · 25%TPL
$1,531.28
情境價格
$350.920
+4.457 (+1.27%)收盤時
Texas Pacific Land Corporation is the landowner in the State of Texas with approximately 882,000 surface acres of land, principally concentrated in the Permian Basin. Its segments include Land and Resource Management and Water Services and Operations. The Land and Resource Management segment focuses on managing Company’s oil and gas royalty interest and surface acres located in 19 different countries. The Land and Resource Management segment encompasses the business of managing its approximately 882,000 surface acres of land and its approximately 207,000 NRA of oil and gas royalty interests, principally concentrated in the Permian Basin. This segment consists of royalties from oil and gas, revenues from easements, commercial leases and renewables, and land and material sales. The Water Services and Operations segment encompasses the business of providing a full-service water offering to operators in the Permian Basin. Its services include water sourcing and produced water disposal.
Texas Pacific Land Corp is a good buy right now, with a current price of 350.92 and a forward P/E of 37.74, suggesting reasonable valuation relative to future earnings. The company has shown strong revenue growth, with Q2 2026 revenue at 246.06 million USD, marking a significant increase from previous quarters. However, the RSI is at 47.30, indicating it is not yet overbought, which could present an entry opportunity. The main risk is the recent 5-day change of -2.79%, indicating potential short-term volatility.
情境價格取自當年最後一個月度預測區間。機率為固定的模型權重(25 / 50 / 25),不構成保證。
Investor Sentiments on Various Stocks
Oil Prices Surge After Attacks on Saudi Energy Facilities
Murray Stahl's Q2 2026 Investment Moves
Can Market Momentum Be Sustained?
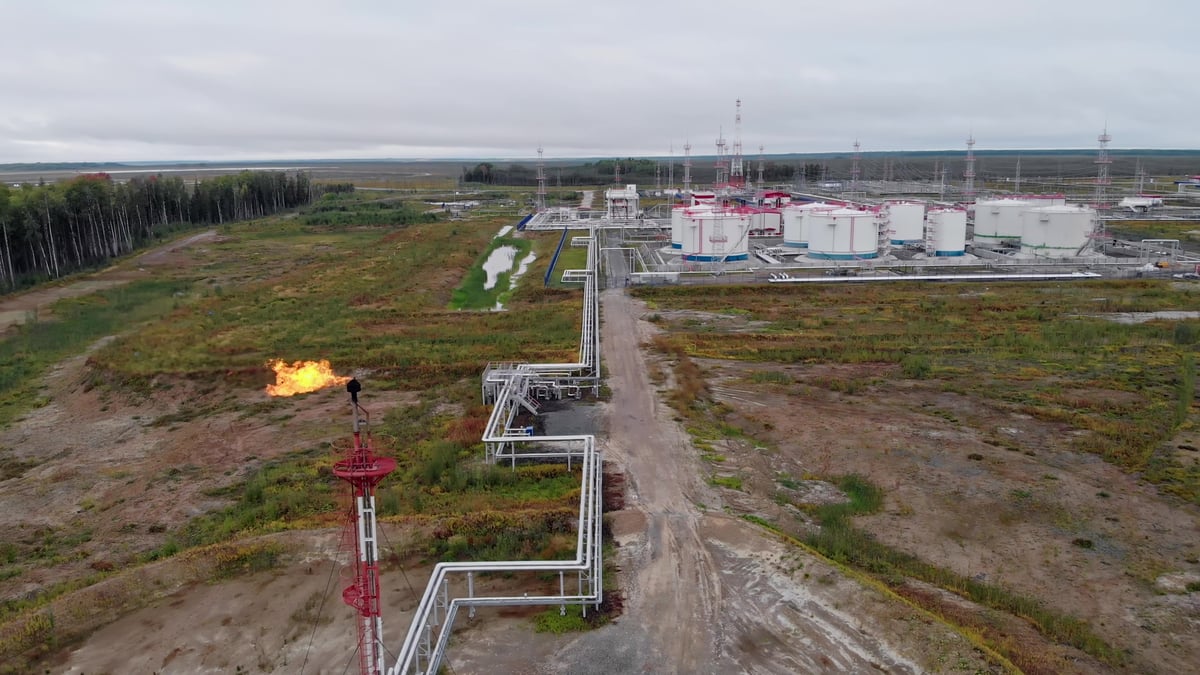
Texas Pacific Land Corporation Shares Surge 52.4% Amid Oil and AI Boom
Texas Pacific Land Corporation is the landowner in the State of Texas with approximately 882,000 surface acres of land, principally concentrated in the Permian Basin. Its segments include Land and Resource Management and Water Services and Operations. The Land and Resource Management segment focuses on managing Company’s oil and gas royalty interest and surface acres located in 19 different countries. The Land and Resource Management segment encompasses the business of managing its approximately 882,000 surface acres of land and its approximately 207,000 NRA of oil and gas royalty interests, principally concentrated in the Permian Basin. This segment consists of royalties from oil and gas, revenues from easements, commercial leases and renewables, and land and material sales. The Water Services and Operations segment encompasses the business of providing a full-service water offering to operators in the Permian Basin. Its services include water sourcing and produced water disposal. It operates in the Energy sector (OIL ROYALTY TRADERS industry).
Texas Pacific Land Corp is a good buy right now, with a current price of 350.92 and a forward P/E of 37.74, suggesting reasonable valuation relative to future earnings. The company has shown strong revenue growth, with Q2 2026 revenue at 246.06 million USD, marking a significant increase from previous quarters. However, the RSI is at 47.30, indicating it is not yet overbought, which could present an entry opportunity. The main risk is the recent 5-day change of -2.79%, indicating potential short-term volatility.
暫無貼文
註冊或登入後參與討論本頁僅供研究參考,不構成投資建議。模型可能出錯。過往表現不代表未來結果。