
樂
樂觀
樂觀 · 25%RHP
$125.72
情境價格
$130.380
-0.874 (-0.67%)收盤時
Ryman Hospitality Properties, Inc. is a lodging and hospitality real estate investment trust that specializes in upscale convention center resorts and entertainment experiences. Its holdings include Gaylord Opryland Resort & Convention Center; Gaylord Palms Resort & Convention Center; Gaylord Texan Resort & Convention Center; Gaylord National Resort & Convention Center, and Gaylord Rockies Resort & Convention Center, which are non-gaming convention center hotels in the United States based on total indoor meeting space. Its segments include Hospitality, which includes its Gaylord Hotels properties, its JW Marriott properties, the Inn at Opryland and the AC Hotel; Entertainment, which includes the entertainment and media assets comprising OEG; and Corporate and Other. It owns the Grande Lakes Orlando Resort, the JW Marriott Phoenix Desert Ridge Resort & Spa and the JW Marriott San Antonio Hill Country Resort & Spa.
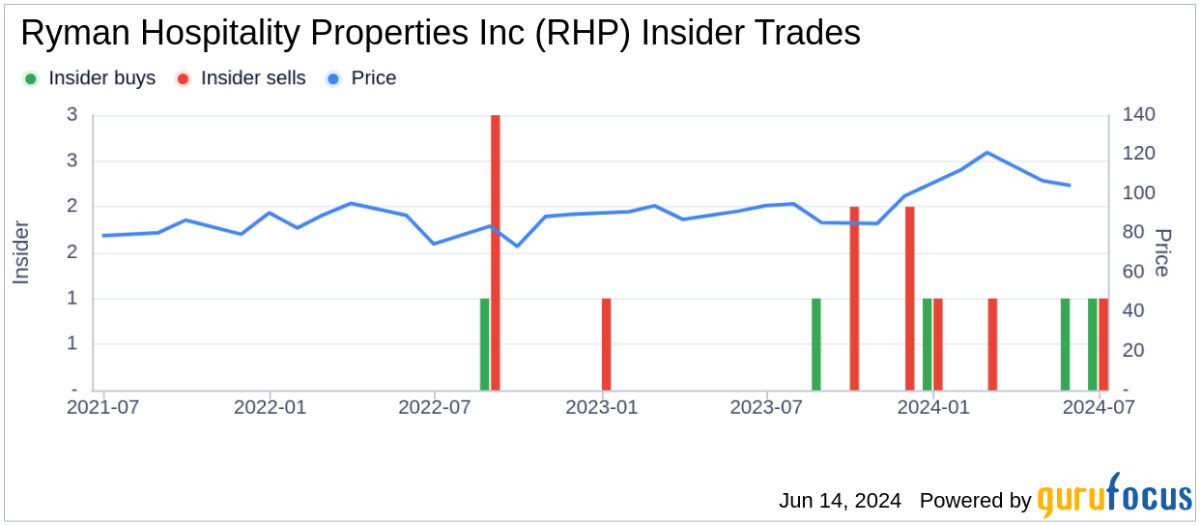
Ryman Hospitality Properties Inc is a good buy right now due to its strong recent performance, with a year-to-date change of +31.94% and a solid gross margin of 24.86% in Q2 2026. Additionally, the forward P/E ratio of 25.84 suggests reasonable valuation compared to its growth prospects. The main risk is its high debt-to-equity ratio of 501.76%, which could impact financial stability if not managed carefully.
Raymond James
$130
2026-09-28
Raymond James
2026-09-28
目標價
$130
Truist
$141
2026-09-10
Truist
2026-09-10
目標價
$141
Citi
$135
2026-09-09
Citi
2026-09-09
目標價
$135
Barclays
$147
2026-08-27
Barclays
2026-08-27
目標價
$147
BofA
$145
2026-08-25
BofA
2026-08-25
目標價
$145
情境價格取自當年最後一個月度預測區間。機率為固定的模型權重(25 / 50 / 25),不構成保證。
Ryman Acquires Grande Lakes Orlando Resort for $1.38 Billion
Ryman Acquires Grande Lakes Orlando Resort for $1.38 Billion
Ryman Hospitality to Release Q3 2026 Earnings Results on November 2
Ryman Hospitality Completes $700 Million Senior Notes Offering
RHP Q2 2026 Earnings Call Transcript
Ryman Hospitality Properties, Inc. is a lodging and hospitality real estate investment trust that specializes in upscale convention center resorts and entertainment experiences. Its holdings include Gaylord Opryland Resort & Convention Center; Gaylord Palms Resort & Convention Center; Gaylord Texan Resort & Convention Center; Gaylord National Resort & Convention Center, and Gaylord Rockies Resort & Convention Center, which are non-gaming convention center hotels in the United States based on total indoor meeting space. Its segments include Hospitality, which includes its Gaylord Hotels properties, its JW Marriott properties, the Inn at Opryland and the AC Hotel; Entertainment, which includes the entertainment and media assets comprising OEG; and Corporate and Other. It owns the Grande Lakes Orlando Resort, the JW Marriott Phoenix Desert Ridge Resort & Spa and the JW Marriott San Antonio Hill Country Resort & Spa. It operates in the Real Estate sector (REAL ESTATE INVESTMENT TRUSTS industry).
Ryman Hospitality Properties Inc is a good buy right now due to its strong recent performance, with a year-to-date change of +31.94% and a solid gross margin of 24.86% in Q2 2026. Additionally, the forward P/E ratio of 25.84 suggests reasonable valuation compared to its growth prospects. The main risk is its high debt-to-equity ratio of 501.76%, which could impact financial stability if not managed carefully.
8 analysts cover RHP: 1 rate it Buy, 6 Hold and 1 Sell. The average price target is 108.71.
暫無貼文
註冊或登入後參與討論本頁僅供研究參考,不構成投資建議。模型可能出錯。過往表現不代表未來結果。