
樂
樂觀
樂觀 · 25%LEGH
$32.49
情境價格
$27.390
+0.151 (+0.55%)收盤時
Legacy Housing Corporation builds, sells, and finances manufactured homes and tiny houses that are distributed through a network of independent retailers and Company-owned stores and also sold directly to manufactured home communities. The Company has operations focused primarily on the southern United States. Its homes are marketed under its premier Legacy brand name and are sold to consumers, primarily across 15 states, through a network of over 80 independent retail locations, 14 Company-owned retail locations and through direct sales to owners of manufactured home communities. Its 14 Company-owned retail locations, including 13 Heritage Housing stores and one Tiny House Outlet store, exclusively sell its homes. It provides inventory financing for its independent retailers who purchase homes and then sell them to consumers. It provides consumer financing for its products, which are sold to end users through both independent and Company-owned retail locations.
Legacy Housing Corp (LEGH) is a good buy right now due to its strong financial performance and growth potential. The current price is $27.39, which is below the analyst price target of $24, indicating potential upside. The company reported a 32% year-over-year revenue increase to $66.3 million in Q2 2026, with net income soaring nearly 59% to $23.5 million, leading to an EPS of $0.99, a 62% increase from last year. However, the RSI is at 39.739, indicating the stock is approaching oversold territory, which could present a buying opportunity. The main risk is the recent 1.51% decline over the past 5 days, which reflects broader market trends and could affect short-term performance.
情境價格取自當年最後一個月度預測區間。機率為固定的模型權重(25 / 50 / 25),不構成保證。

BOXABL Signs Agreement for Up to 1,500 Factory-Built Homes with LC Vegas
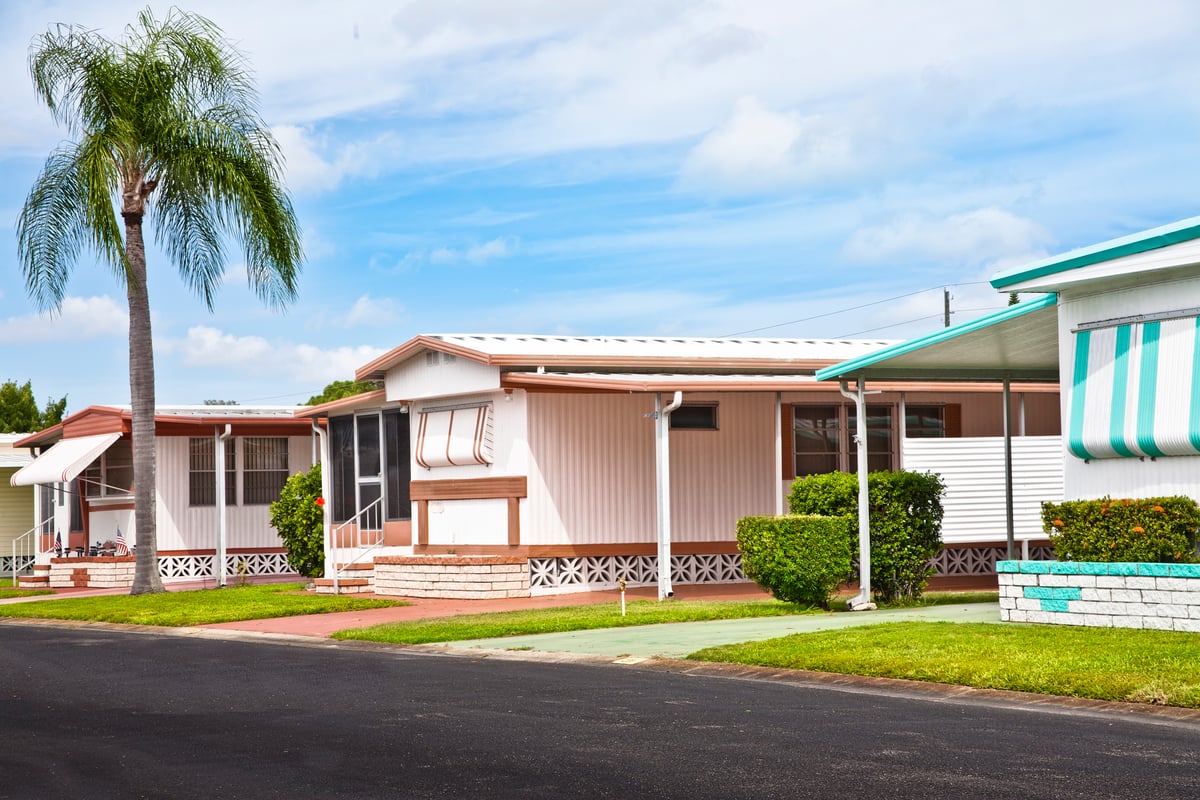
Housing Market Struggles, Legacy Housing Sees Significant Growth
Factory-Built Homes Gain New Advantages
Legacy Housing (LEGH) Q2 2026 Earnings Call Transcript
Legacy Housing Q2 Earnings Beat Expectations
Legacy Housing Corporation builds, sells, and finances manufactured homes and tiny houses that are distributed through a network of independent retailers and Company-owned stores and also sold directly to manufactured home communities. The Company has operations focused primarily on the southern United States. Its homes are marketed under its premier Legacy brand name and are sold to consumers, primarily across 15 states, through a network of over 80 independent retail locations, 14 Company-owned retail locations and through direct sales to owners of manufactured home communities. Its 14 Company-owned retail locations, including 13 Heritage Housing stores and one Tiny House Outlet store, exclusively sell its homes. It provides inventory financing for its independent retailers who purchase homes and then sell them to consumers. It provides consumer financing for its products, which are sold to end users through both independent and Company-owned retail locations. It operates in the Consumer Cyclicals sector (MOBILE HOMES industry).
Legacy Housing Corp (LEGH) is a good buy right now due to its strong financial performance and growth potential. The current price is $27.39, which is below the analyst price target of $24, indicating potential upside. The company reported a 32% year-over-year revenue increase to $66.3 million in Q2 2026, with net income soaring nearly 59% to $23.5 million, leading to an EPS of $0.99, a 62% increase from last year. However, the RSI is at 39.739, indicating the stock is approaching oversold territory, which could present a buying opportunity. The main risk is the recent 1.51% decline over the past 5 days, which reflects broader market trends and could affect short-term performance.
暫無貼文
註冊或登入後參與討論本頁僅供研究參考,不構成投資建議。模型可能出錯。過往表現不代表未來結果。