
樂
樂觀
樂觀 · 25%KR
$76.57
情境價格
$66.770
-1.082 (-1.62%)收盤時
The Kroger Co. is a food and drug retailer. The Company operates supermarkets, multi-department stores and fulfillment centers throughout the United States. It operates approximately 2,697 supermarkets, 2,250 pharmacies and 1,731 fuel centers in over 35 states and the District of Columbia while also operating online through a digital ecosystem to offer customers an omnichannel shopping experience. The Company also manufactures and processes food for sale in its supermarkets and online. It offers Pickup and Harris Teeter ExpressLane personalized, order online, pick-up at the store services at approximately 2,408 of its supermarkets and provides delivery, which allows it to offer digital solutions to its customers. Its delivery solutions include orders delivered to customers at retail store locations, customer fulfillment centers and orders placed through third-party platforms. The Company also offers customer-facing apps and interfaces.
Kroger Co is a good buy right now, with a current price of $66.77 and a forward P/E ratio of 11.325, suggesting it is undervalued compared to its earnings potential. The recent positive news about Kroger's growth targets, including a projected 3% comparable sales growth by 2029 and adjusted EPS growth of 7%-11%, reinforces this bullish outlook. However, the company is facing some risks, particularly the recent layoff plan affecting 3,000 positions, which could impact morale and operational efficiency in the short term.
BNP Paribas
$72
2026-10-07
BNP Paribas
2026-10-07
目標價
$72
Melius Research
$80
2026-09-29
Melius Research
2026-09-29
目標價
$80
Guggenheim
$66
2026-09-15
Guggenheim
2026-09-15
目標價
$66
Telsey Advisory
$75
2026-09-14
Telsey Advisory
2026-09-14
目標價
$75
Roth Capital
$73
2026-09-14
Roth Capital
2026-09-14
目標價
$73
情境價格取自當年最後一個月度預測區間。機率為固定的模型權重(25 / 50 / 25),不構成保證。
Musk Advocates for Tesla-SpaceX Merger
Kroger Co. Unveils 2026 Investor Update with Growth Targets
Kroger Expects to Sell 25 Million Pounds of Halloween Candy
Albertsons Sales Growth Falls Short of Expectations
Kroger to Cut One-Third of Corporate Staff to Enhance Efficiency
The Kroger Co. is a food and drug retailer. The Company operates supermarkets, multi-department stores and fulfillment centers throughout the United States. It operates approximately 2,697 supermarkets, 2,250 pharmacies and 1,731 fuel centers in over 35 states and the District of Columbia while also operating online through a digital ecosystem to offer customers an omnichannel shopping experience. The Company also manufactures and processes food for sale in its supermarkets and online. It offers Pickup and Harris Teeter ExpressLane personalized, order online, pick-up at the store services at approximately 2,408 of its supermarkets and provides delivery, which allows it to offer digital solutions to its customers. Its delivery solutions include orders delivered to customers at retail store locations, customer fulfillment centers and orders placed through third-party platforms. The Company also offers customer-facing apps and interfaces. It operates in the Consumer Non-Cyclicals sector (RETAIL-GROCERY STORES industry).
Kroger Co is a good buy right now, with a current price of $66.77 and a forward P/E ratio of 11.325, suggesting it is undervalued compared to its earnings potential. The recent positive news about Kroger's growth targets, including a projected 3% comparable sales growth by 2029 and adjusted EPS growth of 7%-11%, reinforces this bullish outlook. However, the company is facing some risks, particularly the recent layoff plan affecting 3,000 positions, which could impact morale and operational efficiency in the short term.
25 analysts cover KR: 9 rate it Buy, 14 Hold and 2 Sell. The average price target is 75.00.
$KR | THE KROGER CO. Q2 2026 EARNINGS HIGHLIGHTS ◆ EPS: $1.09 vs. $1.06 est. ✅ ◆ Revenue: $34.62B vs. $34.64B est. ❌ ◆ Net Income: $641M (+5.3% YoY) ◆ Operating Income: $971M (+12.5% YoY) ◆ Operating Expenses: $33,650M (+2.4% YoY) ◆ H1 Operating Cash Flow: $3,085M (-16.4% YoY) Key Metrics: ◆ Adjusted eCommerce sales grew +20% YoY; Kroger Precision Marketing profit grew +24% in Q2 2026. ◆ Kroger repurchased $1.0B in shares during Q2 2026; ~$800M remains of the $2B authorization, expected completed by FY26 end. ◆ Dividend increased 11% this quarter, marking 20 consecutive years of dividend increases; $0.39 declared per share. Forward Guidance: ◆ FY26 identical sales without fuel: +0.2% to +0.8% (lowered from +1.0% to +2.0%); includes ~140 bps IRA headwind. ◆ FY26 adjusted FIFO Operating Profit: $5.0B to $5.2B (reaffirmed). ◆ FY26 adjusted EPS: $5.10 to $5.30 (reaffirmed). ◆ FY26 Free Cash Flow: $2.7B to $2.9B (reaffirmed).
展開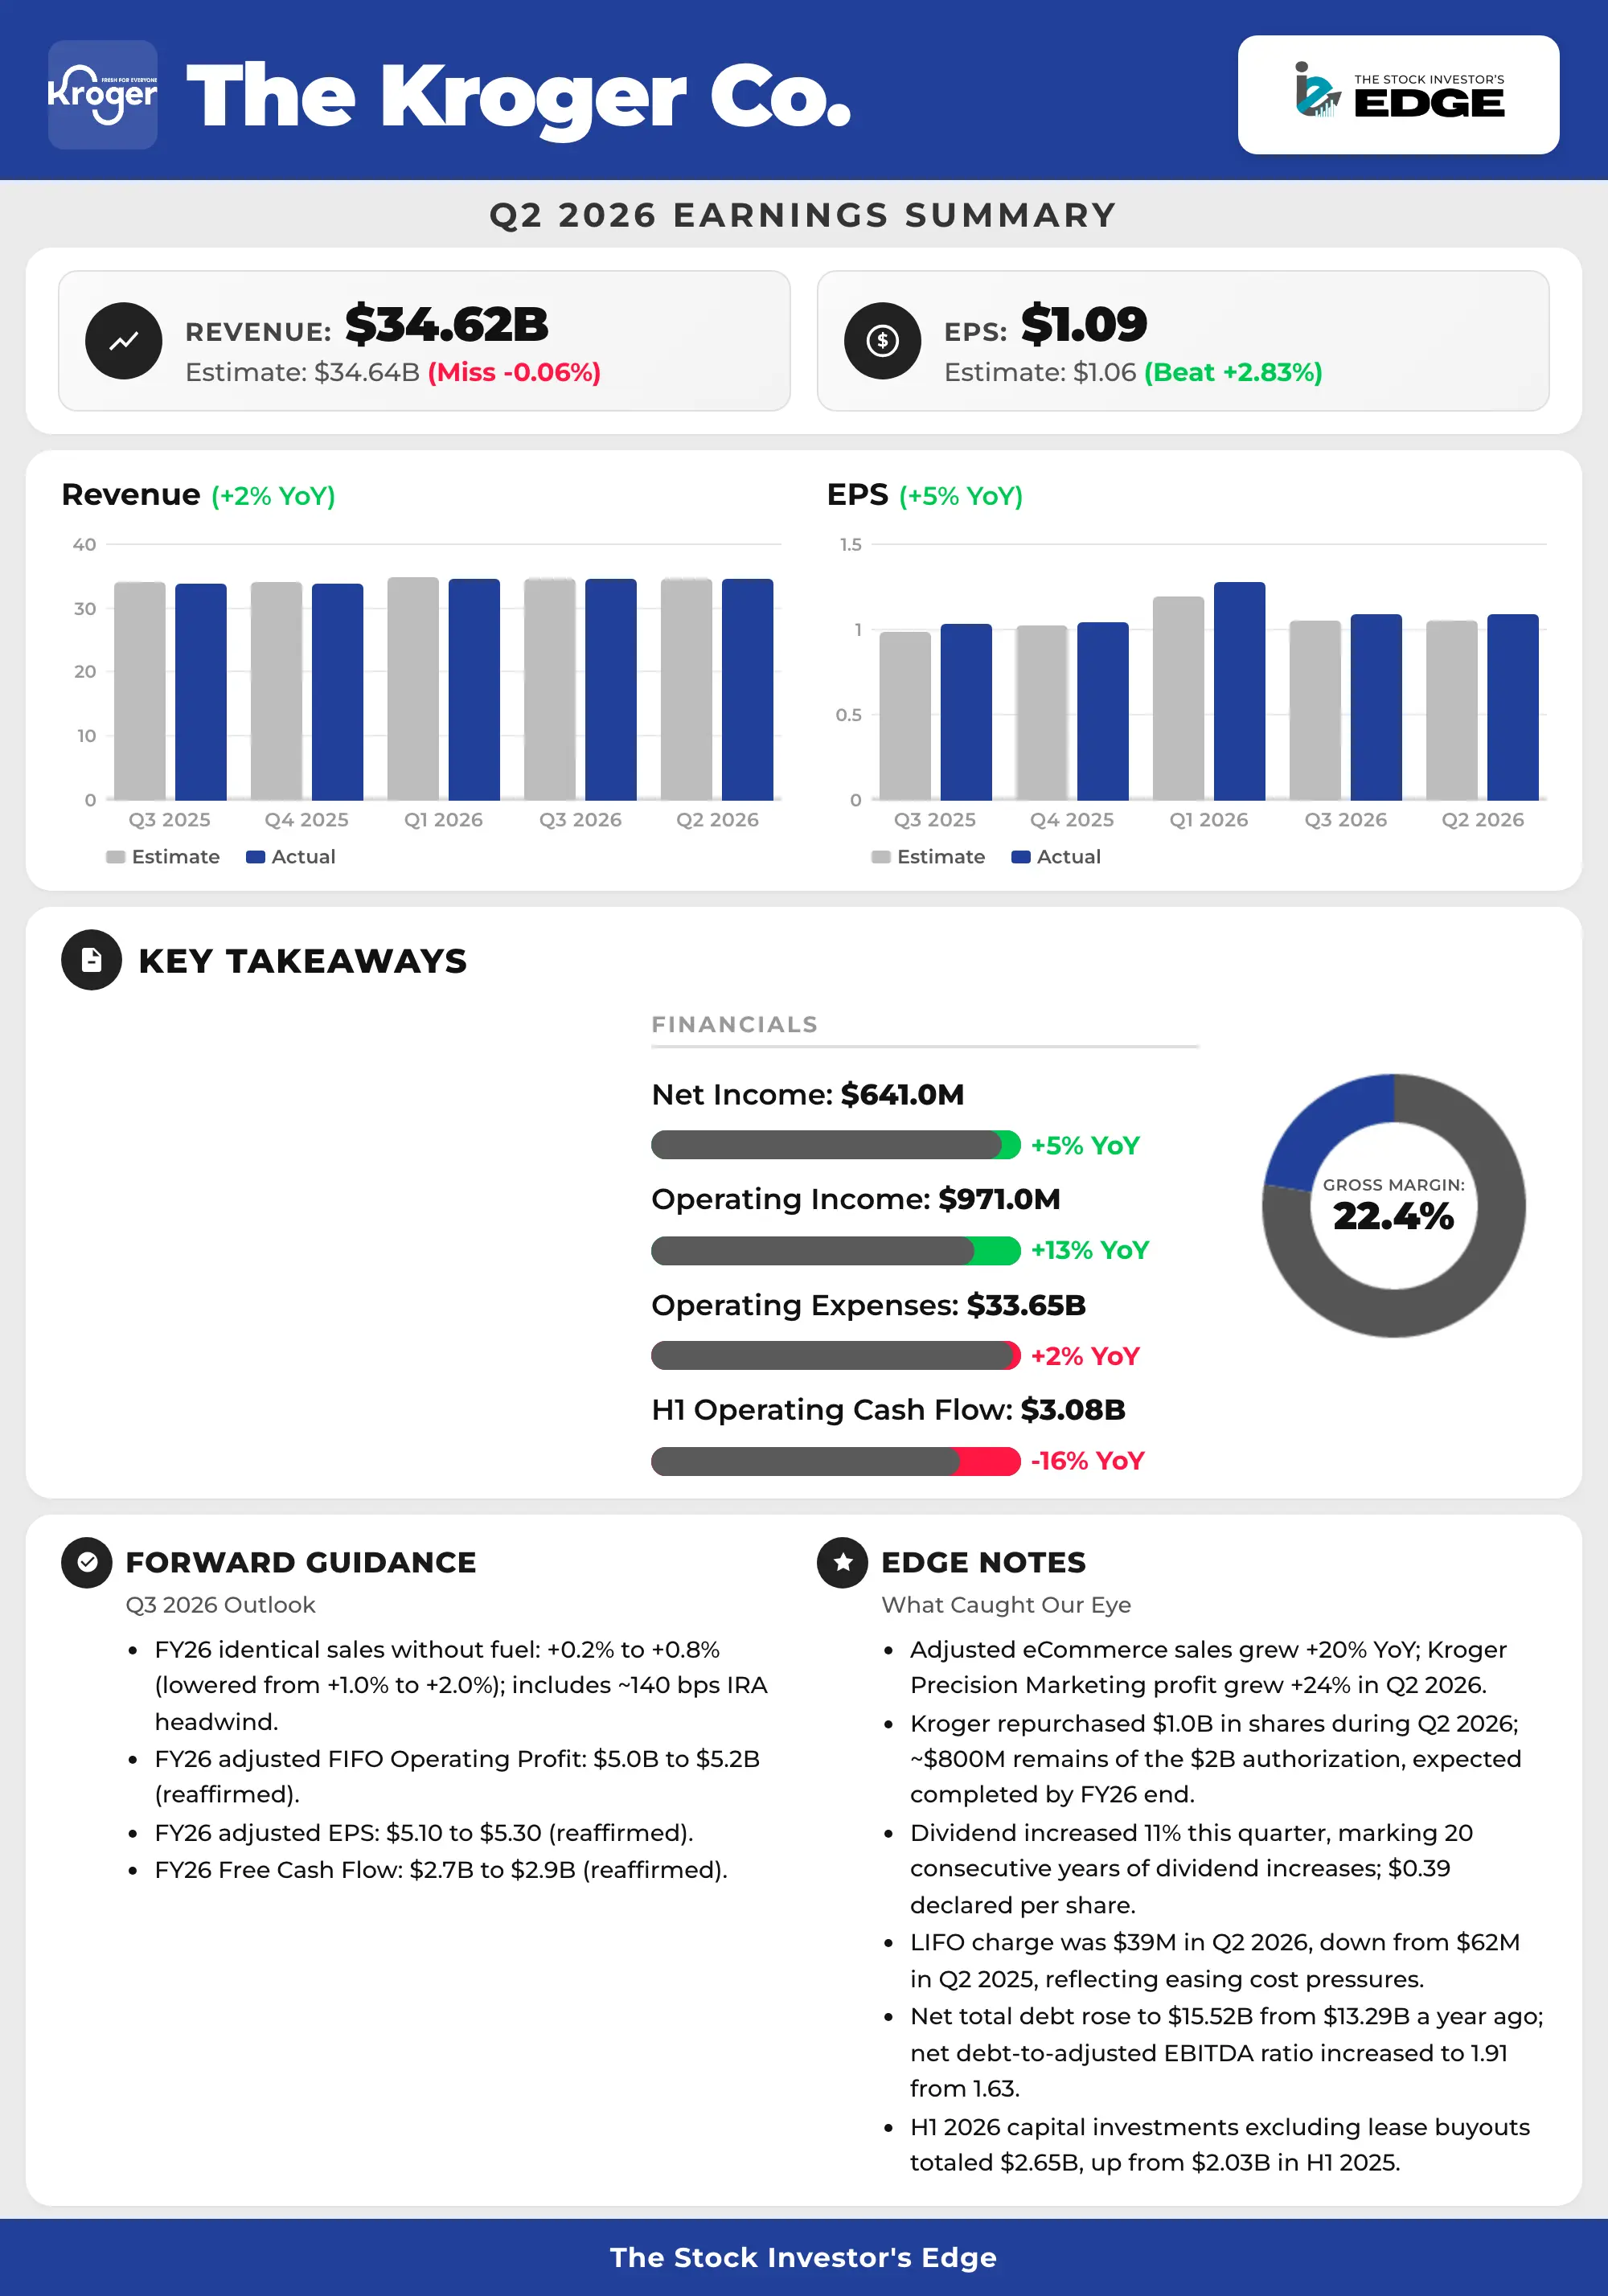
$KR | Kroger Q2 2026 Earnings - Adj EPS $1.09 (est $1.05) - Sales $34.6B (est $34.69B) - Identical-Store Sales Ex-Fuel +0.2% (est +0.88%) - Still Sees FY Adj EPS $5.10 To $5.30 (est $5.22) - Still Sees FY CAPEX $3.8B To $4.03 (est $3.95B)
展開本頁僅供研究參考,不構成投資建議。模型可能出錯。過往表現不代表未來結果。