
樂
樂觀
樂觀 · 25%JPM
$268.14
情境價格
$331.580
-4.874 (-1.47%)收盤時
JPMorgan Chase & Co. is a financial holding company engaged in investment banking, financial services for consumers and small businesses, commercial banking, financial transaction processing and asset management. It operates through three segments: Consumer & Community Banking (CCB), Commercial & Investment Bank (CIB), and Asset & Wealth Management (AWM). Its CCB segment offers products and services to consumers and small businesses through bank branches, ATMs, digital and telephone banking. Its CIB segment consists of banking and payments and markets and securities services, and offers a suite of investment banking, lending, payments, market-making, financing, custody and securities products and services to a global base of corporate and institutional clients. Its AWM segment offers investment and wealth management solutions. It offers multi-asset investment management solutions, retirement products and services, brokerage, custody, estate planning, lending, deposits, and others.
JPMorgan Chase is currently a hold due to its recent price decline and mixed analyst ratings. The stock is trading at $331.58, with an RSI of 38.33, indicating it is nearing oversold territory, but the forward P/E ratio of 13.50 suggests it is not undervalued compared to its peers. The main risk is the recent insider selling trend, which has increased by 306.25% over the last month, indicating potential lack of confidence among insiders.
TD Cowen
$370
2026-10-08
TD Cowen
2026-10-08
目標價
$370
UBS
$395
2026-10-05
UBS
2026-10-05
目標價
$395
BofA
$400
2026-10-05
BofA
2026-10-05
目標價
$400
HSBC
$377
2026-09-28
HSBC
2026-09-28
目標價
$377
UBS
$400
2026-08-03
UBS
2026-08-03
目標價
$400
情境價格取自當年最後一個月度預測區間。機率為固定的模型權重(25 / 50 / 25),不構成保證。
Midterm Elections Outlook and Market Performance
Potential Threat of AI Agents to Banking Industry
AGNC Investment Maintains Stable Dividends Amid Market Volatility
J.P. Morgan Launches On-Chain Money Market Funds for U.S. Investors
J.P. Morgan Asset Management Expands Access to Tokenized Money Market Funds
JPMorgan Chase & Co. is a financial holding company engaged in investment banking, financial services for consumers and small businesses, commercial banking, financial transaction processing and asset management. It operates through three segments: Consumer & Community Banking (CCB), Commercial & Investment Bank (CIB), and Asset & Wealth Management (AWM). Its CCB segment offers products and services to consumers and small businesses through bank branches, ATMs, digital and telephone banking. Its CIB segment consists of banking and payments and markets and securities services, and offers a suite of investment banking, lending, payments, market-making, financing, custody and securities products and services to a global base of corporate and institutional clients. Its AWM segment offers investment and wealth management solutions. It offers multi-asset investment management solutions, retirement products and services, brokerage, custody, estate planning, lending, deposits, and others. It operates in the Financials sector (NATIONAL COMMERCIAL BANKS industry).
JPMorgan Chase is currently a hold due to its recent price decline and mixed analyst ratings. The stock is trading at $331.58, with an RSI of 38.33, indicating it is nearing oversold territory, but the forward P/E ratio of 13.50 suggests it is not undervalued compared to its peers. The main risk is the recent insider selling trend, which has increased by 306.25% over the last month, indicating potential lack of confidence among insiders.
28 analysts cover JPM: 13 rate it Buy, 13 Hold and 2 Sell. The average price target is 341.38.
Jamie Dimon's interview was circulated as "the economy is booming" and "US stocks are going to fall 40%," but the line really worth listening to closely is another one: inflation has been sticky for five years. The Wall Street Journal published an interview with JPMorgan CEO Jamie Dimon on Monday. English news alerts seized on the word "booming," while Chinese-language circles preferred to share the "40% drop" number. Both the optimistic and pessimistic versions spread quickly, but few people told the full version. The sentence "inflation has been sticky for five years" is neither scary nor exciting, and it is hard to get traffic with it in a headline. But for people with US stock positions, it matters more than the previous two phrases. Look at the data first. September CPI was 3.7% year over year, up from 3.4% in August, and only 2.4% before Iran acted. Gasoline prices rose 9.1% in a month, accounting for roughly half of that month's CPI increase. Core CPI was 2.6%, also above expectations. In September, the Federal Reserve raised rates by 25 basis points in a 12-0 unanimous vote, bringing the rate range back to 3.75% to 4.00%. Warsh said at the press conference: inflation is too high, and it has been too high for too long. The 10-year Treasury yield briefly touched 5.35% intraday earlier this month, a level last seen in 2002. Some will say not to take it too seriously. Dimon warned in 2022 that an "economic hurricane" was coming, yet the S&P 500 rose 24% in 2023. It is part of a bank CEO's job to talk about worst-case scenarios. That makes sense; his track record on turning points is indeed only average, and this time he also admitted that no one today knows when the downturn will come or why. But 3.7% inflation is not a forecast, it is a fact that has already happened, and you can verify it by looking at prices at the gas station. What Dimon described is actually a causal chain: the economy is too strong, employment is too stable, and prices are hard to bring down. Government deficits show no sign of narrowing, the world is rearming, and both the trading system and the healthcare system are being restructured. All of these changes push costs higher. He even included AI. Building data centers requires labor, steel, cement, and servers, all of which push prices higher in the short term; as for when AI will bring disinflation, he cannot say for sure either. Internally, JPMorgan has stress-tested rate hikes, rate cuts, stagflation, a 40% market drop, and credit spreads widening two to three times. He is not betting on which scenario will happen, but preparing in advance for each one. This means the script the market was familiar with last year, "rates falling all the way," has stopped working. The steadier the economy and the fuller employment is, the less reason the Federal Reserve has to ease. Now look at valuations. The S&P 500's forward P/E is about 19 times, which translates to an earnings yield of about 5.3%, while the 10-year Treasury yield is also around 5.3%. Buying a basket of America's best companies and lending money to the US government now offer roughly the same return. The risk premium stocks are supposed to provide has been almost entirely eaten up by rates. The fundamentals themselves are not bad. Among the small group of companies that have already reported, 84% beat expectations, profits are growing, and neither companies nor households are overly leveraged. Dimon confirmed all of this himself. The problem is that when the 10-year Treasury yield stands above 5%, companies whose stock prices depend more on stories three to five years out come under pressure first. How much of a portfolio is supported by real earnings this year and how much by distant expectations is a ratio worth calculating carefully. Next is the October 28 policy meeting. Futures markets are pricing more than 80% odds of standing pat and nearly 20% odds of another hike. If gasoline prices do not fall back, rate-hike expectations will only keep rising. The most memorable part of this interview is neither "booming" nor "a 40% drop," but what Dimon said: JPMorgan never guesses the timing, it just prepares for every scenario. That sounds like a truism, but look at your own portfolio and you will know that not many people have really prepared for more than two scenarios. No leverage and cash on hand, these two things are the most practical moat for ordinary investors.
展開
$JPM JPMorgan Chase doesn't look bad here after an 11%+ dip from the August highs to recent lows. Watch for a confirmed break and hold of this trendline. Will likely try to reclaim the 50 DMA next.
展開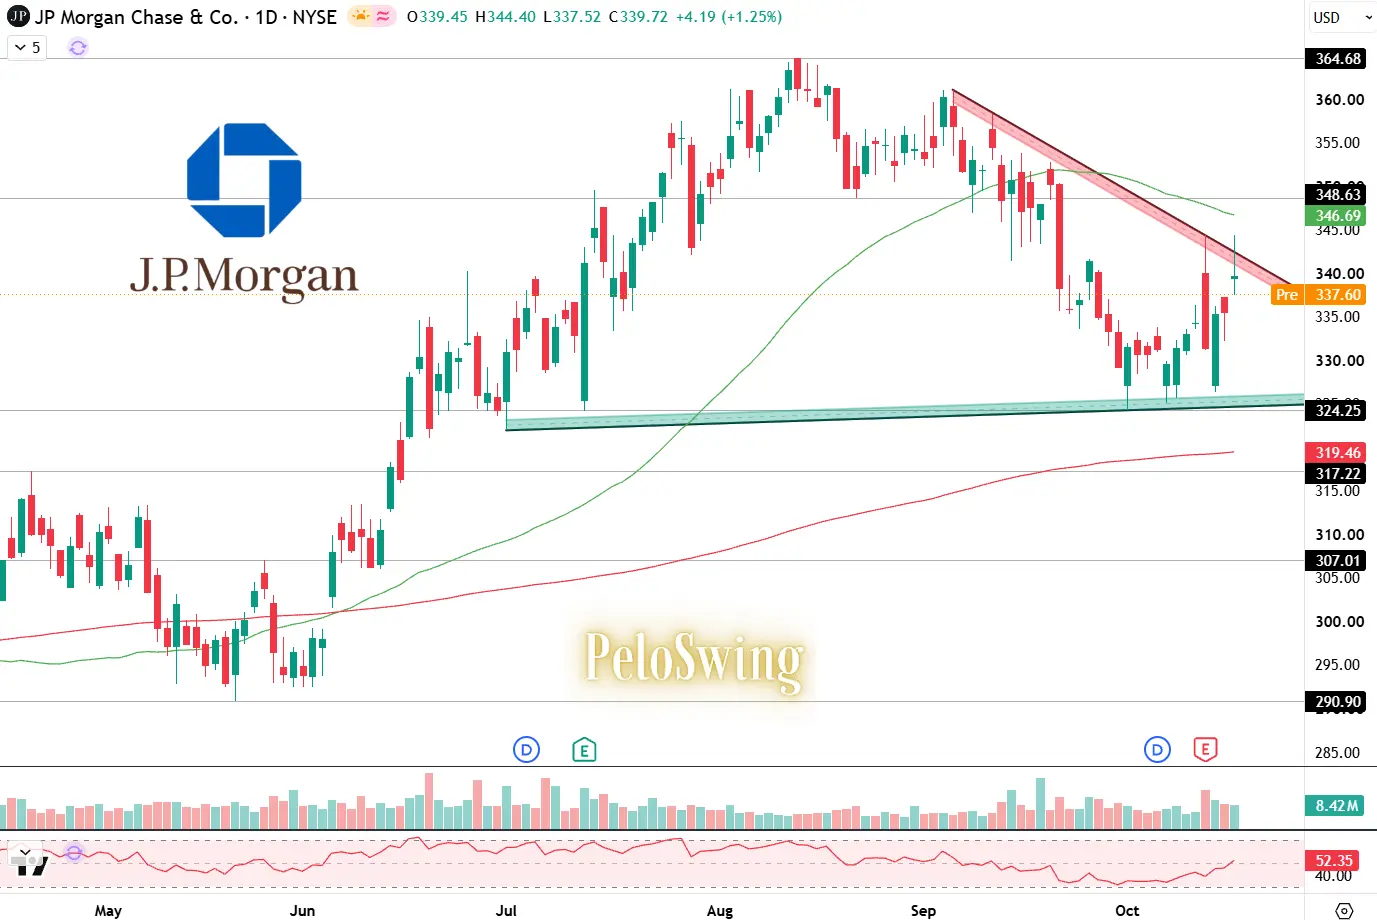
✨ Earnings season has begun: profit growth and mixed expectations side by side. 🔹 Q3 results from U.S. banks have started to roll in. Data from JPMorgan, Goldman Sachs, and Wells Fargo provide key signals for the sector's overall outlook. 📊 Reported data: 🔹 JPMorgan Chase: net profit rose 6% to $15.3 billion. EPS was $5.57, below the expected $5.90. Weak interest-related revenue drew attention. 🔹 Goldman Sachs: net profit jumped 29% to $5.29 billion. EPS reached $17.01, well above the expected $12.53. Annualized return on equity was 18.7%. 🔹 Wells Fargo: net profit rose to $6 billion, above expectations. EPS was $1.87, above the forecast of $1.84. However, revenue came in below expectations at $21.87 billion. ⚖️ Structural view: These bank results reflect how they are navigating the rate environment and capital market activity. Goldman Sachs' strong performance suggests investment banking and trading revenue are recovering, while weakness in JPMorgan's lending business indicates that market dynamics are squeezing profitability in some areas. Meanwhile, slower revenue growth at Wells Fargo shows that net interest margin pressure remains. These results can serve as a reference point for other alternatives to be announced later in this earnings season. 💬 On bank policy, do you mainly focus on profit growth or revenue quality? 👇 #BankEarnings #JPMorgan #GoldmanSachs #WellsFargo #Macro Not financial advice.
展開
Wall Street is already on-chain. BlackRock, Fidelity, Franklin Templeton, JPMorgan, Goldman Sachs, Citi, HSBC, UBS, Visa, Mastercard, PayPal, and more. Thirty financial giants have already launched tokenized assets or stablecoins. Do you still think RWA is just a narrative?
展開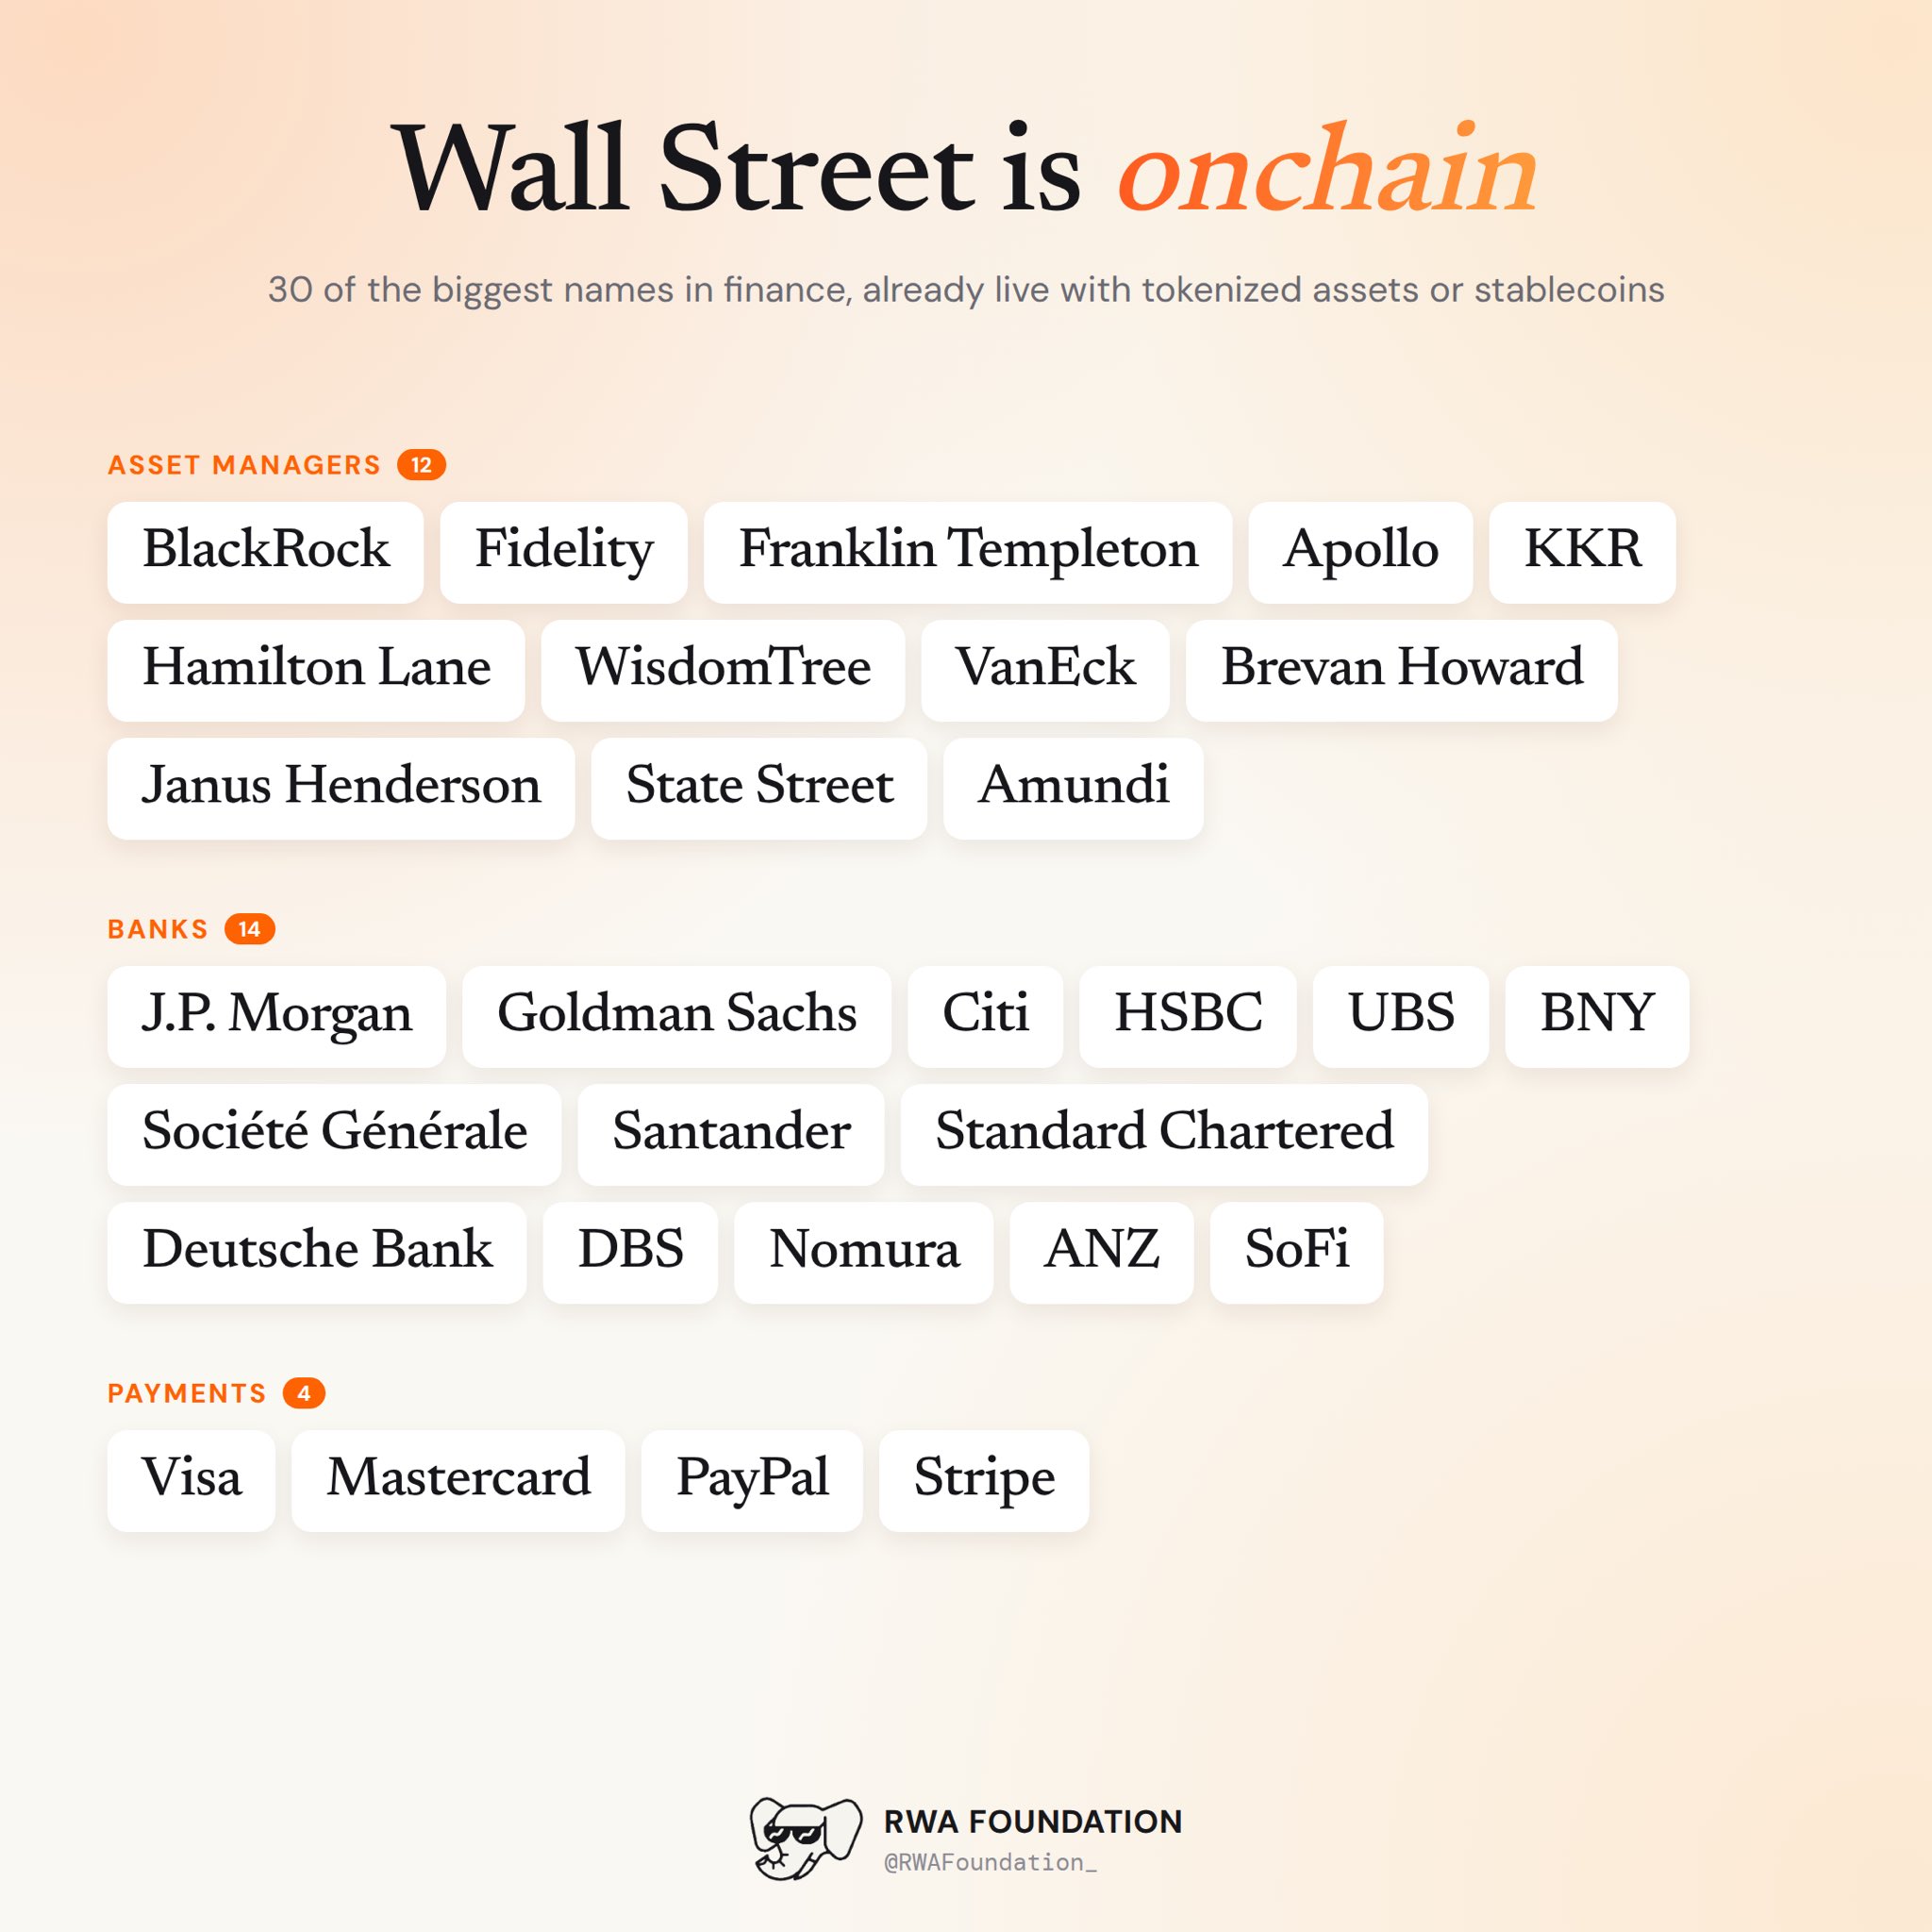
本頁僅供研究參考,不構成投資建議。模型可能出錯。過往表現不代表未來結果。