
C
CK Hutchison Holdings Limited
+ 持有HCM
+11.34%
3個月報酬率
$14.740
+0.582 (+3.95%)收盤時
HUTCHMED (China) Ltd is an investment holding company principally engaged in the manufacture and sale of pharmaceuticals. The Company operates its business through two segments. Oncology Immunology segment is engaged in the discovery, development and commercialization of targeted therapies and immunotherapies for the treatment of cancer and immunological diseases. Among it, research and development (R&D) includes research and development activities covering drug discovery, development, manufacturing and regulatory functions, out-licensing of in-house developed drugs, as well as administrative activities to support research and development operations, marketed products comprises the invoiced sales, marketing, manufacture and distribution of drugs developed from research and development activities. Other Ventures segment is engaged in the other commercial businesses which include the sales, marketing, manufacture and distribution of other prescription drugs and healthcare products.
HUTCHMED (China) Ltd is a good buy right now due to its current price of $14.05, which is below the analyst price targets of $16 to $18.50, indicating potential upside. The forward P/E ratio of 18.08 suggests reasonable valuation compared to its growth prospects, especially following the licensing agreement with GSK that could enhance revenue streams. However, the main risk is the high P/E ratio of 1239.37, indicating potential overvaluation if growth does not materialize as expected.
BofA
$18
2026-09-21
BofA
2026-09-21
目標價
$18
HSBC
$17.40
2026-09-08
HSBC
2026-09-08
目標價
$17.40
Daiwa
$18.50
2026-09-03
Daiwa
2026-09-03
目標價
$18.50
Goldman Sachs
$14
2026-07-23
Goldman Sachs
2026-07-23
目標價
$14
BofA
$17
2026-07-07
BofA
2026-07-07
目標價
$17
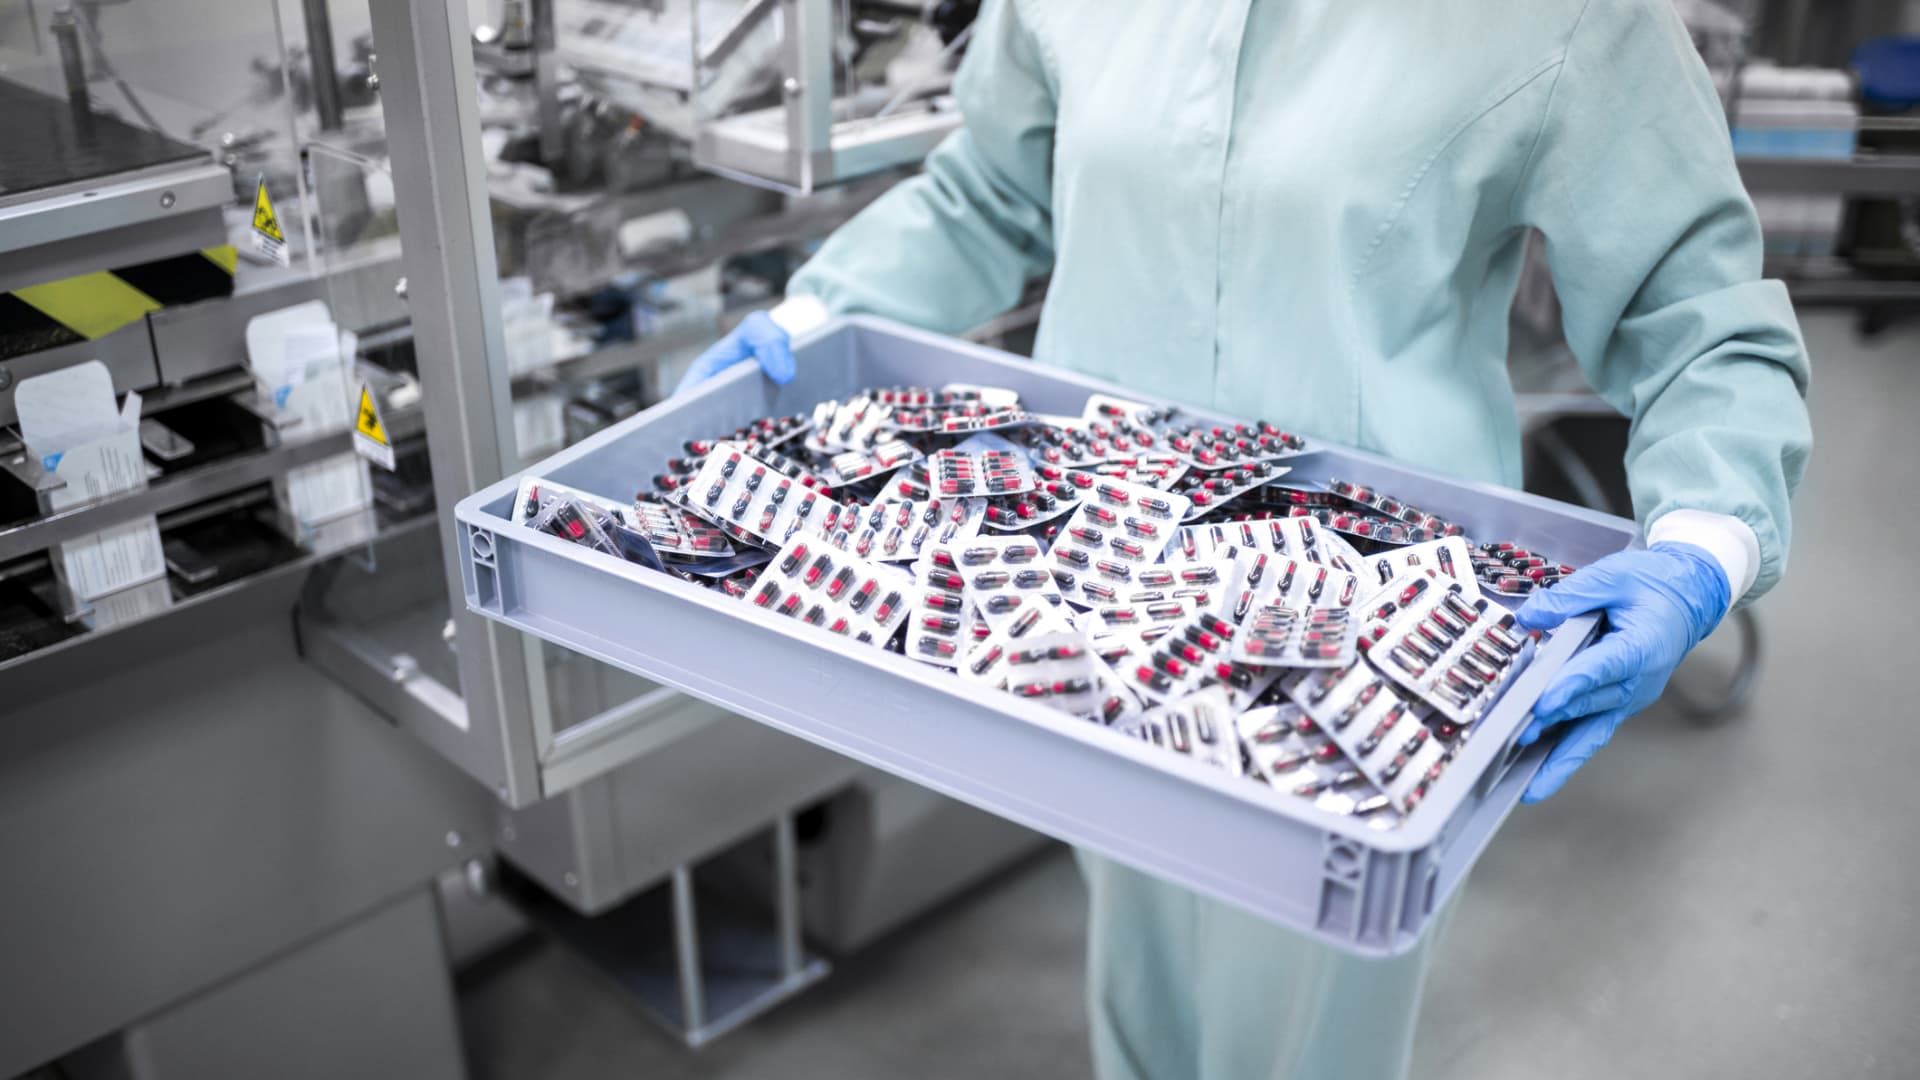
Optimistic Outlook for Sino-U.S. Pharmaceutical Cooperation
Hutchmed Licenses Drug Development Rights to GSK

HUTCHMED Enters Exclusive License Agreement with GSK for HMPL-A830
HUTCHMED Reports Positive SANOVO Trial Results for Lung Cancer Treatment
HUTCHMED's ATLED Receives Conditional Approval in China
HUTCHMED (China) Ltd is an investment holding company principally engaged in the manufacture and sale of pharmaceuticals. The Company operates its business through two segments. Oncology Immunology segment is engaged in the discovery, development and commercialization of targeted therapies and immunotherapies for the treatment of cancer and immunological diseases. Among it, research and development (R&D) includes research and development activities covering drug discovery, development, manufacturing and regulatory functions, out-licensing of in-house developed drugs, as well as administrative activities to support research and development operations, marketed products comprises the invoiced sales, marketing, manufacture and distribution of drugs developed from research and development activities. Other Ventures segment is engaged in the other commercial businesses which include the sales, marketing, manufacture and distribution of other prescription drugs and healthcare products. It operates in the Healthcare sector (PHARMACEUTICAL PREPARATIONS industry).
HUTCHMED (China) Ltd is a good buy right now due to its current price of $14.05, which is below the analyst price targets of $16 to $18.50, indicating potential upside. The forward P/E ratio of 18.08 suggests reasonable valuation compared to its growth prospects, especially following the licensing agreement with GSK that could enhance revenue streams. However, the main risk is the high P/E ratio of 1239.37, indicating potential overvaluation if growth does not materialize as expected.
4 analysts cover HCM: 4 rate it Buy, 0 Hold and 0 Sell. The average price target is 22.00.
暫無貼文
註冊或登入後參與討論本頁僅供研究參考,不構成投資建議。模型可能出錯。過往表現不代表未來結果。