
樂
樂觀
樂觀 · 25%CPS
$25.10
情境價格
$20.220
-0.168 (-0.83%)收盤時
Cooper-Standard Holdings Inc. is a manufacturer of sealing and fluid handling systems (consisting of fuel and brake delivery and fluid transfer systems) and components. The Company's products are primarily for use in passenger vehicles and light trucks that are manufactured by global automotive original equipment manufacturers (OEMs) and replacement markets. The Company operates through two segments: Sealing Systems and Fluid Handling Systems. The Sealing Systems segment is comprised of products that are designed and manufactured to protect vehicle interiors from weather, dust and noise intrusion for an improved driving experience. The Fluid Handling Systems segment is comprised of products that help convey, connect, control and communicate throughout fluid systems for superior performance across diverse powertrains. The Company's brands include eCoFlow, FlushSeal, Gen III Posi-Lock, Easy-Lock, MagAlloy, Ergo-Lock +, PlastiCool and Fortrex.
Cooper-Standard Holdings Inc is not a good buy right now due to its current price of $20.39, which is significantly below its 200-day simple moving average of $28.979, indicating a bearish trend. Additionally, the company has a forward P/E ratio of 62.89, which suggests that it is overvalued based on future earnings expectations. The main risk is the company's recent performance, with a year-to-date change of -37.43%, reflecting significant underperformance compared to the market.
Citi
$25
2026-10-09
Citi
2026-10-09
目標價
$25
Citi
$31
2026-08-12
Citi
2026-08-12
目標價
$31
Stifel
$53
2026-07-20
Stifel
2026-07-20
目標價
$53
Stifel
$55
2026-04-14
Stifel
2026-04-14
目標價
$55
Freedom Capital
$57
2026-02-18
Freedom Capital
2026-02-18
目標價
$57
情境價格取自當年最後一個月度預測區間。機率為固定的模型權重(25 / 50 / 25),不構成保證。
Cooper-Standard to Release Q3 2026 Financial Results
Cooper Standard Appoints New Chief Commercial Officer

Cooper Standard Appoints New Chief Commercial Officer
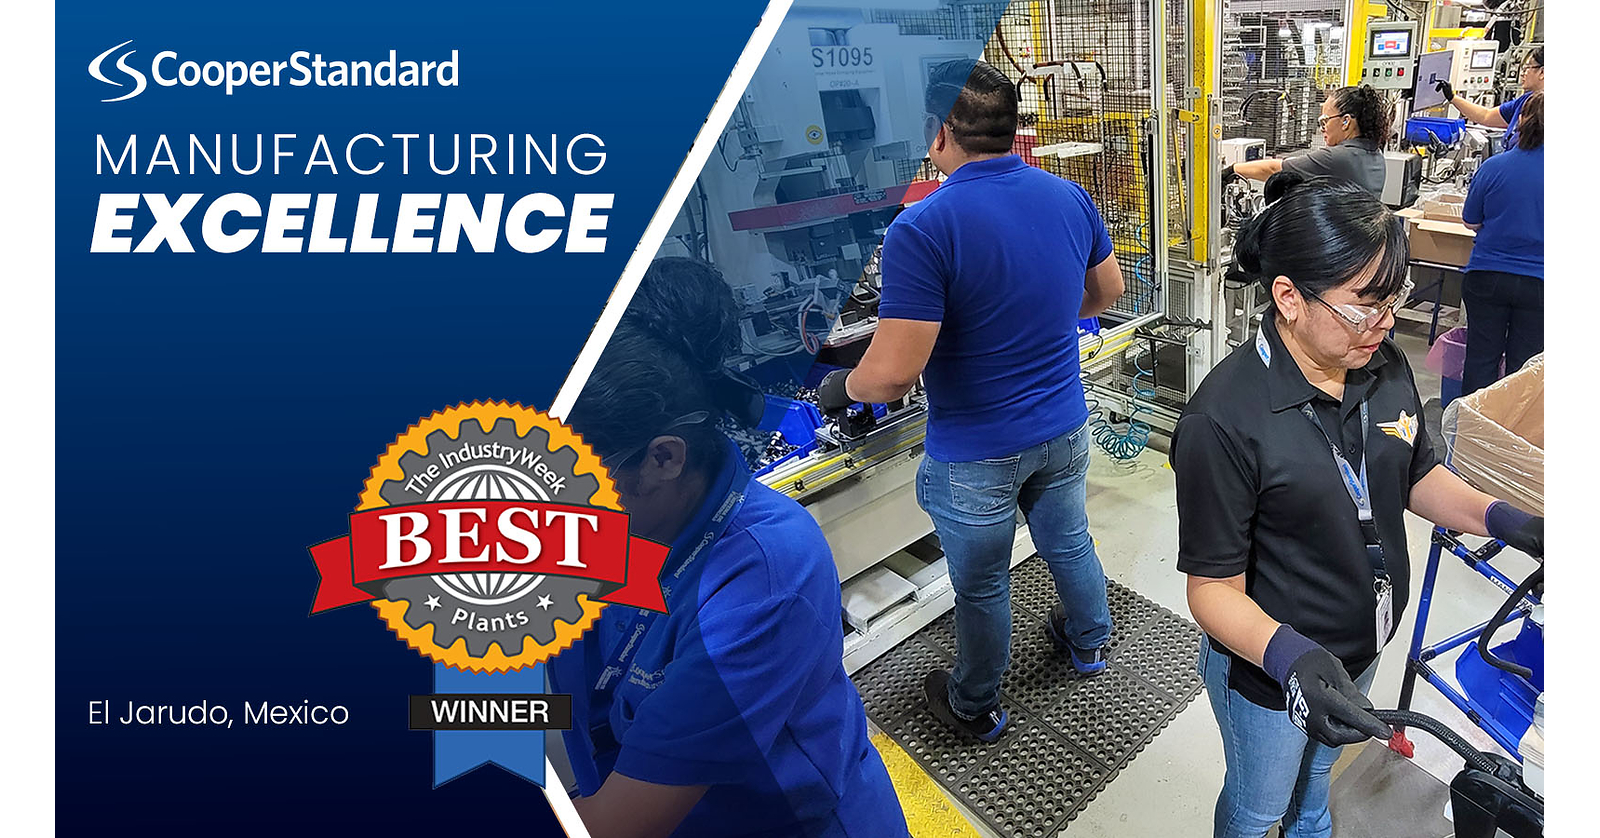
Cooper Standard's El Jarudo Plant Wins IndustryWeek's Best Plants Award
Cooper Standard's El Jarudo Plant Wins IndustryWeek Best Plants Award
Cooper-Standard Holdings Inc. is a manufacturer of sealing and fluid handling systems (consisting of fuel and brake delivery and fluid transfer systems) and components. The Company's products are primarily for use in passenger vehicles and light trucks that are manufactured by global automotive original equipment manufacturers (OEMs) and replacement markets. The Company operates through two segments: Sealing Systems and Fluid Handling Systems. The Sealing Systems segment is comprised of products that are designed and manufactured to protect vehicle interiors from weather, dust and noise intrusion for an improved driving experience. The Fluid Handling Systems segment is comprised of products that help convey, connect, control and communicate throughout fluid systems for superior performance across diverse powertrains. The Company's brands include eCoFlow, FlushSeal, Gen III Posi-Lock, Easy-Lock, MagAlloy, Ergo-Lock +, PlastiCool and Fortrex. It operates in the Consumer Cyclicals sector (MOTOR VEHICLE PARTS & ACCESSORIES industry).
Cooper-Standard Holdings Inc is not a good buy right now due to its current price of $20.39, which is significantly below its 200-day simple moving average of $28.979, indicating a bearish trend. Additionally, the company has a forward P/E ratio of 62.89, which suggests that it is overvalued based on future earnings expectations. The main risk is the company's recent performance, with a year-to-date change of -37.43%, reflecting significant underperformance compared to the market.
7 analysts cover CPS: 3 rate it Buy, 3 Hold and 1 Sell. The average price target is 39.00.
暫無貼文
註冊或登入後參與討論本頁僅供研究參考,不構成投資建議。模型可能出錯。過往表現不代表未來結果。