
乐
乐观
乐观 · 25%TPL
$1,531.28
情景价格
$333.670
-10.310 (-3.09%)收盘时
Texas Pacific Land Corporation is the landowner in the State of Texas with approximately 882,000 surface acres of land, principally concentrated in the Permian Basin. Its segments include Land and Resource Management and Water Services and Operations. The Land and Resource Management segment focuses on managing Company’s oil and gas royalty interest and surface acres located in 19 different countries. The Land and Resource Management segment encompasses the business of managing its approximately 882,000 surface acres of land and its approximately 207,000 NRA of oil and gas royalty interests, principally concentrated in the Permian Basin. This segment consists of royalties from oil and gas, revenues from easements, commercial leases and renewables, and land and material sales. The Water Services and Operations segment encompasses the business of providing a full-service water offering to operators in the Permian Basin. Its services include water sourcing and produced water disposal.
Texas Pacific Land Corp is a good buy right now, with a current price of 350.92 and a forward P/E of 37.74, suggesting reasonable valuation relative to future earnings. The company has shown strong revenue growth, with Q2 2026 revenue at 246.06 million USD, marking a significant increase from previous quarters. However, the RSI is at 47.30, indicating it is not yet overbought, which could present an entry opportunity. The main risk is the recent 5-day change of -2.79%, indicating potential short-term volatility.
情景价格取自当年最后一个月度预测区间。概率为固定的模型权重(25 / 50 / 25),不构成保证。
Investor Sentiments on Various Stocks
Oil Prices Surge After Attacks on Saudi Energy Facilities
Murray Stahl's Q2 2026 Investment Moves
Can Market Momentum Be Sustained?
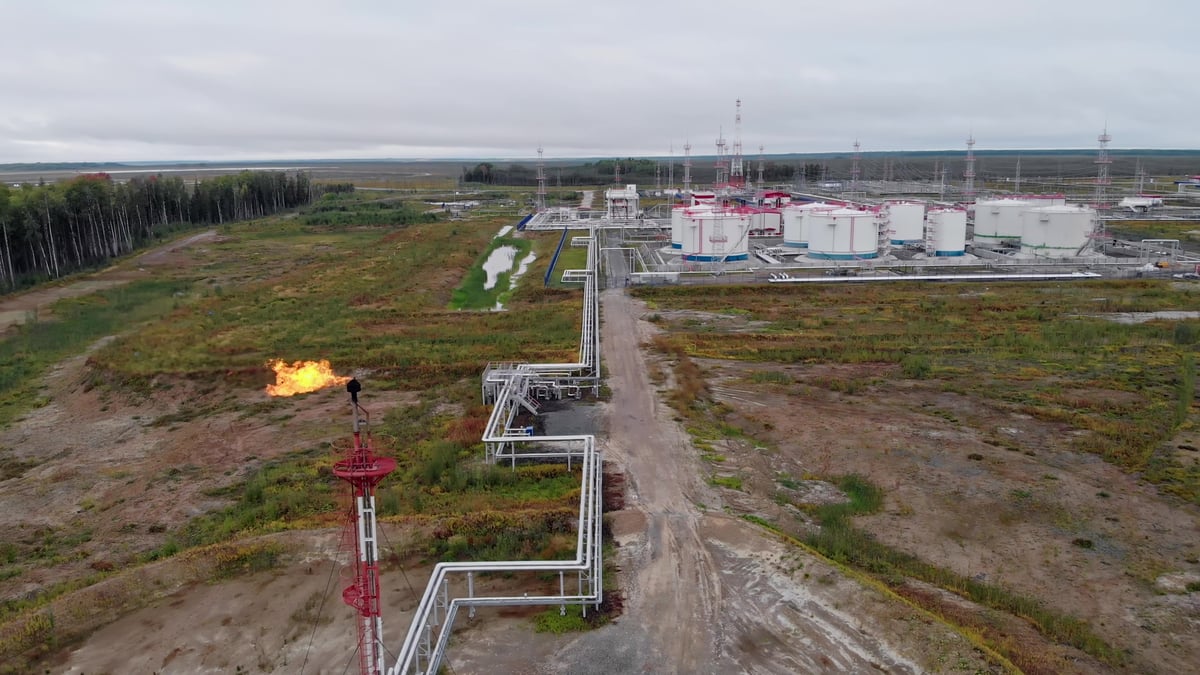
Texas Pacific Land Corporation Shares Surge 52.4% Amid Oil and AI Boom
Texas Pacific Land Corporation is the landowner in the State of Texas with approximately 882,000 surface acres of land, principally concentrated in the Permian Basin. Its segments include Land and Resource Management and Water Services and Operations. The Land and Resource Management segment focuses on managing Company’s oil and gas royalty interest and surface acres located in 19 different countries. The Land and Resource Management segment encompasses the business of managing its approximately 882,000 surface acres of land and its approximately 207,000 NRA of oil and gas royalty interests, principally concentrated in the Permian Basin. This segment consists of royalties from oil and gas, revenues from easements, commercial leases and renewables, and land and material sales. The Water Services and Operations segment encompasses the business of providing a full-service water offering to operators in the Permian Basin. Its services include water sourcing and produced water disposal. It operates in the Energy sector (OIL ROYALTY TRADERS industry).
Texas Pacific Land Corp is a good buy right now, with a current price of 350.92 and a forward P/E of 37.74, suggesting reasonable valuation relative to future earnings. The company has shown strong revenue growth, with Q2 2026 revenue at 246.06 million USD, marking a significant increase from previous quarters. However, the RSI is at 47.30, indicating it is not yet overbought, which could present an entry opportunity. The main risk is the recent 5-day change of -2.79%, indicating potential short-term volatility.
暂无帖子
注册或登录后参与讨论本页仅供研究参考,不构成投资建议。模型可能出错。过往表现不代表未来结果。