乐
乐观
乐观 · 25%ANET
$139.86
情景价格
$185.580
-9.353 (-5.04%)收盘时
Arista Networks, Inc. is a provider of data-driven, client-to-cloud networking for large artificial intelligence (AI), data center, campus and routing environments. The Company's cloud networking solutions consist of its Extensible Operating System (EOS), a set of network applications and its Ethernet switching and routing platforms. Its platforms deliver availability, agility, automation, analytics, and security through an advanced network operating stack. It offers a robust set of solutions, ranging from modular and fixed-form-factor campus spine switches to Power-over-Ethernet (PoE) leaf switches and Wi-Fi access points, all managed through CloudVision. The Company's network-as-a-service approach empowers customers of all sizes to leverage their data through offerings spanning three categories: Core (AI, Cloud, and Data Center Networking), Cognitive Adjacencies (Campus and Routing), and Cognitive Networks (Software and Services).
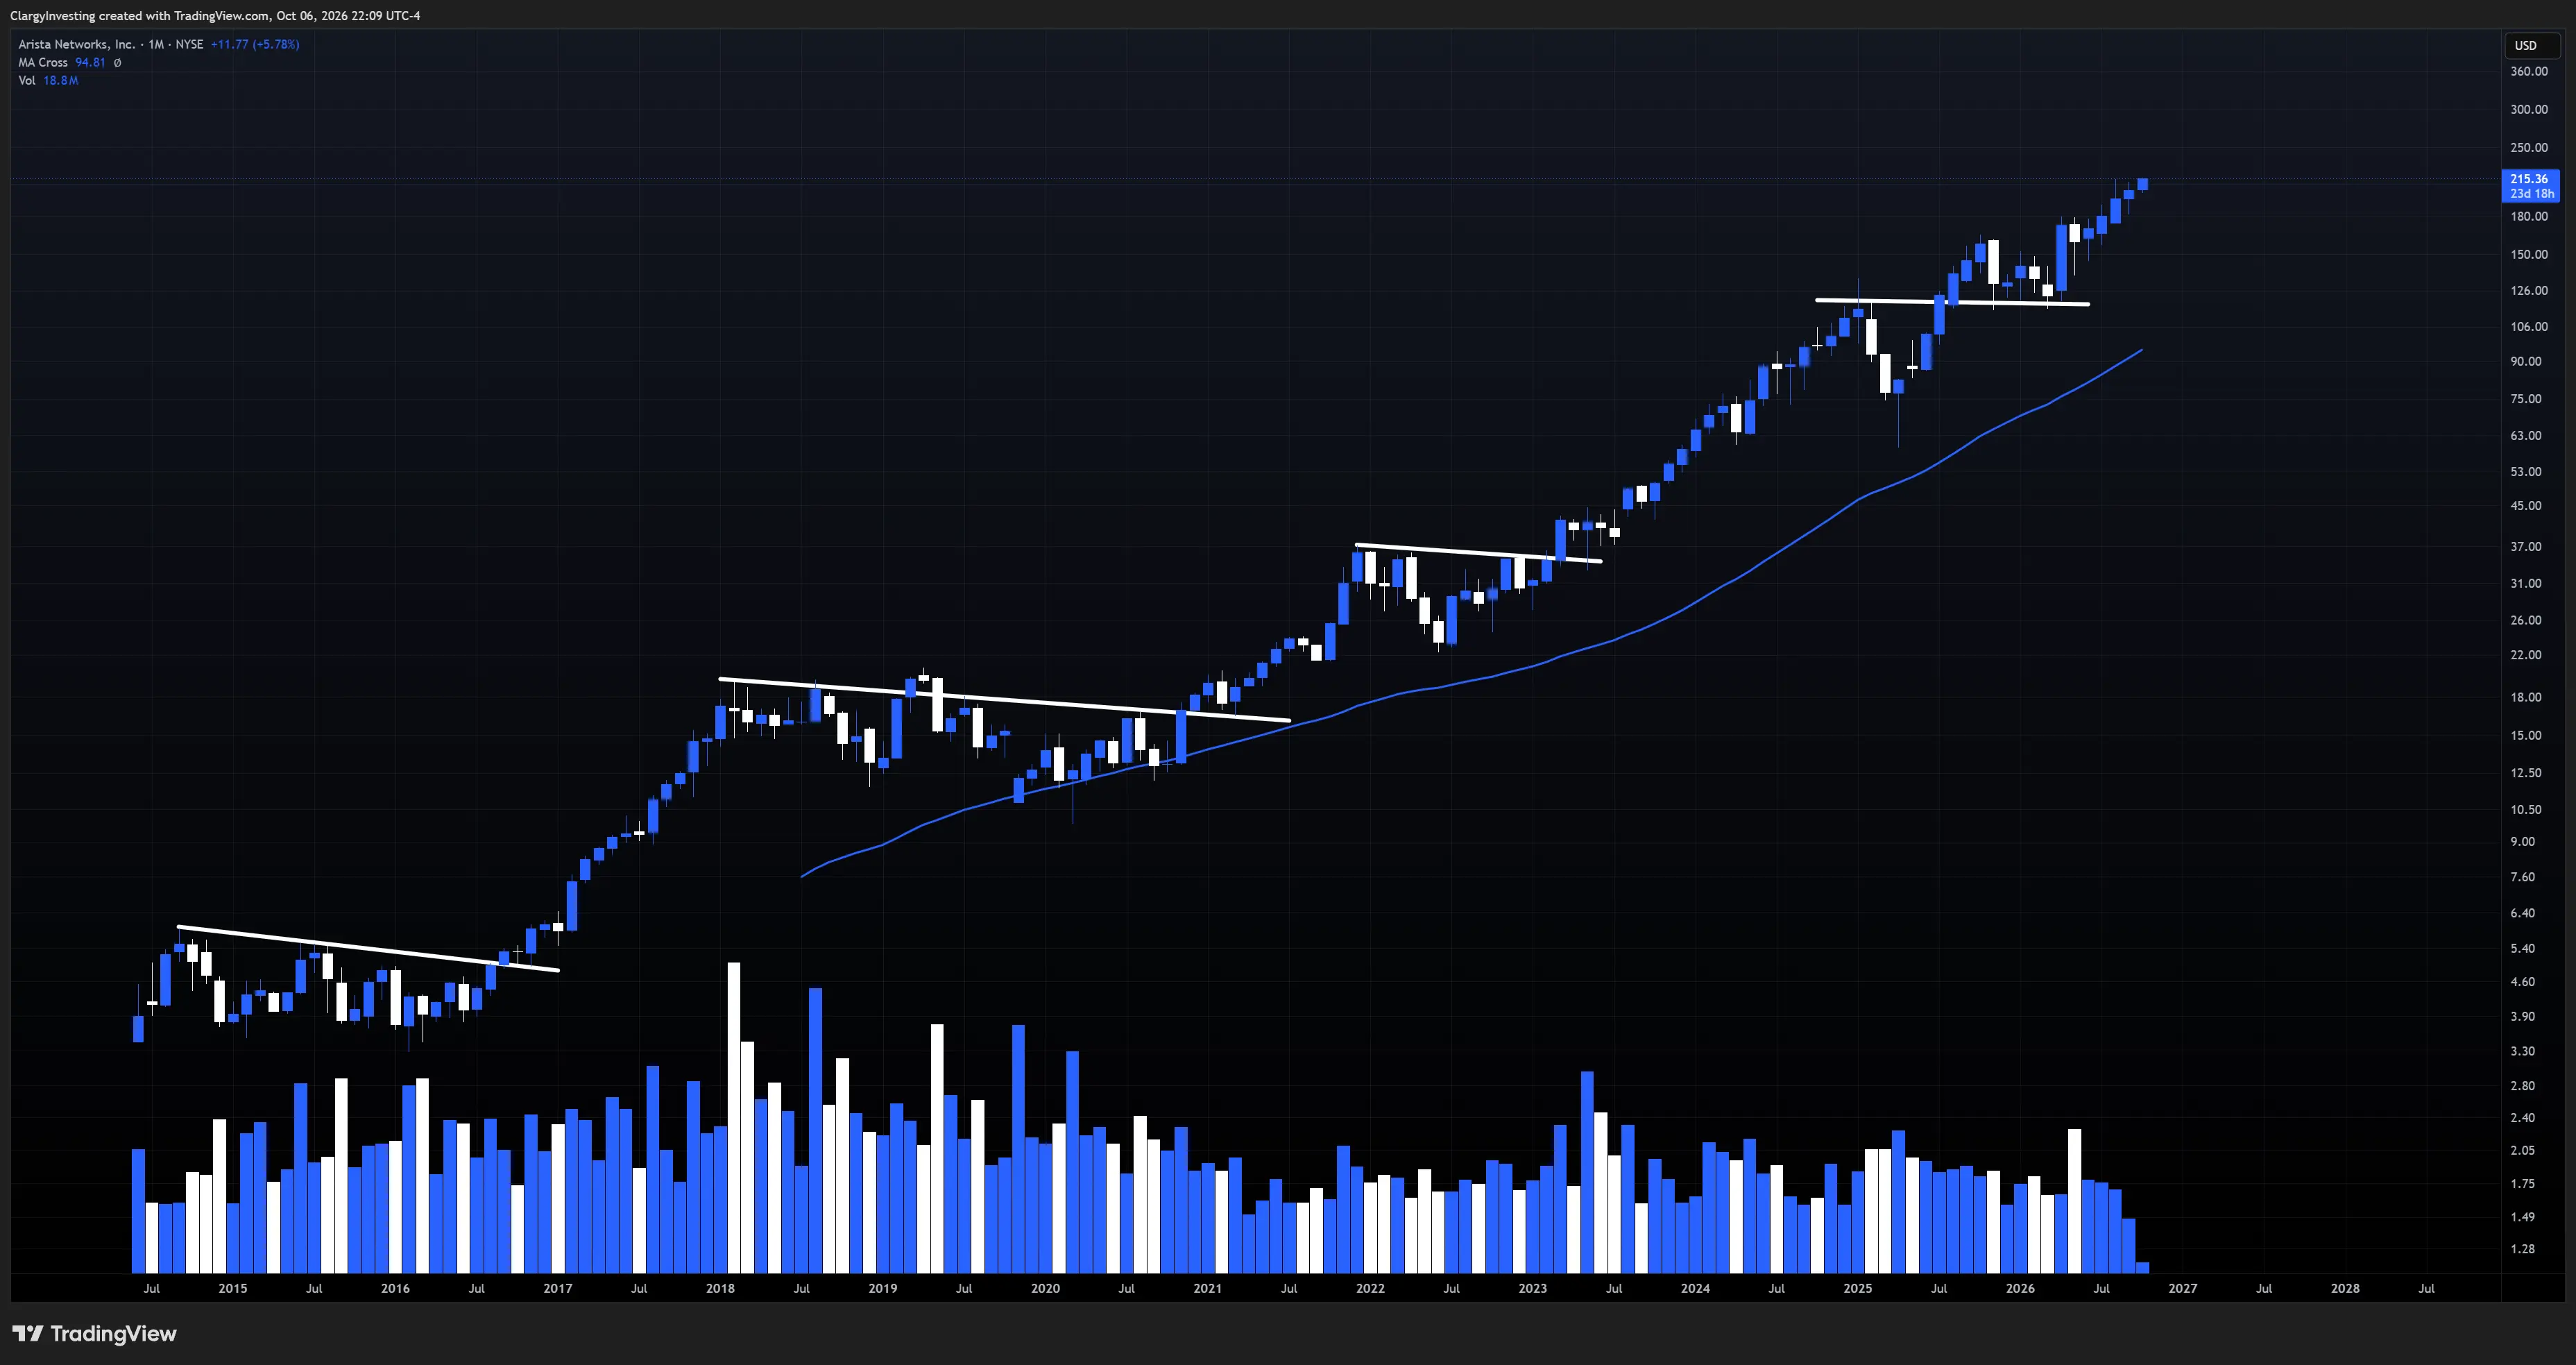
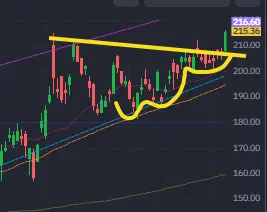
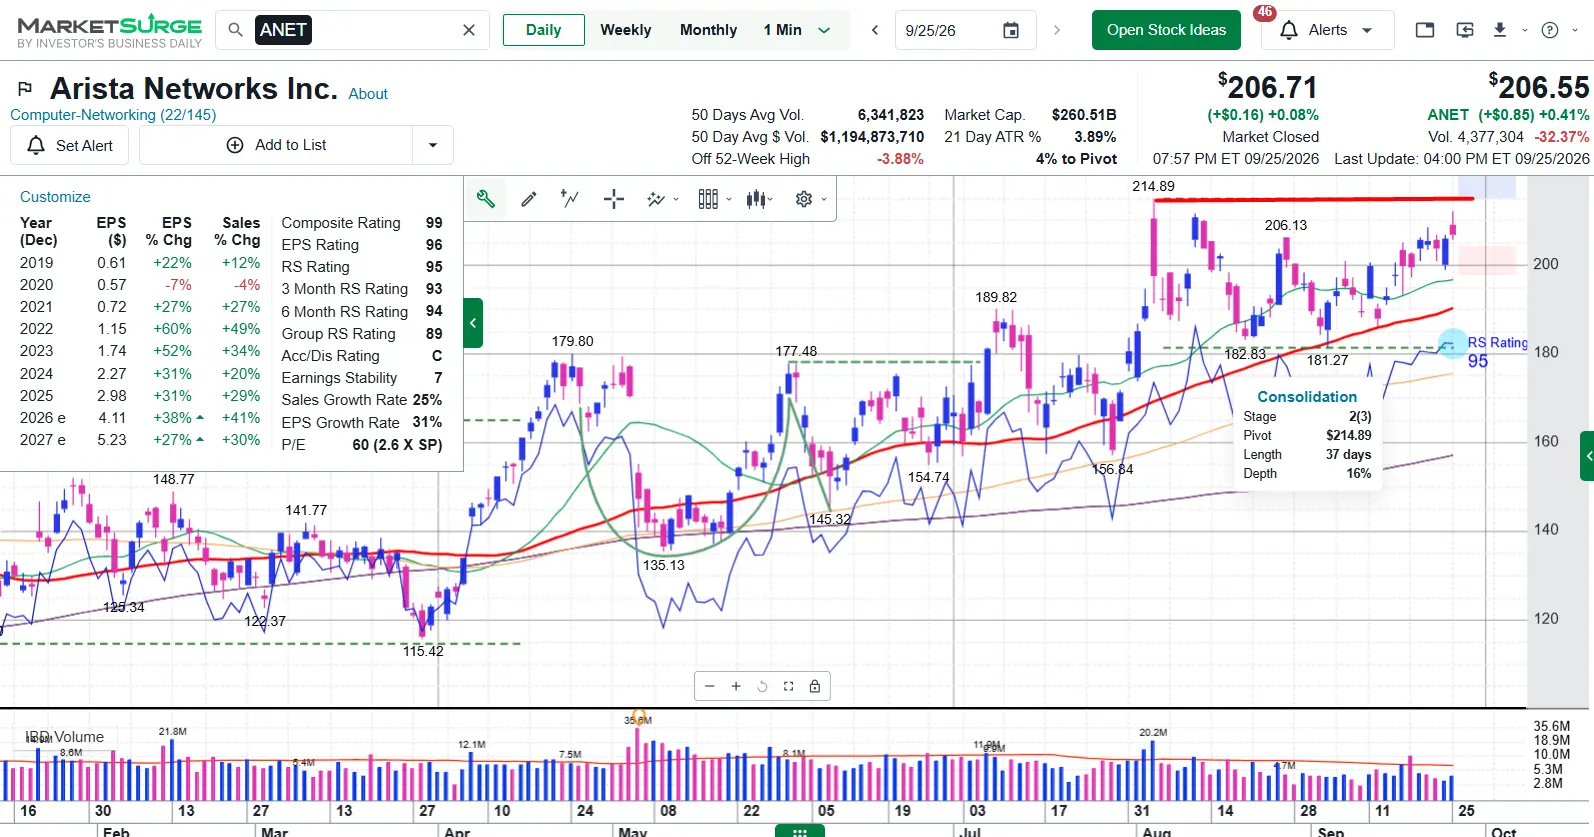
Arista Networks Inc is a good buy right now due to its strong revenue growth and positive market outlook. The current price is $216.74, and the company reported a 38% year-over-year revenue growth in Q2, reaching $3 billion. Additionally, analysts have set a price target range of $220 to $280, indicating significant upside potential. However, there is a risk associated with customer concentration, as Microsoft accounts for over 25% of revenue, which could impact stability if their relationship falters.
Citi
$248
2026-10-08
Citi
2026-10-08
目标价
$248
Bernstein
$250
2026-09-30
Bernstein
2026-09-30
目标价
$250
Deutsche Bank
$220
2026-08-31
Deutsche Bank
2026-08-31
目标价
$220
Rosenblatt
$280
2026-08-05
Rosenblatt
2026-08-05
目标价
$280
Goldman Sachs
$225
2026-08-05
Goldman Sachs
2026-08-05
目标价
$225
情景价格取自当年最后一个月度预测区间。概率为固定的模型权重(25 / 50 / 25),不构成保证。
Arista Networks Emerges as Key Player in AI Infrastructure
Tech Giants Set to Spend $745 Billion on Capital Expenditures
Dell Shares Plunge 11% Amid AI Spending Concerns
Investment Comparison: Arista vs. IBM
Analysis of AI Accelerator Market Dynamics
Arista Networks, Inc. is a provider of data-driven, client-to-cloud networking for large artificial intelligence (AI), data center, campus and routing environments. The Company's cloud networking solutions consist of its Extensible Operating System (EOS), a set of network applications and its Ethernet switching and routing platforms. Its platforms deliver availability, agility, automation, analytics, and security through an advanced network operating stack. It offers a robust set of solutions, ranging from modular and fixed-form-factor campus spine switches to Power-over-Ethernet (PoE) leaf switches and Wi-Fi access points, all managed through CloudVision. The Company's network-as-a-service approach empowers customers of all sizes to leverage their data through offerings spanning three categories: Core (AI, Cloud, and Data Center Networking), Cognitive Adjacencies (Campus and Routing), and Cognitive Networks (Software and Services). It operates in the Technology sector (COMPUTER COMMUNICATIONS EQUIPMENT industry).
Arista Networks Inc is a good buy right now due to its strong revenue growth and positive market outlook. The current price is $216.74, and the company reported a 38% year-over-year revenue growth in Q2, reaching $3 billion. Additionally, analysts have set a price target range of $220 to $280, indicating significant upside potential. However, there is a risk associated with customer concentration, as Microsoft accounts for over 25% of revenue, which could impact stability if their relationship falters.
25 analysts cover ANET: 16 rate it Buy, 9 Hold and 0 Sell. The average price target is 172.88.
$ANET Arista Networks initiated with an Outperform at Bernstein Bernstein initiated coverage of Arista Networks with an Outperform rating and a $250 price target. The firm rolled out coverage of the U.S. networking group with a positive view. Networking and optical companies will be "structural winners" within AI infrastructure, the analyst tells investors in a research note. Bernstein believes there is more upside than downside to AI spend expectations, and sees the risk/rewards on exposed stocks as positive. While an overbuild is still possible, demand continues to exceed supply and the assumptions needed to underwrite continued investments do not appear aggressive compared to the pace of adoption, the firm contends.
展开
本页仅供研究参考,不构成投资建议。模型可能出错。过往表现不代表未来结果。