B
Bull
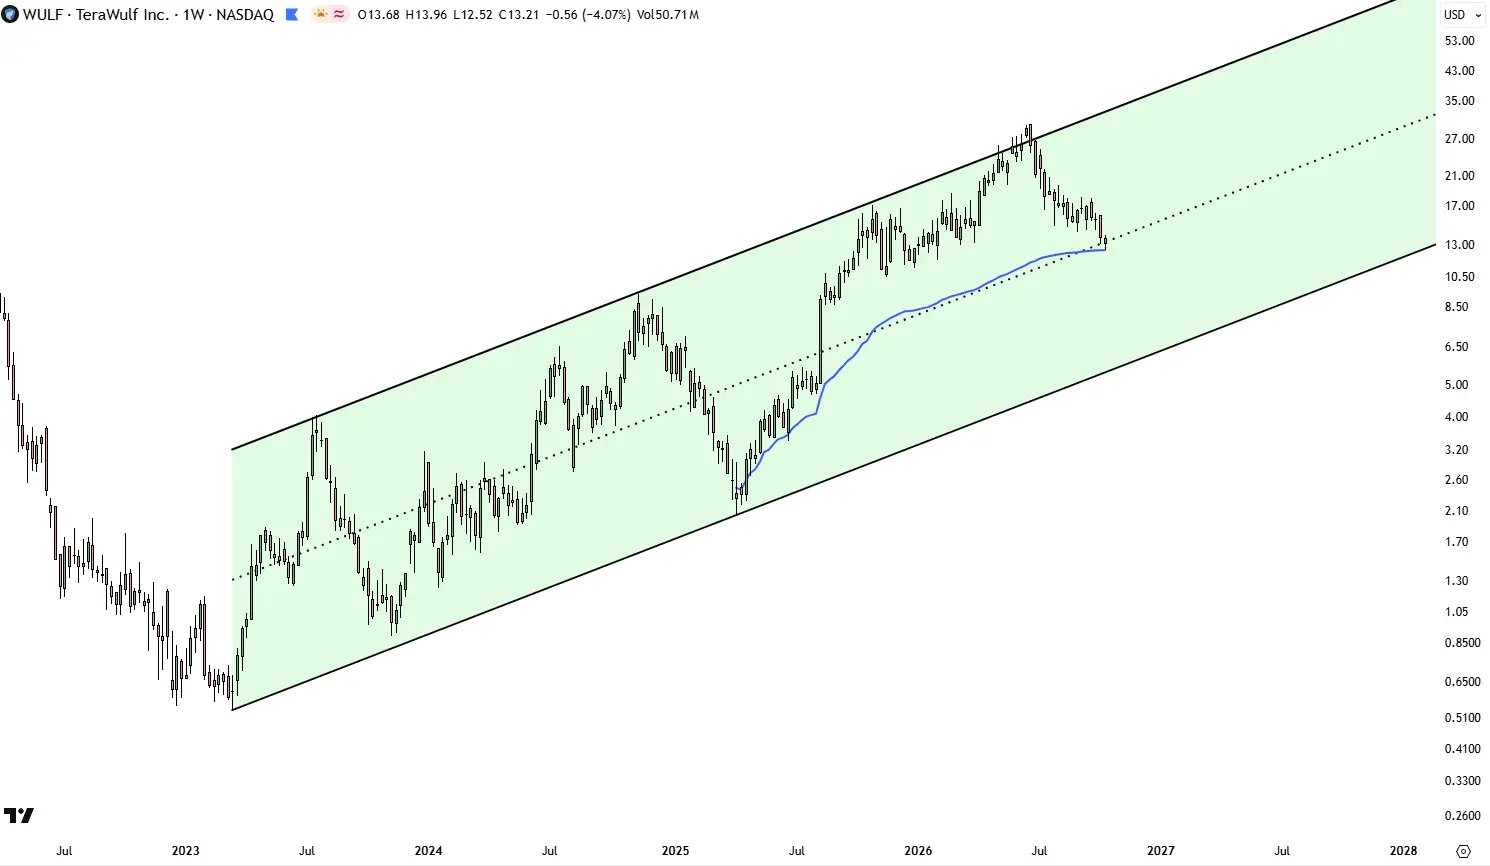
Bull · 25%WULF
$6.57
Scenario price
$13.210
-0.159 (-1.20%)At close
TeraWulf Inc. develops, owns, and operates digital infrastructure platforms that support artificial intelligence (AI), high-performance computing (HPC), and other compute-intensive workloads. The Company uses power infrastructure, grid connectivity, and development sites to provide capacity for data center and compute deployments. The Company operates in energy markets and grid integration and provides infrastructure for AI and computing workloads in the United States. The Company operates through two segments: Digital Asset Mining and HPC Leasing. Digital Asset Mining consists of providing hash computation services to a mining pool operator facilitating transaction validation on the global bitcoin network using its fleet of application-specific integrated circuit miners. HPC Leasing consists of providing high-density colocation services to third parties for HPC operations. Its subsidiaries include Akela Data LLC, Big Country Wulf LLC, Lake Hawkeye LLC, and others.
TeraWulf Inc is a good buy right now due to its recent expansion plans and positive analyst ratings. The current price is $13.77, significantly below the analyst price targets of $65 and $30, indicating a potential upside of approximately 371% and 118% respectively. Additionally, the company has increased its data campus capacity to 1 GW, which enhances its competitive position in the market. However, the main risk is the high debt-to-equity ratio of 3533.84%, which indicates significant financial leverage and potential vulnerability in adverse market conditions.
Scenario prices are the last monthly forecast band of the current year. Probabilities are fixed model weights (25 / 50 / 25), not guarantees.
TeraWulf Schedules Q3 Earnings Conference Call
Morgan Stanley Sees Growth Potential for eBay
TD Cowen Initiates Buy Rating on TeraWulf with $21 Price Target
Morgan Stanley Lowers Price Targets for Bitcoin Miners Amid AI Infrastructure Shift
Comparative Analysis of Iren and Cipher Digital
TeraWulf Inc. develops, owns, and operates digital infrastructure platforms that support artificial intelligence (AI), high-performance computing (HPC), and other compute-intensive workloads. The Company uses power infrastructure, grid connectivity, and development sites to provide capacity for data center and compute deployments. The Company operates in energy markets and grid integration and provides infrastructure for AI and computing workloads in the United States. The Company operates through two segments: Digital Asset Mining and HPC Leasing. Digital Asset Mining consists of providing hash computation services to a mining pool operator facilitating transaction validation on the global bitcoin network using its fleet of application-specific integrated circuit miners. HPC Leasing consists of providing high-density colocation services to third parties for HPC operations. Its subsidiaries include Akela Data LLC, Big Country Wulf LLC, Lake Hawkeye LLC, and others. It operates in the Technology sector (FINANCE SERVICES industry).
TeraWulf Inc is a good buy right now due to its recent expansion plans and positive analyst ratings. The current price is $13.77, significantly below the analyst price targets of $65 and $30, indicating a potential upside of approximately 371% and 118% respectively. Additionally, the company has increased its data campus capacity to 1 GW, which enhances its competitive position in the market. However, the main risk is the high debt-to-equity ratio of 3533.84%, which indicates significant financial leverage and potential vulnerability in adverse market conditions.
$WULF (+2.8% pre) TeraWulf expands contracted power capacity at its Muskie Data Campus to 1 GW.
Show more
$WULF | Rothschild Redburn Initiates TeraWulf at Neutral with $15 PT on AI/HPC Diversification and Pipeline Risk Rothschild Redburn stays neutral as AI/HPC expansion and pipeline execution shape growth outlook.
Show more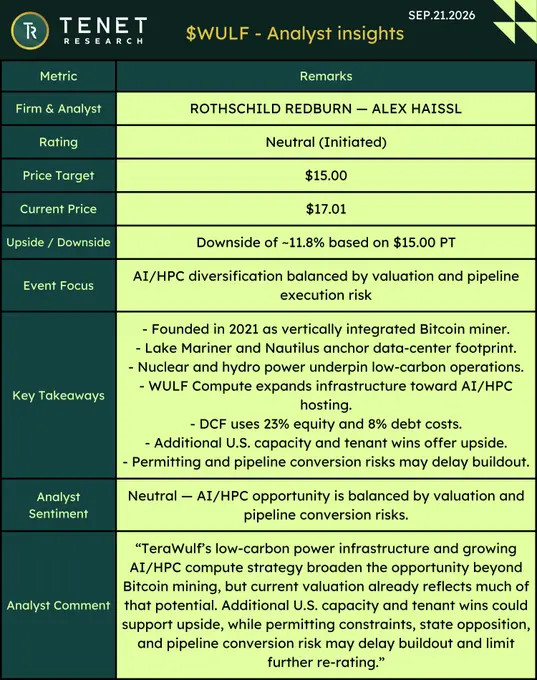
$WULF TeraWulf initiated with an Overweight at Wells Fargo Wells Fargo initiated coverage of TeraWulf with an Overweight rating and $30 price target. The firm has a favorable view of TeraWulf's track record and the quality of its contracted and pipeline sites. The company has contracted 839 megawatts of capacity with three different tenants, the analyst tells investors in a research note. Wells says TeraWulf was able to brownfield develop these sites with multiple high-voltage transmission line connections at a lower cost than a traditional greenfield site.
Show more
TeraWulf appears to be attempting to move past its recent downward trend, and it is not the only one—several others in this sector show a similar pattern. No rate hike expected next week? $WULF
Show more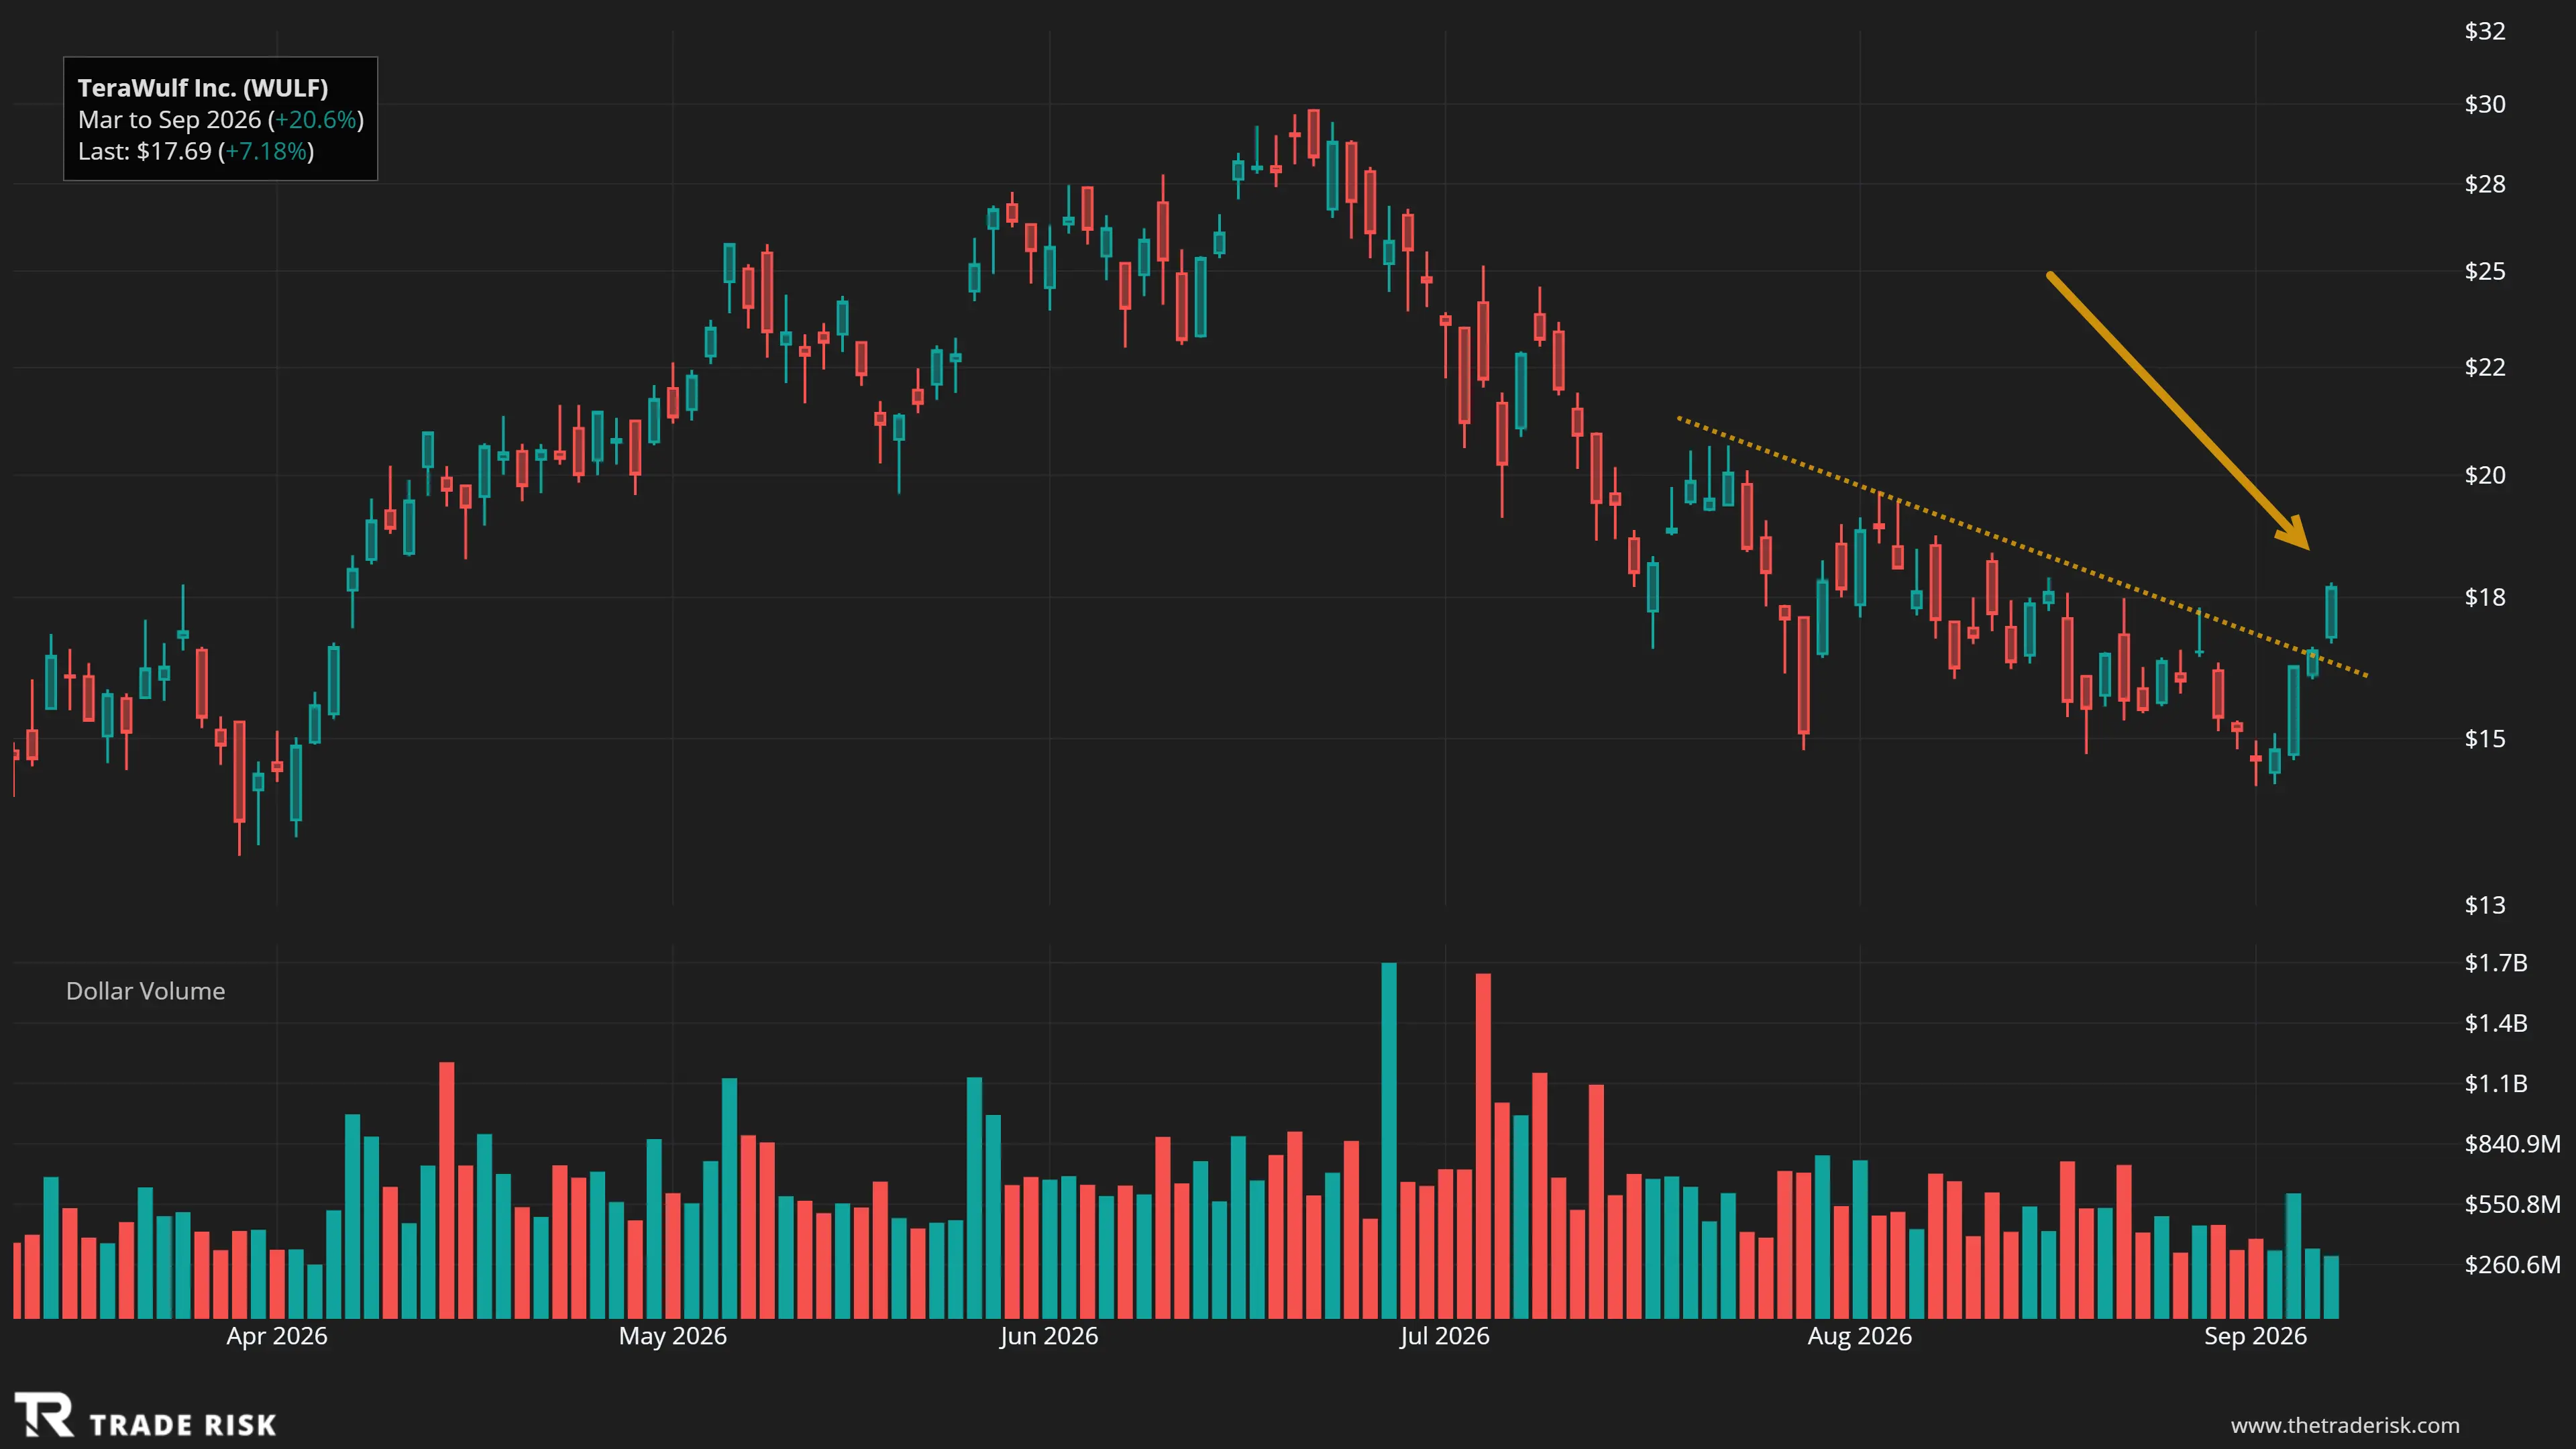
This page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.