
B
Bull
Bull · 25%HSAI
$37.75
Scenario price
$13.940
-0.502 (-3.60%)At close
Hesai Group is a holding company primarily engaged in providing three-dimensional light detection and ranging (LiDAR) solutions. The Company’s primary business includes the design, development, manufacturing, and sales of LiDAR products and gas sensor. The Company’s main products include Advanced Driver Assistance Systems (ADAS) products such as the AT series, ET series and FT series, as well as robot products such as the Pandar series, OT series, XT series and QT series, used for long-distance detection and blind spot detection. The products are used in passenger and commercial vehicles supporting ADAS, autonomous vehicles and robotics. The Company operates its businesses in the domestic market and overseas markets.
Hesai Group is a good buy right now due to its strong revenue growth and profitability. The current price is $16.01, and the company reported a 22% year-over-year increase in revenue to RMB 861 million ($127 million) for Q2 2026, alongside a 60% rise in net income to RMB 71 million ($10 million). The forward P/E ratio of 17.36 indicates a reasonable valuation compared to its growth potential. However, the main risk is the recent downgrade in price targets by analysts, with Goldman Sachs lowering its target to $31 from $35, which could indicate market volatility ahead.
Scenario prices are the last monthly forecast band of the current year. Probabilities are fixed model weights (25 / 50 / 25), not guarantees.
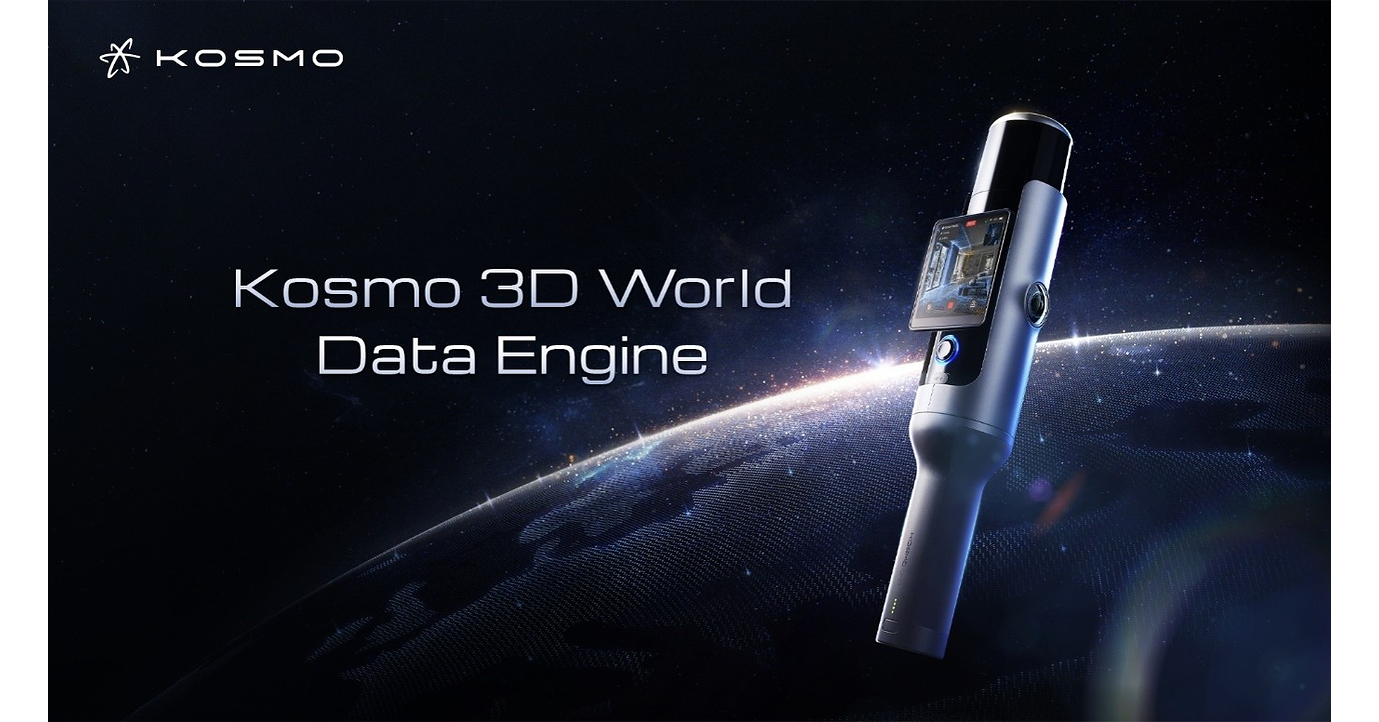
Hesai Launches Kosmo 3D Data Engine to Transform Physical AI
Humanoid Robot Market Booms with Component Suppliers Leading Growth
Hesai Group Reports Strong Q2 2026 Earnings with Significant Growth
Hesai Group Q2 Earnings Analysis

Hesai Group Reports Strong Q2 2026 Financial Results
Hesai Group is a holding company primarily engaged in providing three-dimensional light detection and ranging (LiDAR) solutions. The Company’s primary business includes the design, development, manufacturing, and sales of LiDAR products and gas sensor. The Company’s main products include Advanced Driver Assistance Systems (ADAS) products such as the AT series, ET series and FT series, as well as robot products such as the Pandar series, OT series, XT series and QT series, used for long-distance detection and blind spot detection. The products are used in passenger and commercial vehicles supporting ADAS, autonomous vehicles and robotics. The Company operates its businesses in the domestic market and overseas markets. It operates in the Technology sector (GENERAL INDUSTRIAL MACHINERY AND EQUIPMENT, NOT EL industry).
Hesai Group is a good buy right now due to its strong revenue growth and profitability. The current price is $16.01, and the company reported a 22% year-over-year increase in revenue to RMB 861 million ($127 million) for Q2 2026, alongside a 60% rise in net income to RMB 71 million ($10 million). The forward P/E ratio of 17.36 indicates a reasonable valuation compared to its growth potential. However, the main risk is the recent downgrade in price targets by analysts, with Goldman Sachs lowering its target to $31 from $35, which could indicate market volatility ahead.
No posts yet
Sign up or log in to join the discussionThis page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.