
S
Scharf Investments, LLC
+ HoldingHLN
+9.07%
3M Return
$10.140
+0.010 (+0.10%)At close
Haleon plc is a consumer healthcare company. The Company’s product portfolio spans six major categories, including oral health, vitamins, minerals and supplements (VMS), pain relief, respiratory health, digestive health and therapeutic skin health and others. The Company's segments include North America, Europe, Asia Pacific, and International. Its respiratory health brands offer product solutions for a range of respiratory issues, including cold and flu, nasal congestion, coughs, and allergies. The Company’s oral health brands include Sensodyne, Polident, and Parodontax. Its VMS brands include Centrum, Emergen-C, and Caltrate. Its respiratory brands include Otrivin, Theraflu, Flonase, Contac, and Beechams. Its pain relief brands include Voltaren, Panadol, and Advil. Its digestive health brands include TUMS, ENO, and Benefiber. Its therapeutic skin health brands include Fenistil, Zovirax, and Bactroban.
Haleon PLC is a good buy right now as it has shown a strong recent performance with a 5-day change of +8.69% and a current price of $10.13, which is near the Fibonacci resistance level of $10.272. The RSI is at 87.905, indicating strong momentum, although it is approaching overbought territory. Additionally, the company has a gross margin of 64.51% in the latest quarter, showcasing solid profitability. The main risk is the recent downgrade by Rothschild & Co Redburn, which could affect investor sentiment.

Haleon Health House Opens in Toronto for Interactive Health Experience
Three Companies with Sustainable Dividend Growth
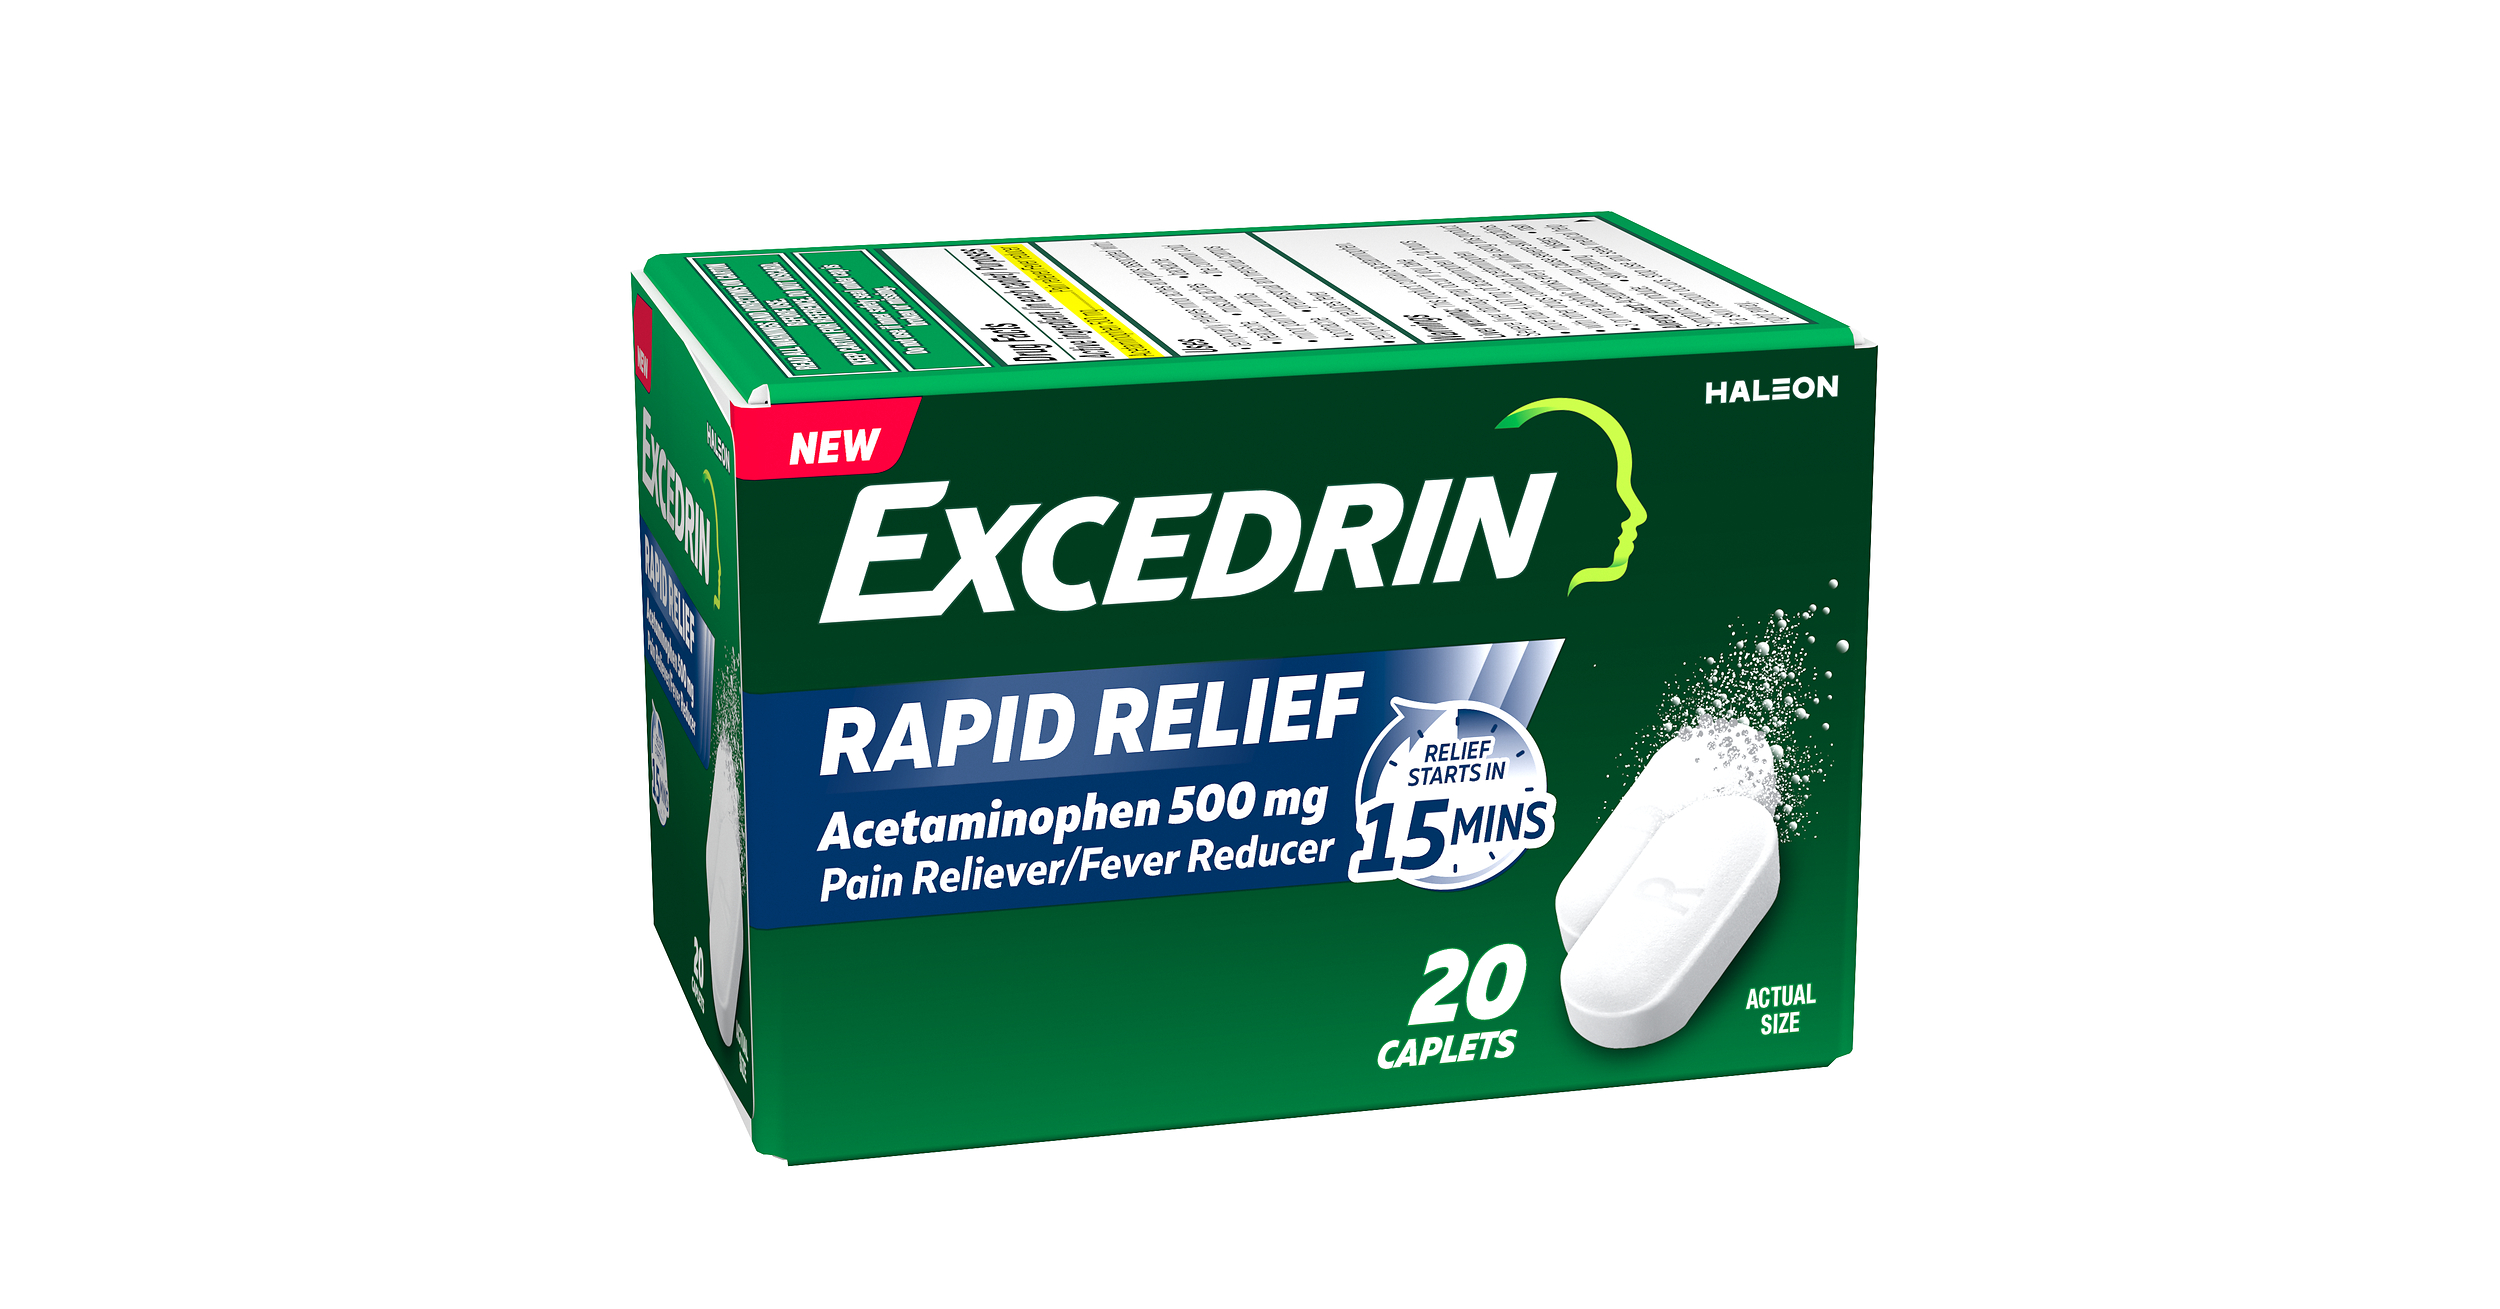
Excedrin Launches Rapid Relief Product Inspired by Nostalgia
Haleon Completes $1.34 Billion Bond Tender Offer

Haleon Announces Results of Bond Buyback Offer
Haleon plc is a consumer healthcare company. The Company’s product portfolio spans six major categories, including oral health, vitamins, minerals and supplements (VMS), pain relief, respiratory health, digestive health and therapeutic skin health and others. The Company's segments include North America, Europe, Asia Pacific, and International. Its respiratory health brands offer product solutions for a range of respiratory issues, including cold and flu, nasal congestion, coughs, and allergies. The Company’s oral health brands include Sensodyne, Polident, and Parodontax. Its VMS brands include Centrum, Emergen-C, and Caltrate. Its respiratory brands include Otrivin, Theraflu, Flonase, Contac, and Beechams. Its pain relief brands include Voltaren, Panadol, and Advil. Its digestive health brands include TUMS, ENO, and Benefiber. Its therapeutic skin health brands include Fenistil, Zovirax, and Bactroban. It operates in the Healthcare sector (PERFUMES, COSMETICS, AND OTHER TOILET PREPARATIONS industry).
Haleon PLC is a good buy right now as it has shown a strong recent performance with a 5-day change of +8.69% and a current price of $10.13, which is near the Fibonacci resistance level of $10.272. The RSI is at 87.905, indicating strong momentum, although it is approaching overbought territory. Additionally, the company has a gross margin of 64.51% in the latest quarter, showcasing solid profitability. The main risk is the recent downgrade by Rothschild & Co Redburn, which could affect investor sentiment.
No posts yet
Sign up or log in to join the discussionThis page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.