
C
CK Hutchison Holdings Limited
+ HoldingHCM
+12.55%
3M Return
$13.940
+0.475 (+3.41%)At close
HUTCHMED (China) Ltd is an investment holding company principally engaged in the manufacture and sale of pharmaceuticals. The Company operates its business through two segments. Oncology Immunology segment is engaged in the discovery, development and commercialization of targeted therapies and immunotherapies for the treatment of cancer and immunological diseases. Among it, research and development (R&D) includes research and development activities covering drug discovery, development, manufacturing and regulatory functions, out-licensing of in-house developed drugs, as well as administrative activities to support research and development operations, marketed products comprises the invoiced sales, marketing, manufacture and distribution of drugs developed from research and development activities. Other Ventures segment is engaged in the other commercial businesses which include the sales, marketing, manufacture and distribution of other prescription drugs and healthcare products.
HUTCHMED (China) Ltd is a good buy right now, trading at $14.1 with a forward P/E of 18.08, indicating reasonable valuation compared to its growth potential. The recent licensing agreement with GSK could generate significant future revenue, which supports the bullish sentiment. However, the high P/E ratio of 1215.37 poses a risk if earnings do not meet expectations.
BofA
$18
2026-09-21
BofA
2026-09-21
Price Target
$18
HSBC
$17.40
2026-09-08
HSBC
2026-09-08
Price Target
$17.40
Daiwa
$18.50
2026-09-03
Daiwa
2026-09-03
Price Target
$18.50
Goldman Sachs
$14
2026-07-23
Goldman Sachs
2026-07-23
Price Target
$14
BofA
$17
2026-07-07
BofA
2026-07-07
Price Target
$17
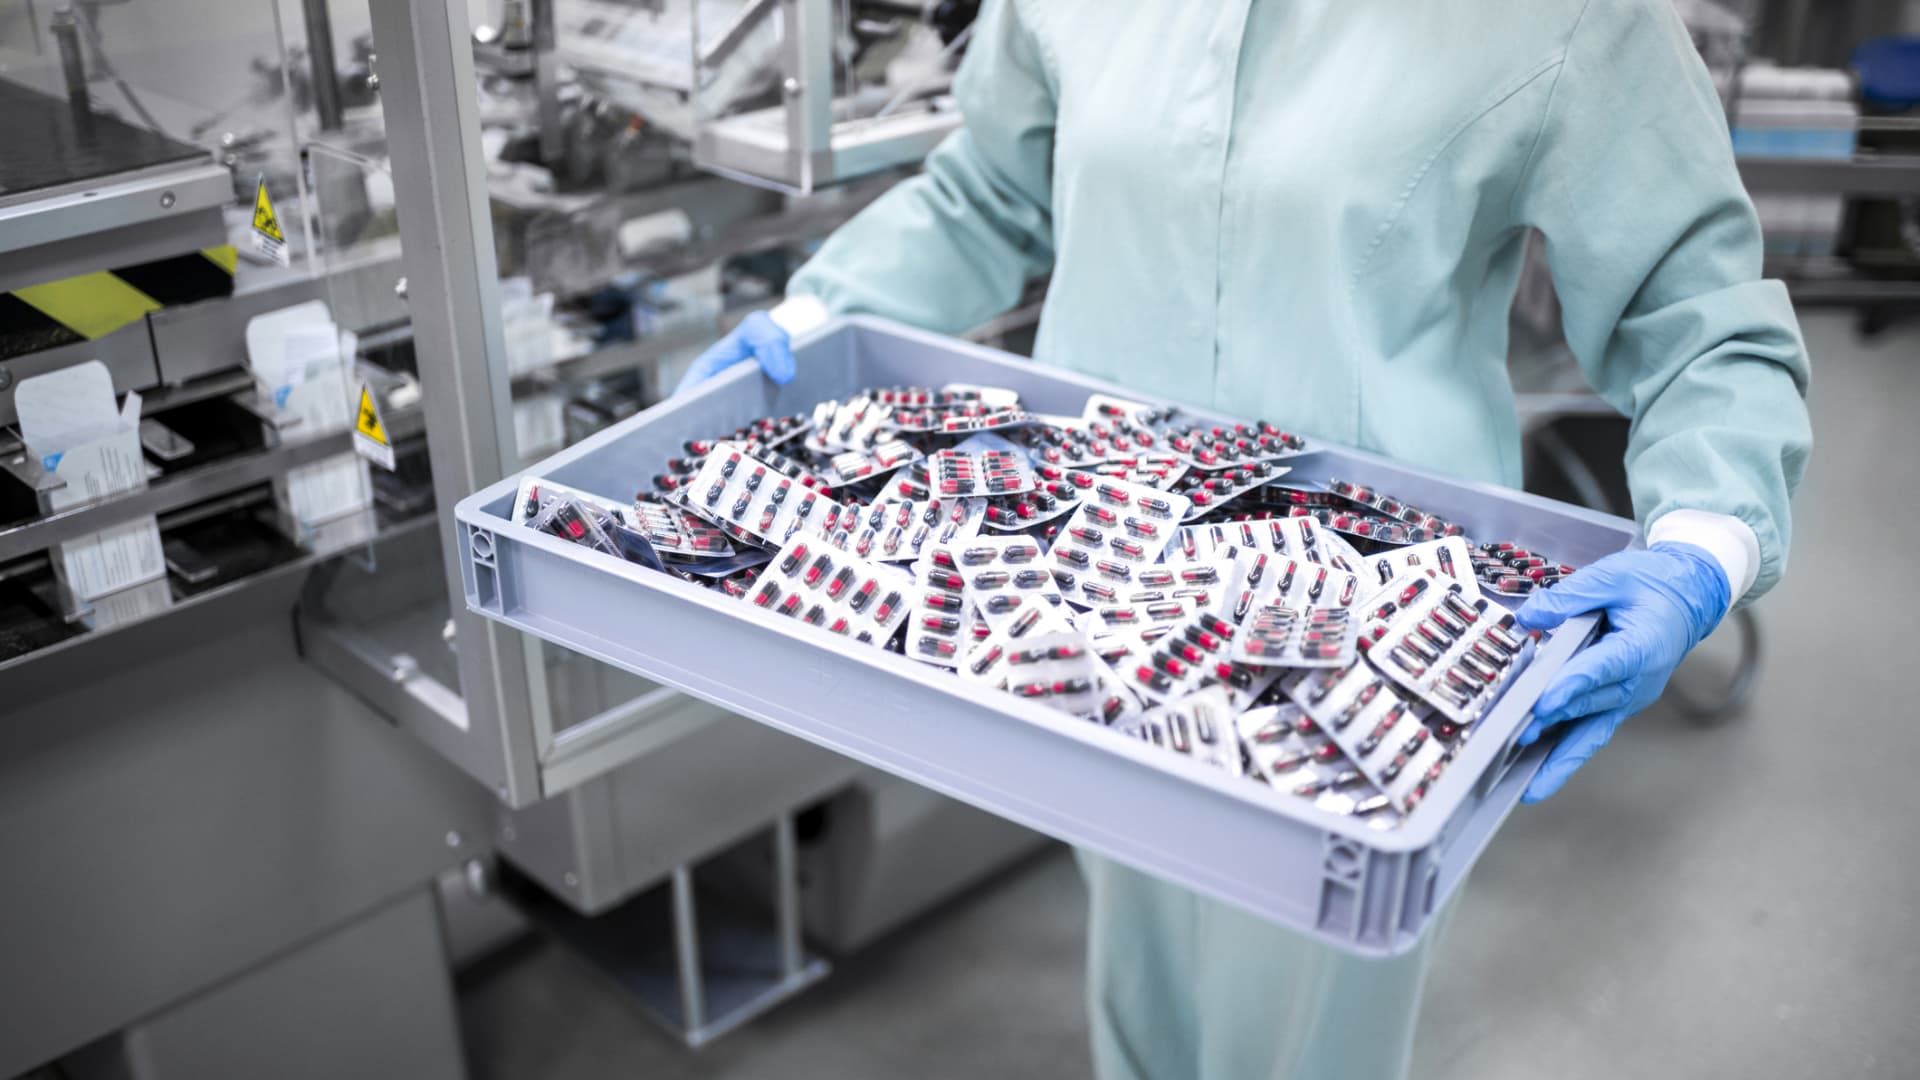
Optimistic Outlook for Sino-U.S. Pharmaceutical Cooperation
Hutchmed Licenses Drug Development Rights to GSK

HUTCHMED Enters Exclusive License Agreement with GSK for HMPL-A830
HUTCHMED Reports Positive SANOVO Trial Results for Lung Cancer Treatment
HUTCHMED's ATLED Receives Conditional Approval in China
HUTCHMED (China) Ltd is an investment holding company principally engaged in the manufacture and sale of pharmaceuticals. The Company operates its business through two segments. Oncology Immunology segment is engaged in the discovery, development and commercialization of targeted therapies and immunotherapies for the treatment of cancer and immunological diseases. Among it, research and development (R&D) includes research and development activities covering drug discovery, development, manufacturing and regulatory functions, out-licensing of in-house developed drugs, as well as administrative activities to support research and development operations, marketed products comprises the invoiced sales, marketing, manufacture and distribution of drugs developed from research and development activities. Other Ventures segment is engaged in the other commercial businesses which include the sales, marketing, manufacture and distribution of other prescription drugs and healthcare products. It operates in the Healthcare sector (PHARMACEUTICAL PREPARATIONS industry).
HUTCHMED (China) Ltd is a good buy right now, trading at $14.1 with a forward P/E of 18.08, indicating reasonable valuation compared to its growth potential. The recent licensing agreement with GSK could generate significant future revenue, which supports the bullish sentiment. However, the high P/E ratio of 1215.37 poses a risk if earnings do not meet expectations.
4 analysts cover HCM: 4 rate it Buy, 0 Hold and 0 Sell. The average price target is 22.00.
No posts yet
Sign up or log in to join the discussionThis page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.