
B
Bull
Bull · 25%HBM
$21.04
Scenario price
$23.600
+0.212 (+0.90%)At close
Hudbay Minerals Inc. is a copper-focused critical minerals company with three operations and a pipeline of copper growth projects in tier-one mining jurisdictions of Canada, Peru and the United States. Its operating portfolio includes the Constancia mine in Cusco (Peru), the Snow Lake operations in Manitoba (Canada) and the Copper Mountain mine in British Columbia (Canada). Its growth pipeline includes the Copper World project in Arizona (United States), the Cactus project in Arizona (United States), the Mason project in Nevada (United States), the Llaguen project in La Libertad (Peru) and several expansion and exploration opportunities near its existing operations. The Copper Mountain Mine, located south of Princeton, British Columbia, is a conventional open pit, truck and shovel operation. The Constancia mine is in the province of Chumbivilcas in southern Peru. Its primary production is copper, complemented by gold production and by-products, such as zinc, silver, and molybdenum.
Hudbay Minerals Inc is currently not a strong buy due to its low RSI of 19.397, indicating oversold conditions, and a recent 5-day price drop of 6.94%. However, the company has shown significant growth over the past year with a 41.81% increase in stock price, and hedge funds have increased their buying activity by 314.23% in the last quarter, suggesting potential for recovery. The main risk is the recent earnings miss with an EPS of $0.28 compared to an estimate of $0.30, which may affect investor sentiment in the short term.
Barclays
$46
2026-10-06
Barclays
2026-10-06
Price Target
$46
BMO Capital
$49
2026-09-29
BMO Capital
2026-09-29
Price Target
$49
Scotiabank
$43
2026-07-30
Scotiabank
2026-07-30
Price Target
$43
Stifel
$43
2026-07-21
Stifel
2026-07-21
Price Target
$43
Barclays
$32
2026-07-15
Barclays
2026-07-15
Price Target
$32
Scenario prices are the last monthly forecast band of the current year. Probabilities are fixed model weights (25 / 50 / 25), not guarantees.

Hudbay Approves Investment Decision for Copper World Project
Hudbay Minerals to Host Q3 2026 Results Conference Call

Honey Badger Silver Reports High-Grade Results from Yava Project
Copper Prices Hit Record High Amid Supply Shortages
Canadian Copper Stocks Plunge as Prices Revert from Record Highs
Hudbay Minerals Inc. is a copper-focused critical minerals company with three operations and a pipeline of copper growth projects in tier-one mining jurisdictions of Canada, Peru and the United States. Its operating portfolio includes the Constancia mine in Cusco (Peru), the Snow Lake operations in Manitoba (Canada) and the Copper Mountain mine in British Columbia (Canada). Its growth pipeline includes the Copper World project in Arizona (United States), the Cactus project in Arizona (United States), the Mason project in Nevada (United States), the Llaguen project in La Libertad (Peru) and several expansion and exploration opportunities near its existing operations. The Copper Mountain Mine, located south of Princeton, British Columbia, is a conventional open pit, truck and shovel operation. The Constancia mine is in the province of Chumbivilcas in southern Peru. Its primary production is copper, complemented by gold production and by-products, such as zinc, silver, and molybdenum. It operates in the Basic Materials sector.
Hudbay Minerals Inc is currently not a strong buy due to its low RSI of 19.397, indicating oversold conditions, and a recent 5-day price drop of 6.94%. However, the company has shown significant growth over the past year with a 41.81% increase in stock price, and hedge funds have increased their buying activity by 314.23% in the last quarter, suggesting potential for recovery. The main risk is the recent earnings miss with an EPS of $0.28 compared to an estimate of $0.30, which may affect investor sentiment in the short term.
6 analysts cover HBM: 6 rate it Buy, 0 Hold and 0 Sell. The average price target is 20.63.
#MicronHostsTechnicalWebinar Micron Technology's technical webinar, led by CTO Scott DeBoer, highlighted a key inflection point for the memory industry. The presentation focused on a roadmap spanning multiple product generations, including high-bandwidth memory (HBM), advanced DRAM, and NAND technologies designed for next-generation AI infrastructure. Here is what this signals for Micron and the broader memory market: Key Takeaways for the Memory Industry 1. Accelerating HBM Competition and Technology Roadmap * Next-Generation Transition: The emphasis on HBM innovation underscores that high-bandwidth memory has become the primary bottleneck and performance differentiator for AI accelerators. * Customer Co-Design: Micron's focus on directly co-designing hardware with major hyperscalers and GPU designers indicates a shift away from commoditized memory. Memory stacks tailored to specific server architectures are raising switching costs and strengthening customer stickiness. 2. Disciplined Capacity Planning * Capital Intensity and Oversupply: The market is scrutinizing Micron's capacity expansion. Higher HBM wafer consumption naturally absorbs DRAM capacity. * Tight DRAM Supply: By prioritizing advanced HBM nodes, industry-wide general-purpose DRAM capacity remains constrained, helping to support average selling prices in standard server and enterprise storage markets. 3. Focus on Power and Thermal Efficiency * Data Center Energy Constraints: Power limits in data centers make performance-per-watt a key metric for memory. Updates in advanced packaging, process nodes, and energy-efficient NAND/DRAM help address thermal constraints in ultra-high-density AI racks. 4. Competitive Positioning Relative to Peers * Market Share Dynamics: Micron continues to challenge incumbent leaders SK Hynix and Samsung in high-end HBM. Technical updates on yields, customer qualification, and roadmap execution will indicate whether Micron can maintain or expand its share in advanced memory. Broader Industry Implications High-Bandwidth Memory Transition Shift toward higher-margin, customized HBM products rather than commoditized DRAM. Supply Reduction / Wafer Allocation HBM production consumes roughly 3x the wafer capacity of standard DRAM, tightening global supply. AI Infrastructure Demand Expansion Enterprise storage and high-density DRAM demand extends from GPUs to servers. Potential Follow-Up Analysis For further exploration, consider analyzing: 1. Financial Impact: How the HBM revenue mix affects Micron's gross margins compared with traditional DRAM/NAND. 2. Competitive Comparison: A direct comparison of Micron's HBM roadmap with SK Hynix and Samsung. 3. Supply Chain Impact: How equipment suppliers (such as ASML or Applied Materials) benefit from HBM packaging capacity expansion. $HBM $DRAM $SKHY $SAMSUNG
Show more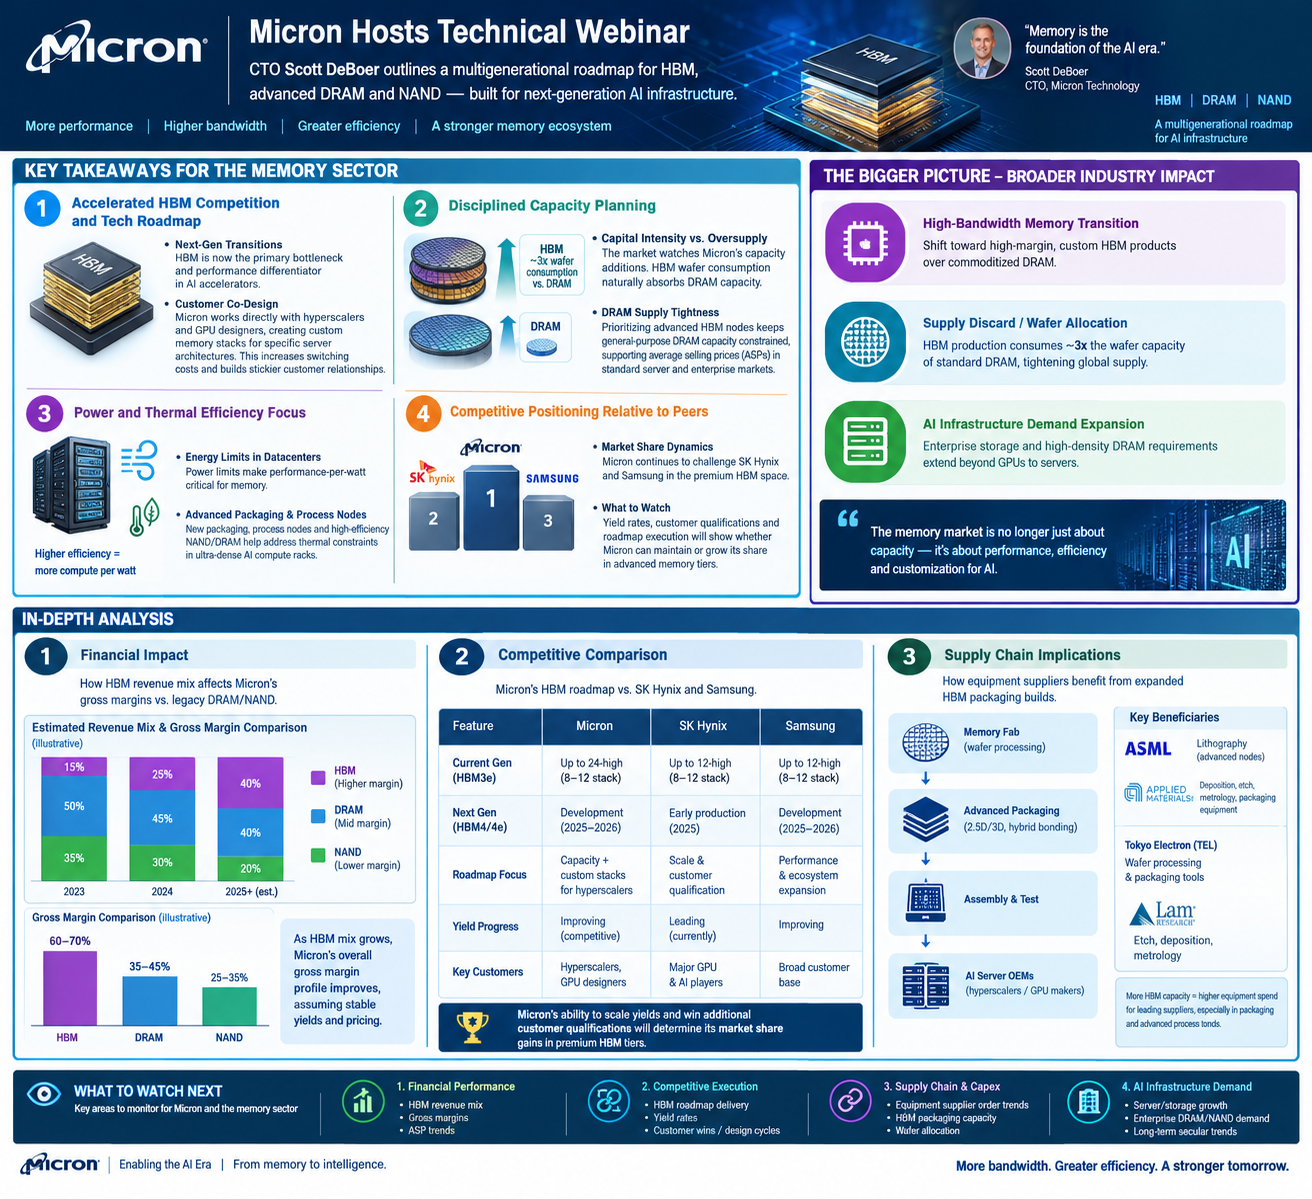
#SamsungQ3OperatingProfitSurges782.5% The disconnect between Samsung's record KRW 107.4 trillion profit (about $80.1 billion) and the negative market reaction reflects a typical Wall Street dynamic: concerns about a cyclical peak clashing with currently strong fundamental performance. Key points 1. AI-driven memory boom * High-bandwidth memory (HBM) and enterprise DRAM pricing continue to push up margins in the device solutions division. * The 55.1% operating margin reflects severe supply tightness in server DRAM and high-density NAND, and the historic pricing power that results. 2. Why are the stock price and KOSPI weakening? (the "good news priced in" trend) * Revenue missed expectations: although operating profit beat expectations (consensus was about KRW 105.7–106 trillion), total revenue of KRW 195 trillion came in below the market consensus of about KRW 206.8 trillion, indicating that revenue growth in non-memory businesses is slowing. * Diverging business performance: rising memory prices are directly squeezing profitability in Samsung's mobile and consumer electronics divisions. Higher bill of materials (BOM) costs, driven by internal chip procurement, are weighing on smartphone margins. * Cyclical peak concerns: as the market approaches late 2026/2027, it is pricing in a potential inventory digestion phase and expectations that margins at large data center companies may normalize. Strategic considerations for the memory bull case * HBM certification and shipments: the top focus of the full earnings call later this month will be the HBM supply share committed to key AI accelerator buyers, especially compared with SK Hynix. * Capital expenditure discipline: as enterprise AI infrastructure spending is readjusted, whether memory makers can maintain capital expenditure discipline, or whether they will face the risk of oversupply at DRAM nodes. $SAMSUNG $HBM $DRAM
Show more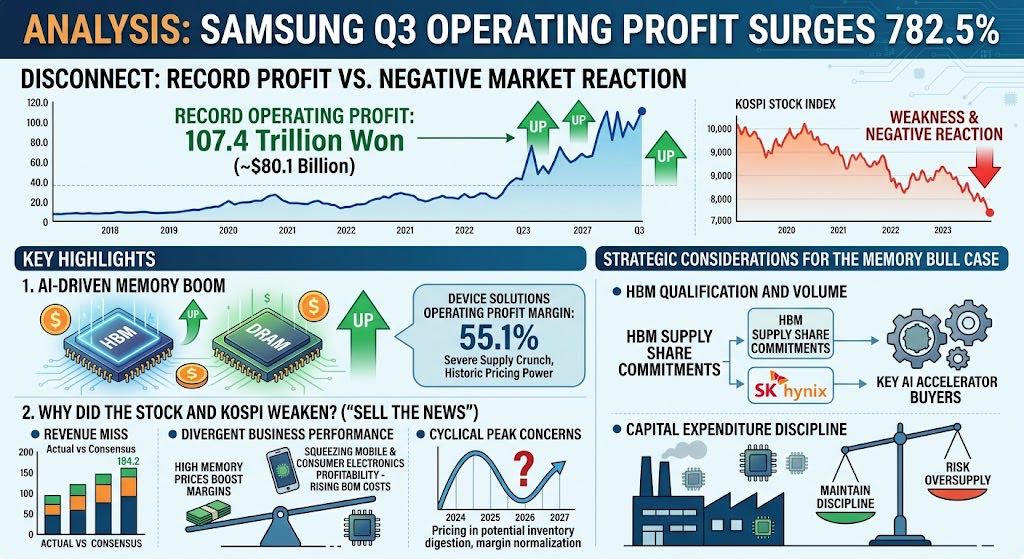
This page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.