
B
Bull
Bull · 25%GLRE
$12.57
Scenario price
$14.820
+0.080 (+0.54%)At close
Greenlight Capital Re, Ltd provides multiline property and casualty insurance and reinsurance through its licensed and regulated reinsurance entities in the Cayman Islands and Ireland, and its Lloyd’s platform, Greenlight Innovation Syndicate 3456. The Company’s segments include Open Market and Innovations. In the Open Market segment, the Company underwrites reinsurance business, sourced through the brokerage distribution channels and Lloyd’s. The Company writes treaty reinsurance on a proportional and non-proportional basis. Its lines of business include casualty, financial, health, multiline, property and specialty. In the Innovations segment, the Company provides reinsurance capacity to startup companies and managing general agents (MGAs) based globally, sourced mainly through direct placements with its strategic partners. This segment also includes business written by Syndicate 3456. Its lines of business include casualty, financial, health, multiline and specialty.
Currently, Greenlight Capital Re Ltd (GLRE) is not a strong buy. The stock is priced at $14.82, which is near its Fibonacci Pivot level of $14.802, indicating potential support. However, the recent RSI of 49.05 suggests it is neither overbought nor oversold, and the company reported a GAAP EPS of -0.89 for Q2 2026, indicating ongoing profitability challenges. Additionally, insider selling has increased by 110.82% over the last month, which raises concerns about insider confidence in the stock's future performance.
Scenario prices are the last monthly forecast band of the current year. Probabilities are fixed model weights (25 / 50 / 25), not guarantees.
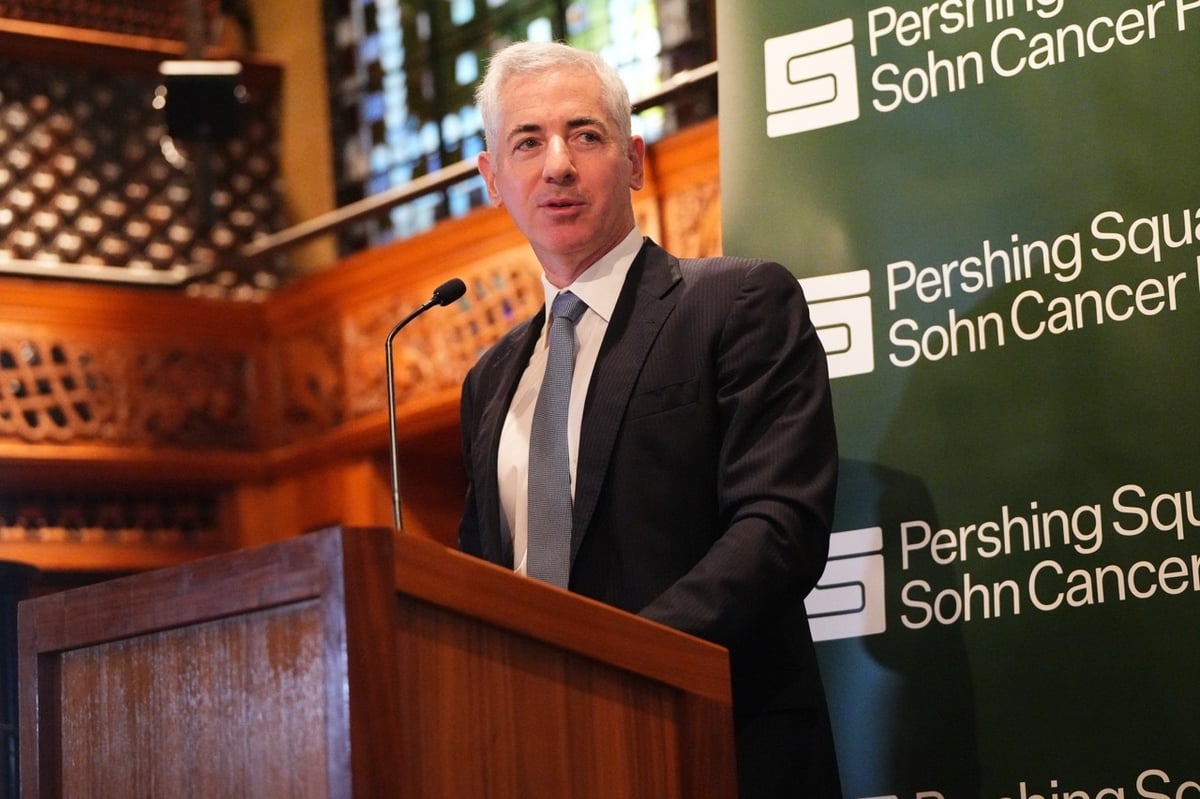
Ackman Emulates Buffett's Investment Strategy with Howard Hughes Holdings
Greenlight Capital Re (GLRE) Q2 2026 Earnings Call

Greenlight Capital Re Reports Q2 2026 Financial Results

Greenlight Capital Reports Q2 Financial Results
Greenlight Re's Syndicate 3456 Receives Lloyd's Full Syndicate Approval
Greenlight Capital Re, Ltd provides multiline property and casualty insurance and reinsurance through its licensed and regulated reinsurance entities in the Cayman Islands and Ireland, and its Lloyd’s platform, Greenlight Innovation Syndicate 3456. The Company’s segments include Open Market and Innovations. In the Open Market segment, the Company underwrites reinsurance business, sourced through the brokerage distribution channels and Lloyd’s. The Company writes treaty reinsurance on a proportional and non-proportional basis. Its lines of business include casualty, financial, health, multiline, property and specialty. In the Innovations segment, the Company provides reinsurance capacity to startup companies and managing general agents (MGAs) based globally, sourced mainly through direct placements with its strategic partners. This segment also includes business written by Syndicate 3456. Its lines of business include casualty, financial, health, multiline and specialty. It operates in the Financials sector (FIRE, MARINE & CASUALTY INSURANCE industry).
Currently, Greenlight Capital Re Ltd (GLRE) is not a strong buy. The stock is priced at $14.82, which is near its Fibonacci Pivot level of $14.802, indicating potential support. However, the recent RSI of 49.05 suggests it is neither overbought nor oversold, and the company reported a GAAP EPS of -0.89 for Q2 2026, indicating ongoing profitability challenges. Additionally, insider selling has increased by 110.82% over the last month, which raises concerns about insider confidence in the stock's future performance.
3 analysts cover GLRE: 2 rate it Buy, 1 Hold and 0 Sell.
No posts yet
Sign up or log in to join the discussionThis page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.