B
Bull
Bull · 25%FRO
$20.76
Scenario price
$52.490
-0.052 (-0.10%)At close
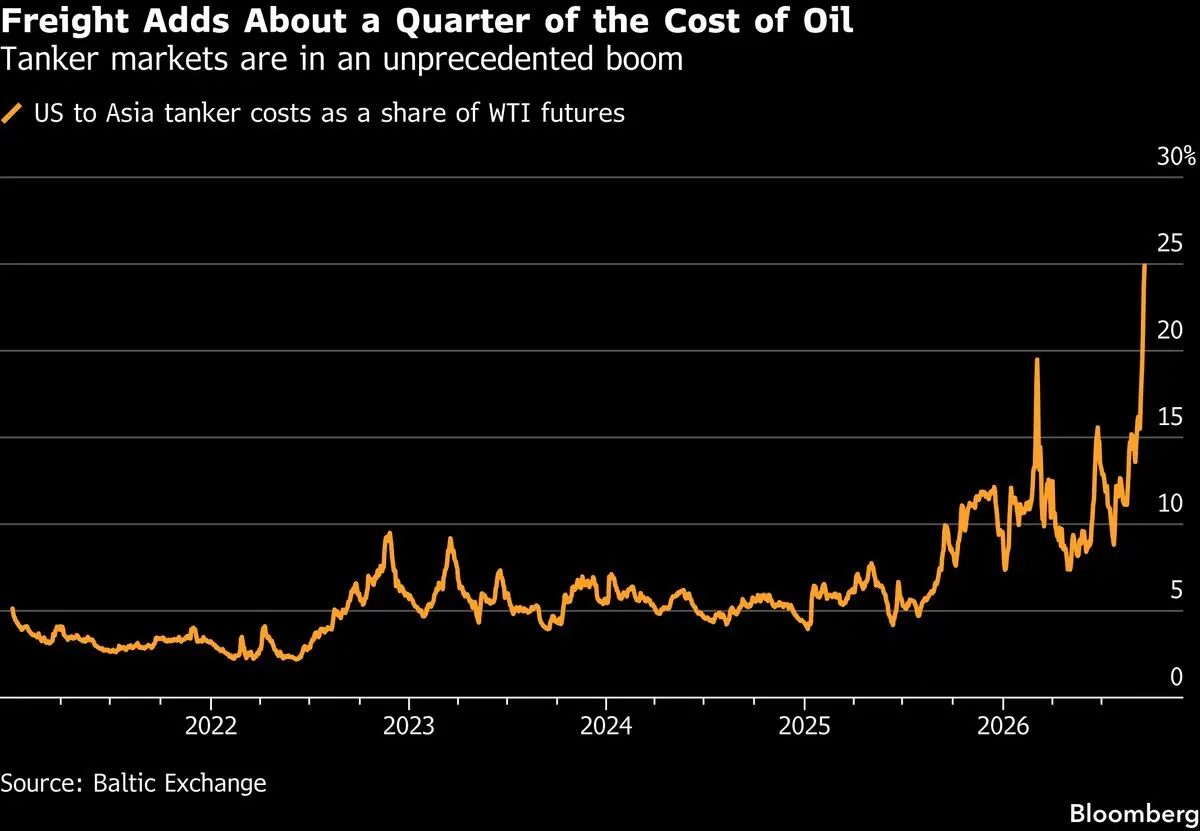
FRONTLINE PLC is a Cyprus-based company primarily operating in the transportation sector. The Company's main focus is on seaborne transportation of crude oil and refined products. The Company owns and operates a fleet consisting of multiple VLCC, Suezmax and LR2 / Aframax tankers intended for freight of oil and cargo. The Company operates worldwide.
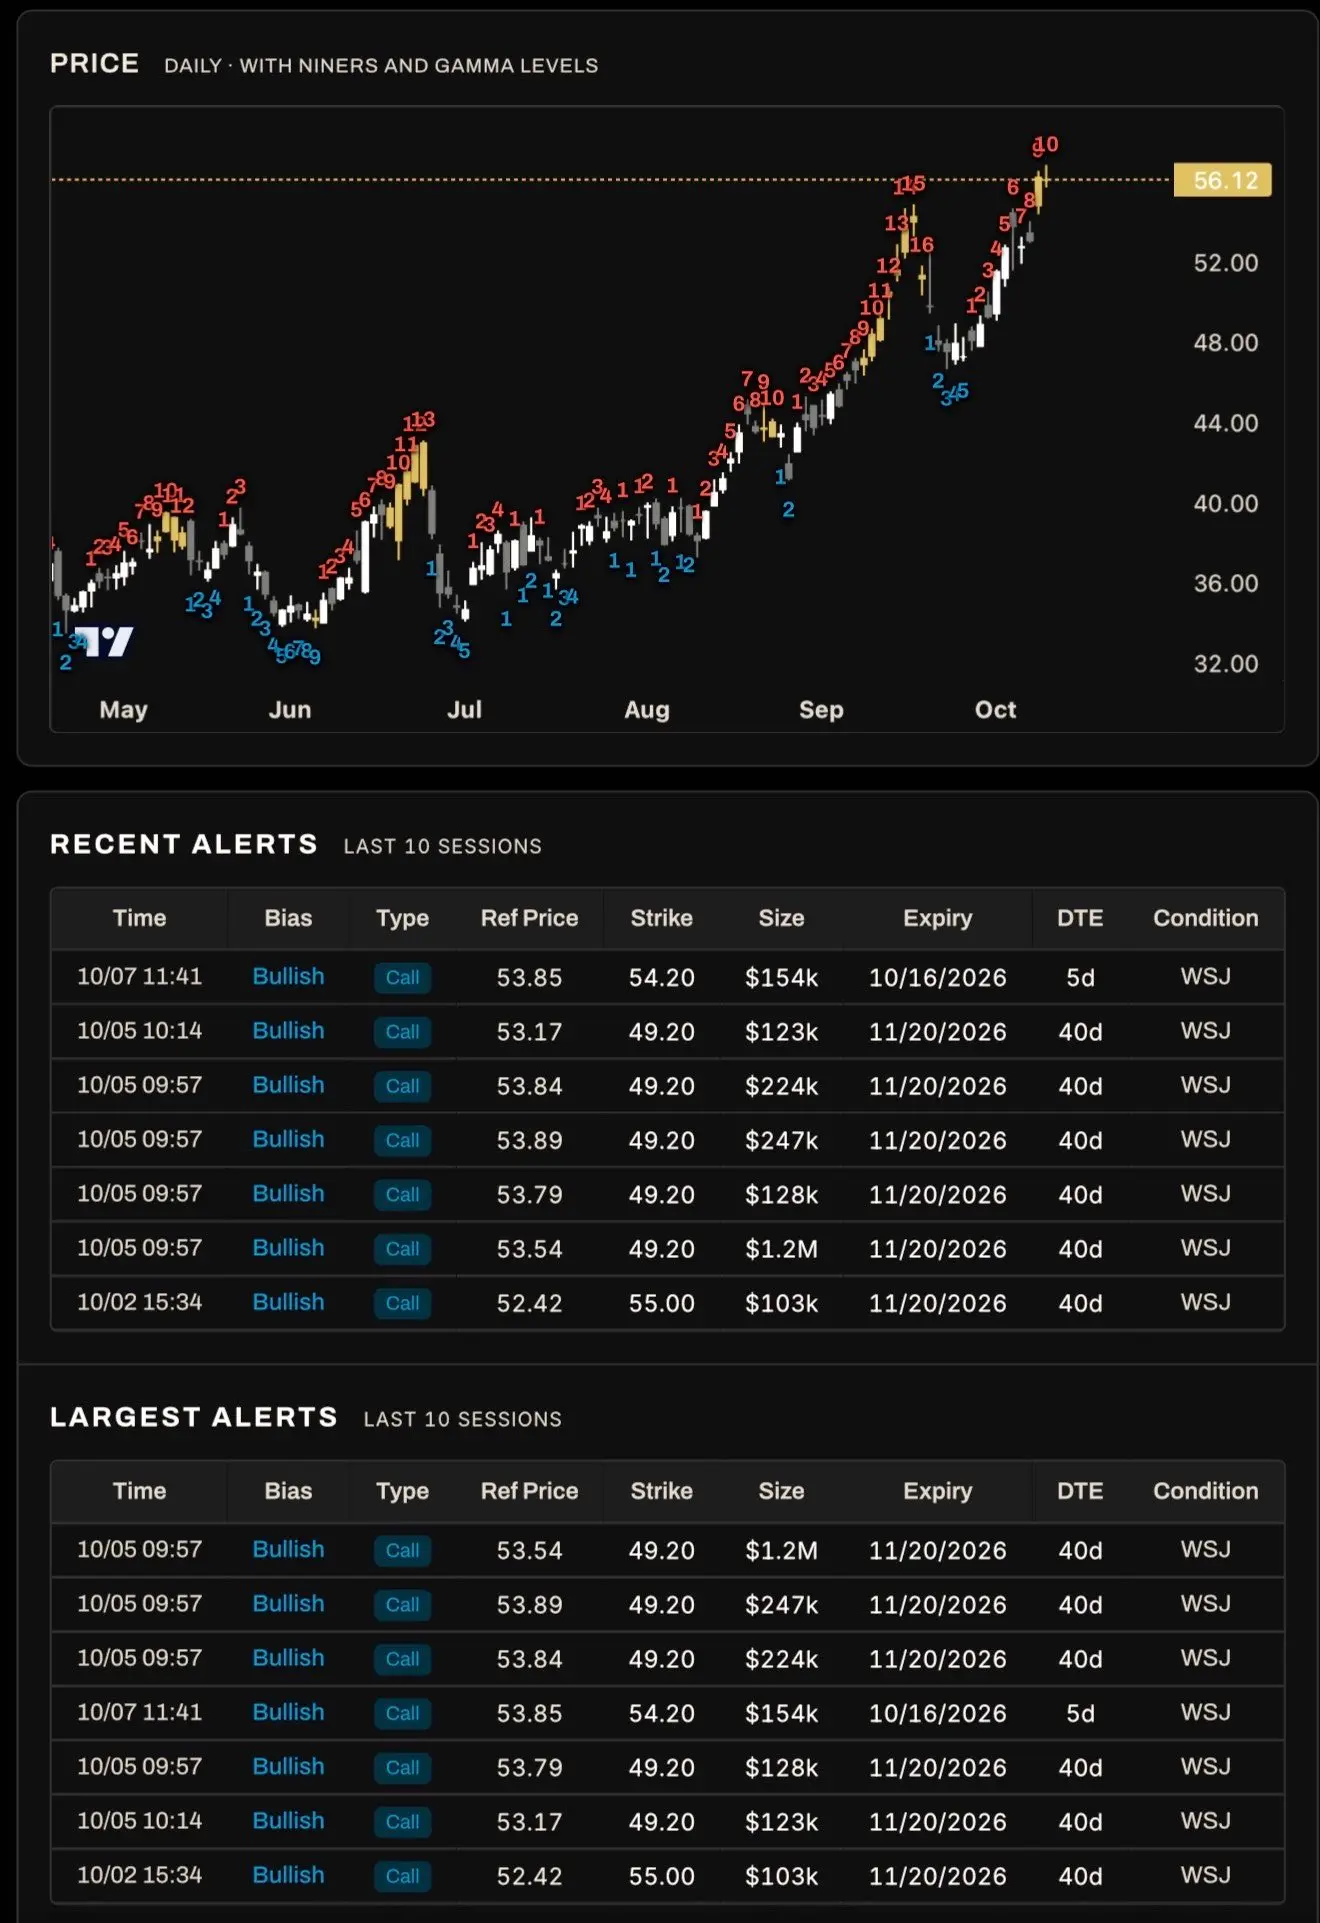
Frontline Plc is a strong buy right now due to its impressive financial performance, with a net income of $659 million in Q2 2026 and a gross margin of 64.52%. The stock is currently priced at $56.1, which is below the analyst target of $70, indicating significant upside potential. However, the main risk is the hedge fund selling activity, which has increased by 2312.52% over the last quarter, suggesting some market caution.
BTIG
$70
2026-09-18
BTIG
2026-09-18
Price Target
$70
Evercore ISI
$41
2026-08-31
Evercore ISI
2026-08-31
Price Target
$41
Nordea
—
2026-08-31
Nordea
2026-08-31
Price Target
—
Danske Bank
$39.15
2026-08-21
Danske Bank
2026-08-21
Price Target
$39.15
BTIG
$55
2026-06-24
BTIG
2026-06-24
Price Target
$55
Scenario prices are the last monthly forecast band of the current year. Probabilities are fixed model weights (25 / 50 / 25), not guarantees.
IEA Lowers 2026 Global Oil Demand Forecast Amid Market Disruptions

Global Oil Demand Forecast Downgraded
Strait of Hormuz Crisis Drives Shipping Stocks Surge
Frontline Reports Record Quarter Performance

Frontline Reports Record Quarterly Earnings
FRONTLINE PLC is a Cyprus-based company primarily operating in the transportation sector. The Company's main focus is on seaborne transportation of crude oil and refined products. The Company owns and operates a fleet consisting of multiple VLCC, Suezmax and LR2 / Aframax tankers intended for freight of oil and cargo. The Company operates worldwide. It operates in the Energy sector (DEEP SEA FOREIGN TRANSPORTATION OF FREIGHT industry).
Frontline Plc is a strong buy right now due to its impressive financial performance, with a net income of $659 million in Q2 2026 and a gross margin of 64.52%. The stock is currently priced at $56.1, which is below the analyst target of $70, indicating significant upside potential. However, the main risk is the hedge fund selling activity, which has increased by 2312.52% over the last quarter, suggesting some market caution.
5 analysts cover FRO: 1 rate it Buy, 3 Hold and 1 Sell. The average price target is 23.45.
This page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.