B
Bull
Bull · 25%CPAY
$414.86
Scenario price
$402.560
+2.737 (+0.68%)At close
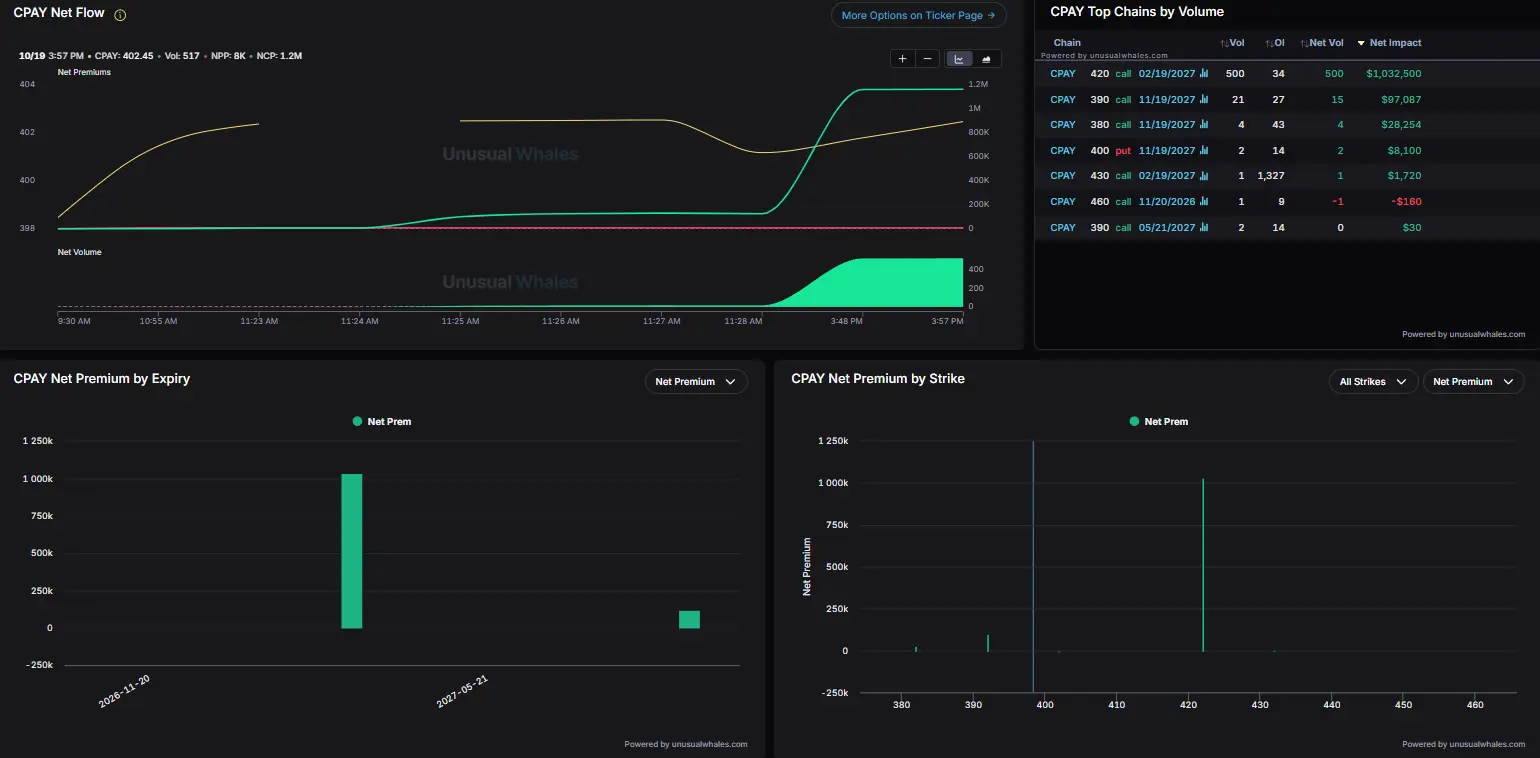
Corpay, Inc. is a corporate payments company. The Company provides a broad suite of payment and spend management solutions, including accounts payable automation and cross-border payment solutions, commercial card programs (purchasing cards, business cards and virtual cards), vehicle payment solutions (fuel cards, toll payments and related services) and lodging payment solutions. Its segments include Corporate Payments, Vehicle Payments, Lodging Payments and Other. Corporate Payments segment helps businesses streamline the management, processing and payment of their domestic and international invoices and make point-of-sale purchases for their employees. Vehicle Payments segment is purpose-built to enable its customers to pay for vehicle related expenses. Lodging Payments segment helps businesses manage and control their lodging costs, simplify the management of offerings from hotels and long-term housing arrangements. Other segments include its gift and payroll card businesses.
Corpay Inc (CPAY) is a strong buy right now, trading at $399.84 with a forward P/E of 12.77, indicating attractive valuation compared to future earnings. The company has shown impressive revenue growth, with Q2 2026 revenue reaching $1.34 billion, a 21% increase year-over-year, and cash EPS hitting $7, up 36% year-over-year. The main risk is the recent $100 million FTC settlement, which caused a slight stock price drop of 1.15%, but the company does not expect this to materially affect operations.
Scenario prices are the last monthly forecast band of the current year. Probabilities are fixed model weights (25 / 50 / 25), not guarantees.
Corpay Extends FX Payments Agreement with WBSC
Corpay Expands AI Agent Team to Enhance Spend Management
Corpay to Settle FTC Allegations for $100 Million
Corpay Reaches $100 Million Settlement with FTC
Corpay to Participate in Investor Conferences
Corpay, Inc. is a corporate payments company. The Company provides a broad suite of payment and spend management solutions, including accounts payable automation and cross-border payment solutions, commercial card programs (purchasing cards, business cards and virtual cards), vehicle payment solutions (fuel cards, toll payments and related services) and lodging payment solutions. Its segments include Corporate Payments, Vehicle Payments, Lodging Payments and Other. Corporate Payments segment helps businesses streamline the management, processing and payment of their domestic and international invoices and make point-of-sale purchases for their employees. Vehicle Payments segment is purpose-built to enable its customers to pay for vehicle related expenses. Lodging Payments segment helps businesses manage and control their lodging costs, simplify the management of offerings from hotels and long-term housing arrangements. Other segments include its gift and payroll card businesses. It operates in the Industrials sector (BUSINESS SERVICES, NOT ELSEWHERE CLASSIFIED industry).
Corpay Inc (CPAY) is a strong buy right now, trading at $399.84 with a forward P/E of 12.77, indicating attractive valuation compared to future earnings. The company has shown impressive revenue growth, with Q2 2026 revenue reaching $1.34 billion, a 21% increase year-over-year, and cash EPS hitting $7, up 36% year-over-year. The main risk is the recent $100 million FTC settlement, which caused a slight stock price drop of 1.15%, but the company does not expect this to materially affect operations.
This page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.