A
ARK Investment Management LLC
+ HoldingCBRS
+18.96%
3M Return
$108.370
-2.395 (-2.21%)At close
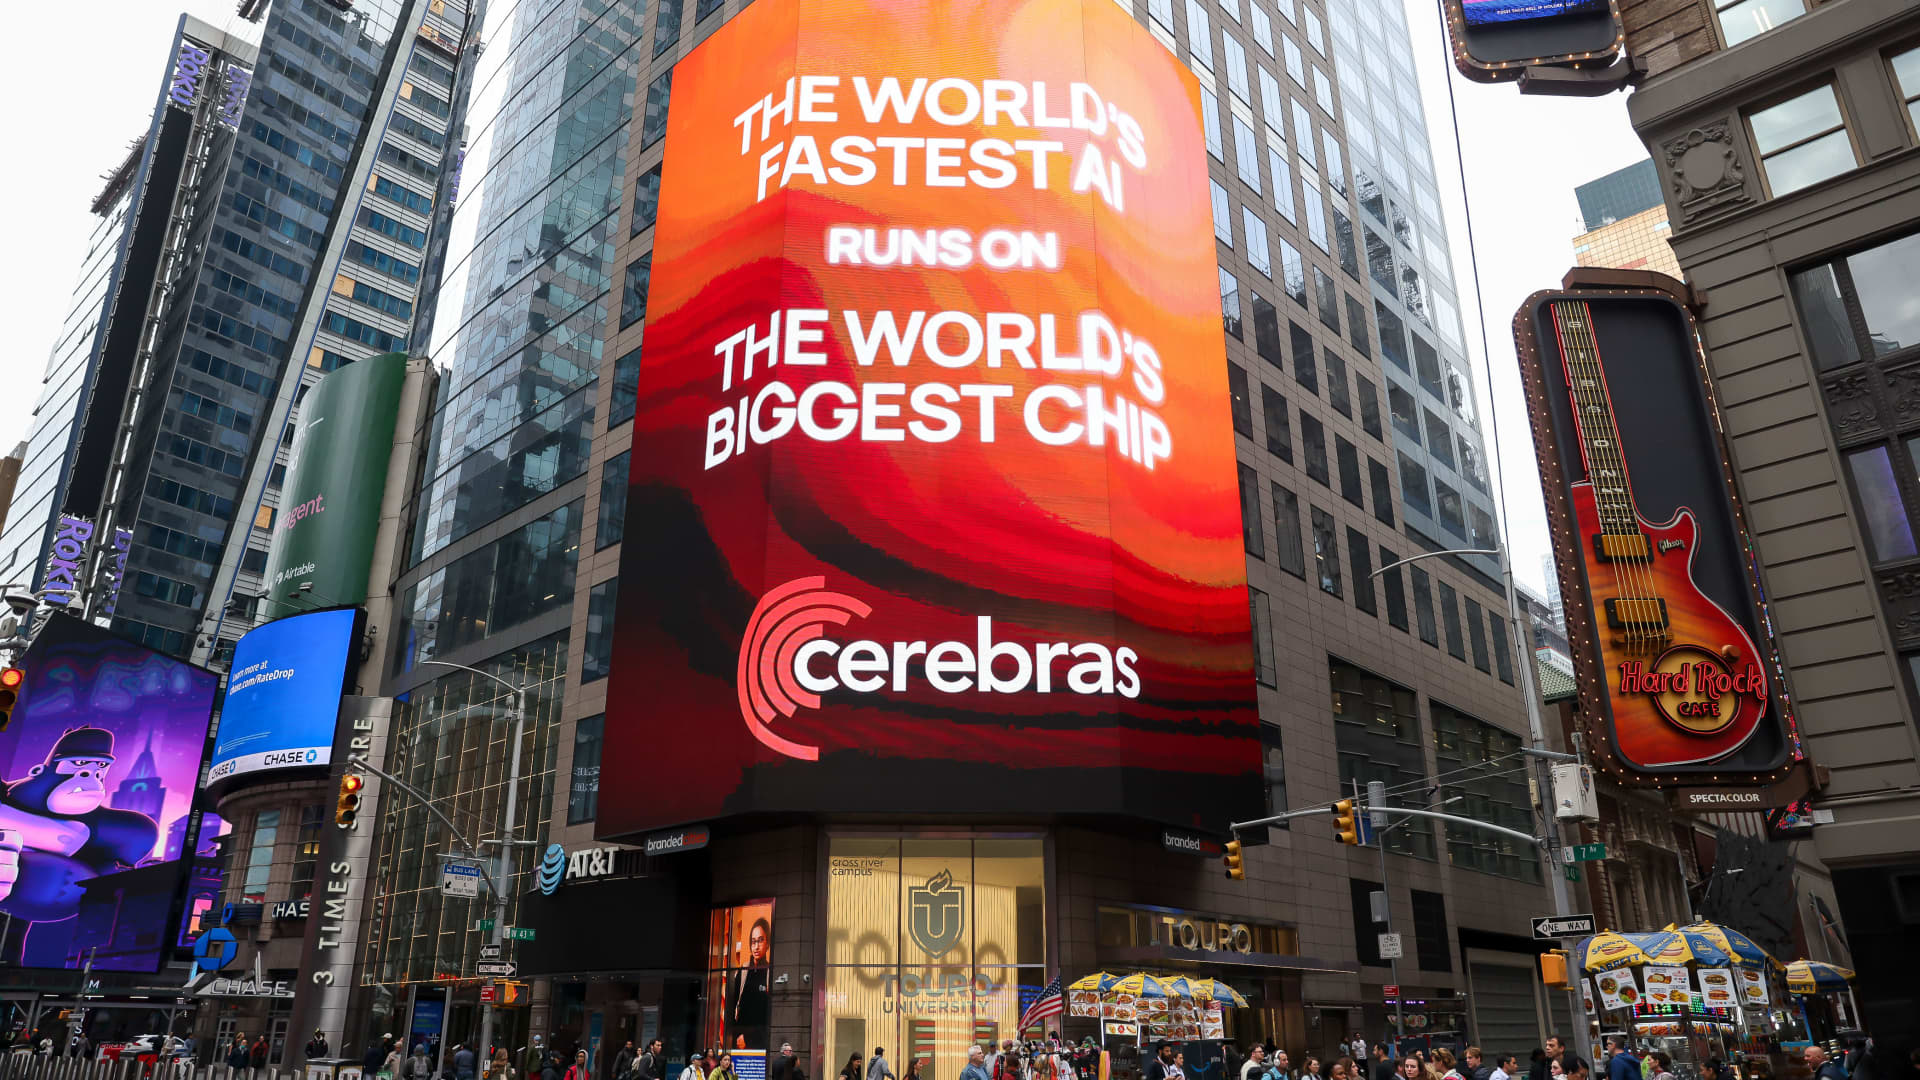
Cerebras Systems Inc. is an artificial intelligence (AI) infrastructure company that designs and manufactures an AI compute platform comprised of proprietary systems and software. The Company's products include inference Cloud, Training Cloud, CS-3 system, AI supercomputer, Wafer Scale Engine and model development. The Company's pioneering Wafer-Scale Engine (WSE), a chip encompassing an entire silicon wafer, was specifically designed to enable higher performance and speeds than GPUs for the computational demands of inference, Generative AI (GenAI), and other AI applications. It offers deployment services to assist customers with data preparation, model architecture design, training management, inference optimization, and, in select cases, ongoing system operations and management. It also offers a subscription service providing access to an ongoing stream of software updates and upgrades for purchasers of its hardware.
Cerebras Systems Inc. is a good buy right now due to its current price of $110.82, which is significantly lower than the analyst price targets ranging from $209 to $320, indicating potential upside of approximately 91% to 189%. Additionally, the company has a strong growth trajectory, with core cloud revenue having grown 287% year-over-year in Q2 2026. However, investors should be aware of the risk of a high forward P/E ratio of 217.39, indicating that the stock may be overvalued if growth does not materialize as expected.
Cerebras and Marvell's AI Strategies Compared
AI Drives Growth in Semiconductor Industry
Investment Opportunity in Cerebras Amid Stock Decline
Harvard's Investment Strategy: A Deep Dive into Top Holdings

Surge in Trading Volume of Tokenized Assets
Cerebras Systems Inc. is an artificial intelligence (AI) infrastructure company that designs and manufactures an AI compute platform comprised of proprietary systems and software. The Company's products include inference Cloud, Training Cloud, CS-3 system, AI supercomputer, Wafer Scale Engine and model development. The Company's pioneering Wafer-Scale Engine (WSE), a chip encompassing an entire silicon wafer, was specifically designed to enable higher performance and speeds than GPUs for the computational demands of inference, Generative AI (GenAI), and other AI applications. It offers deployment services to assist customers with data preparation, model architecture design, training management, inference optimization, and, in select cases, ongoing system operations and management. It also offers a subscription service providing access to an ongoing stream of software updates and upgrades for purchasers of its hardware. It operates in the Technology sector.
Cerebras Systems Inc. is a good buy right now due to its current price of $110.82, which is significantly lower than the analyst price targets ranging from $209 to $320, indicating potential upside of approximately 91% to 189%. Additionally, the company has a strong growth trajectory, with core cloud revenue having grown 287% year-over-year in Q2 2026. However, investors should be aware of the risk of a high forward P/E ratio of 217.39, indicating that the stock may be overvalued if growth does not materialize as expected.
This page is for research only and is not investment advice. Models can be wrong. Past performance does not guarantee future results.