
強
強気
強気 · 25%HBM
$21.04
シナリオ価格
$24.240
-1.360 (-5.61%)終値時点
Hudbay Minerals Inc. is a copper-focused critical minerals company with three operations and a pipeline of copper growth projects in tier-one mining jurisdictions of Canada, Peru and the United States. Its operating portfolio includes the Constancia mine in Cusco (Peru), the Snow Lake operations in Manitoba (Canada) and the Copper Mountain mine in British Columbia (Canada). Its growth pipeline includes the Copper World project in Arizona (United States), the Cactus project in Arizona (United States), the Mason project in Nevada (United States), the Llaguen project in La Libertad (Peru) and several expansion and exploration opportunities near its existing operations. The Copper Mountain Mine, located south of Princeton, British Columbia, is a conventional open pit, truck and shovel operation. The Constancia mine is in the province of Chumbivilcas in southern Peru. Its primary production is copper, complemented by gold production and by-products, such as zinc, silver, and molybdenum.
Hudbay Minerals Inc is a good buy right now, primarily driven by a current price of $26.12, a forward P/E ratio of 15.27, and a significant year-to-date change of +29.95%. The company has shown strong earnings growth with a net income of $190.4 million in Q1 2026, reflecting robust profitability. However, a key risk is the recent decline in copper prices, which fell 3.1% to $14,312 per metric ton, impacting market sentiment.
Barclays
$46
2026-10-06
Barclays
2026-10-06
目標株価
$46
BMO Capital
$49
2026-09-29
BMO Capital
2026-09-29
目標株価
$49
Scotiabank
$43
2026-07-30
Scotiabank
2026-07-30
目標株価
$43
Stifel
$43
2026-07-21
Stifel
2026-07-21
目標株価
$43
Barclays
$32
2026-07-15
Barclays
2026-07-15
目標株価
$32
シナリオ価格は本年の最終月次予想レンジです。確率はモデルの固定ウェイト(25 / 50 / 25)であり、保証ではありません。

Honey Badger Silver Reports High-Grade Results from Yava Project
Copper Prices Hit Record High Amid Supply Shortages
Canadian Copper Stocks Plunge as Prices Revert from Record Highs

Hudbay Minerals Recognized as 2026 TSX30™ Winner
Hudbay Minerals Files Early Warning Report on Panoro Holdings
Hudbay Minerals Inc. is a copper-focused critical minerals company with three operations and a pipeline of copper growth projects in tier-one mining jurisdictions of Canada, Peru and the United States. Its operating portfolio includes the Constancia mine in Cusco (Peru), the Snow Lake operations in Manitoba (Canada) and the Copper Mountain mine in British Columbia (Canada). Its growth pipeline includes the Copper World project in Arizona (United States), the Cactus project in Arizona (United States), the Mason project in Nevada (United States), the Llaguen project in La Libertad (Peru) and several expansion and exploration opportunities near its existing operations. The Copper Mountain Mine, located south of Princeton, British Columbia, is a conventional open pit, truck and shovel operation. The Constancia mine is in the province of Chumbivilcas in southern Peru. Its primary production is copper, complemented by gold production and by-products, such as zinc, silver, and molybdenum. It operates in the Basic Materials sector.
Hudbay Minerals Inc is a good buy right now, primarily driven by a current price of $26.12, a forward P/E ratio of 15.27, and a significant year-to-date change of +29.95%. The company has shown strong earnings growth with a net income of $190.4 million in Q1 2026, reflecting robust profitability. However, a key risk is the recent decline in copper prices, which fell 3.1% to $14,312 per metric ton, impacting market sentiment.
6 analysts cover HBM: 6 rate it Buy, 0 Hold and 0 Sell. The average price target is 20.63.
#SamsungQ3OperatingProfitSurges782.5% The disconnect between Samsung's record KRW 107.4 trillion profit (about $80.1 billion) and the negative market reaction reflects a typical Wall Street dynamic: concerns about a cyclical peak clashing with currently strong fundamental performance. Key points 1. AI-driven memory boom * High-bandwidth memory (HBM) and enterprise DRAM pricing continue to push up margins in the device solutions division. * The 55.1% operating margin reflects severe supply tightness in server DRAM and high-density NAND, and the historic pricing power that results. 2. Why are the stock price and KOSPI weakening? (the "good news priced in" trend) * Revenue missed expectations: although operating profit beat expectations (consensus was about KRW 105.7–106 trillion), total revenue of KRW 195 trillion came in below the market consensus of about KRW 206.8 trillion, indicating that revenue growth in non-memory businesses is slowing. * Diverging business performance: rising memory prices are directly squeezing profitability in Samsung's mobile and consumer electronics divisions. Higher bill of materials (BOM) costs, driven by internal chip procurement, are weighing on smartphone margins. * Cyclical peak concerns: as the market approaches late 2026/2027, it is pricing in a potential inventory digestion phase and expectations that margins at large data center companies may normalize. Strategic considerations for the memory bull case * HBM certification and shipments: the top focus of the full earnings call later this month will be the HBM supply share committed to key AI accelerator buyers, especially compared with SK Hynix. * Capital expenditure discipline: as enterprise AI infrastructure spending is readjusted, whether memory makers can maintain capital expenditure discipline, or whether they will face the risk of oversupply at DRAM nodes. $SAMSUNG $HBM $DRAM
もっと見る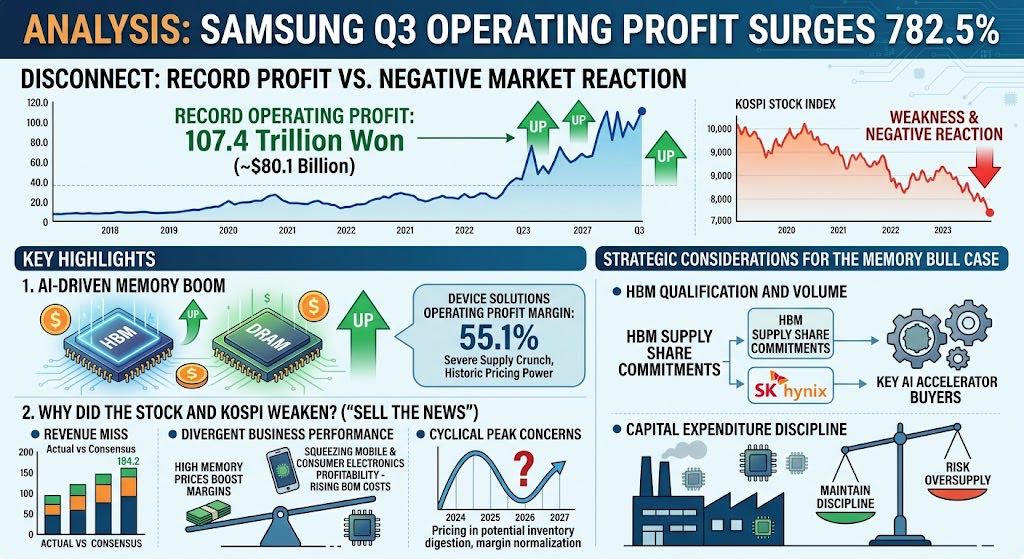
本ページは調査目的であり、投資助言ではありません。モデルは誤ることがあります。過去の実績は将来の成果を保証しません。