

AI Spending Fears Rattle Wall Street: Inside the Tech Selloff of October 2026
Wall Street is shaken as AI spending concerns trigger a massive tech selloff. Learn how Meta, Nvidia, and Microsoft capex is reshaping markets and what investors should watch.

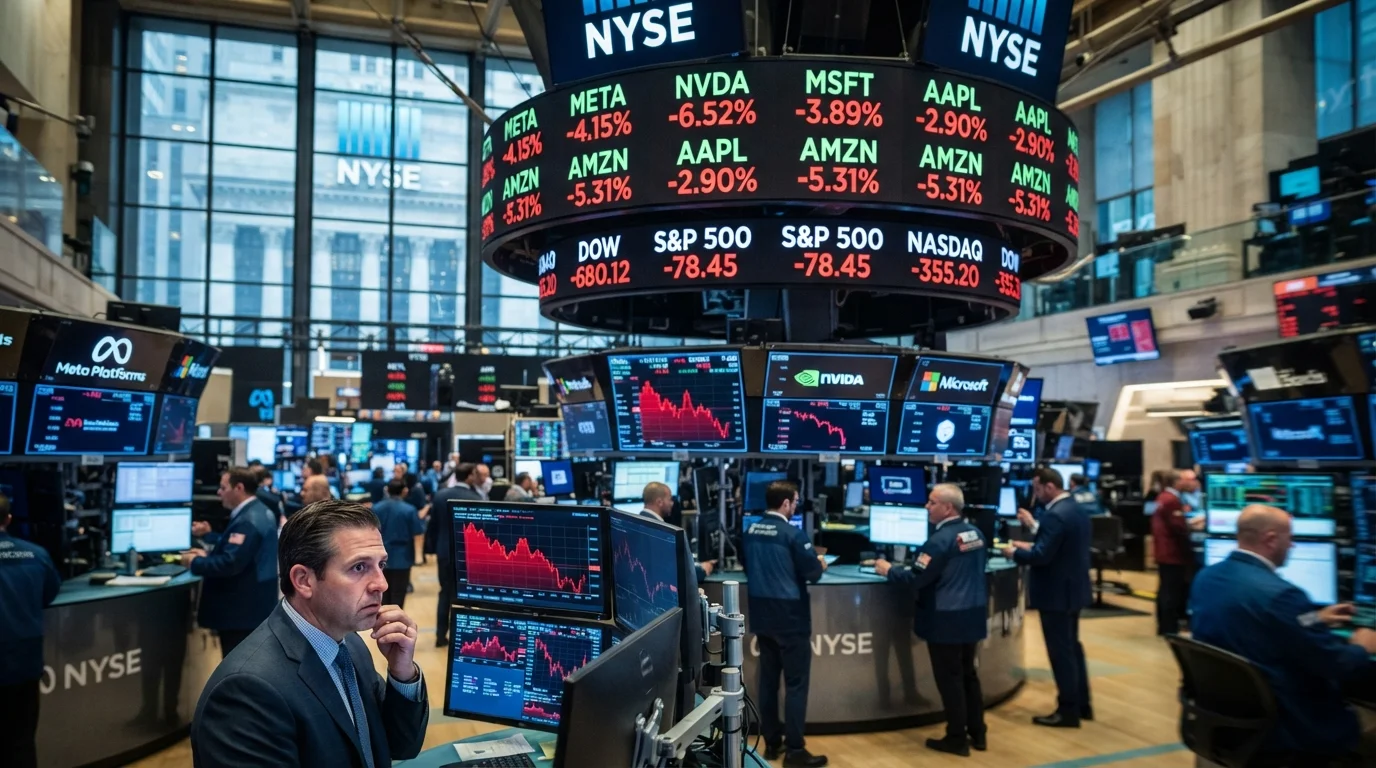
Key Takeaway
October 2026 has delivered a sobering reminder that even the most powerful market narratives can face reality checks. Wall Street's technology sector experienced its sharpest selloff in months as investors confronted an uncomfortable question: are the hundreds of billions being poured into artificial intelligence infrastructure actually generating returns, or are we witnessing one of the largest capital misallocations in corporate history?
The numbers are staggering. Meta Platforms raised its 2026 capital expenditure guidance to between $135 billion and $145 billion, while Amazon is projected to spend approximately $220 billion on AI infrastructure this year alone. When combined with Microsoft, Alphabet, and others, Big Tech's collective AI spending is approaching $735 billion annually, a figure that exceeds the GDP of many developed nations. The Nasdaq Composite plunged 2.6% on October 23, its steepest single-day decline since June, as this spending reality collided with growing skepticism about near-term profitability.
For investors, this moment represents more than a routine correction. It forces a fundamental reassessment of how technology valuations should be calculated when the companies driving them are spending unprecedented sums with payback timelines measured in years rather than quarters. The divergence between strong revenue growth and deteriorating free cash flow has become too pronounced to ignore.
The Scale of Big Tech's AI Investment Boom
Understanding the magnitude of current AI spending requires placing it in historical context. The $735 billion that major technology companies are collectively investing in AI infrastructure during 2026 represents approximately a 40% increase from 2025 levels. To put this in perspective, this annual expenditure exceeds the entire market capitalization of companies like JPMorgan Chase or Walmart.
Amazon leads the pack with projected spending of roughly $220 billion, driven primarily by data center expansion and custom chip development for its AWS cloud platform. Microsoft's capital expenditures, including finance leases, are estimated at approximately $175 billion, reflecting massive investments in Azure AI infrastructure and its partnership with OpenAI. Meta Platforms has emerged as perhaps the most aggressive spender relative to its size, with capex guidance of $135 billion to $145 billion representing a staggering increase from the $19.4 billion it spent in the third quarter of 2025.
Why the Spending Keeps Accelerating
The competitive dynamics driving this spending spiral are genuinely unprecedented. Each major technology company faces a prisoner's dilemma: no participant can afford to reduce investment without risking permanent competitive disadvantage. Meta's CEO Mark Zuckerberg has been particularly explicit about this calculus, framing AI investment as existential to the company's future. The company warned investors that its long-term plans could require raising hundreds of billions of dollars over several years beginning as early as fall 2026.
Cloud providers face similar pressures. Amazon Web Services, Microsoft Azure, and Google Cloud Platform are engaged in an arms race to offer the most capable AI infrastructure to enterprise customers. The transition from general-purpose cloud computing to AI-optimized infrastructure requires entirely new data center architectures, custom silicon, and power delivery systems capable of handling the enormous energy demands of modern AI training clusters.
The strategic logic behind this spending is not without merit. Companies that successfully develop superior AI capabilities may capture disproportionate market share in what could become a multi-trillion dollar market. However, the timeline between investment and returns has stretched far longer than initially anticipated, and the capital intensity required has exceeded even the most optimistic projections from just two years ago.
Meta's $145 Billion Bet: A Case Study in AI Capital Intensity
Meta Platforms' third-quarter 2026 earnings report, released on October 21, provides perhaps the clearest window into how AI spending is transforming corporate financials. The company reported revenue of $64.6 billion, representing impressive 26% year-over-year growth that exceeded consensus estimates of $63.4 billion. However, this strong top-line performance was overshadowed by capital expenditures of $34.9 billion during the quarter alone, compared to $19.4 billion in the same period last year.
The critical development that rattled investors was Meta's disclosure of $825 billion in future commitments, primarily related to AI infrastructure. This figure, which includes obligations for data centers, networking equipment, and energy infrastructure, represents approximately 1.4 times Meta's current market capitalization. The company raised the lower end of its full-year 2026 capex guidance from $130 billion to $135 billion while maintaining the upper bound at $145 billion.
The Cash Flow Crunch
Perhaps most concerning for investors was the fact that Meta's quarterly capital expenditures of $34.9 billion actually exceeded its operating cash flow for the period. This marks a critical inflection point where the company's core business is no longer generating sufficient cash to fund its growth investments. Meta will need to either reduce spending, issue debt, or dilute shareholders through equity offerings to maintain its current investment trajectory.
The market's reaction was swift and severe. Meta's stock dropped nearly 7% following the earnings announcement, wiping out approximately $90 billion in market value in a single session. Analysts who had previously defended the company's AI spending began revising their models to account for the deteriorating free cash flow trajectory. The question is no longer whether Meta's AI investments will eventually pay off, but whether the company can survive the cash burn required to reach that promised land.
For investors seeking to track how major technology companies are managing their capital allocation during this transformative period, tools like Alphio AI's autonomous trading platform can help automate portfolio adjustments based on shifting fundamentals.

Nvidia and the AI Hardware Supply Chain Under Pressure
Nvidia, which has been the primary beneficiary of the AI infrastructure buildout, has not been immune to the broader tech selloff. The company's stock declined 4.4% during the October 23 session, reflecting growing concerns that the sustainability of AI chip demand may be more questionable than previously assumed.
Despite reporting fiscal year 2026 revenue of $215.94 billion, a remarkable 65.47% increase from the prior year's $130.50 billion, Nvidia faces an increasingly complex demand environment. The company's data center revenue, which accounts for the vast majority of its sales, depends on continued aggressive purchasing from the very same hyperscalers that are now facing investor scrutiny over their spending levels.
The Neocloud Challenge
An emerging concern centers on the neocloud providers, companies like CoreWeave and Lambda that rent GPU clusters to startups and enterprises. These companies have been among Nvidia's most aggressive customers, but they are now facing their own funding challenges as venture capital flows slow and debt markets become less accommodating. Nvidia's role as a financier to this ecosystem, through deals where it effectively prepays for capacity, is facing its first major test.
The company's CEO Jensen Huang has maintained that AI cloud demand remains off the charts, and Nvidia continues to expand its supplier base to meet what it describes as insatiable demand. However, market participants are increasingly focused on the difference between demand for AI compute and demand that can be profitably monetized. The gap between these two concepts may be far wider than Nvidia's valuation currently assumes.
Microsoft and Amazon: The Cloud Giants' AI Spending Race
While Meta's spending has captured headlines due to its dramatic increase, Microsoft and Amazon represent the largest absolute contributors to Big Tech's AI capex surge. Microsoft's Azure platform has become the backbone of enterprise AI adoption, hosting OpenAI's models alongside its own Copilot offerings across Office, Windows, and developer tools.
Microsoft's fiscal 2026 capital expenditures, including finance leases, are estimated at approximately $175 billion. This figure actually represents a slight decrease from earlier projections of around $190 billion, though this reduction is attributed to a lease accounting change rather than any meaningful pullback in actual investment. The company is building data centers at an unprecedented pace, with construction projects spanning multiple continents.
Amazon's $220 Billion Infrastructure Buildout
Amazon's projected $220 billion in AI-related capital expenditures for 2026 makes it the single largest spender in the technology sector. The majority of this investment flows into AWS data center expansion, custom chip development including its Trainium and Inferentia processors, and networking infrastructure required to connect massive AI training clusters.
Amazon's spending strategy differs somewhat from its peers in its emphasis on vertical integration. By developing its own AI chips, Amazon aims to reduce its dependence on Nvidia while potentially offering customers lower-cost alternatives for inference workloads. However, this strategy requires enormous upfront investment in silicon design teams, fabrication partnerships, and software ecosystems.
Citi's recent forecast that Amazon, Microsoft, Alphabet, and Meta will spend a cumulative $5.35 trillion on capital expenditures through 2030, a sum exceeding Apple's current market capitalization, underscores just how extraordinary this investment cycle has become.
Market Implications: Is the AI Bubble Deflating?
The October 2026 tech selloff has reignited a debate that has simmered beneath the surface of the market for months: does the current AI investment cycle represent a genuine technological revolution, or are we witnessing a bubble that will ultimately deflate?
The evidence supporting the bubble thesis has grown more compelling. Current AI spending levels imply revenue generation that would require virtually every enterprise on Earth to adopt AI solutions at prices far exceeding current willingness to pay. The hyperscalers are effectively building infrastructure for demand that may not materialize for years, if ever. Historical parallels to the telecom fiber optic boom of the late 1990s, where massive infrastructure overbuilding preceded a multi-year bust, are increasingly invoked by skeptical analysts.
The Case for Continued Investment
Defenders of current spending levels argue that the comparison to previous bubbles is misleading. Unlike the dot-com era, today's technology companies are generating substantial revenue and profits from their core businesses. The $735 billion in annual AI spending, while enormous, is being deployed by companies with combined annual revenues exceeding $2 trillion. The financial capacity to sustain this investment exists, even if it requires temporary margin compression.
Furthermore, AI capabilities are advancing at a pace that justifies continued investment. The leap from GPT-4 to current models represents genuine progress in reasoning, coding, and scientific research applications. If these capabilities continue to improve at current rates, the infrastructure being built today may prove essential for capturing the economic value that emerges over the next decade.
The Federal Reserve's policy trajectory adds another layer of complexity. With interest rates expected to remain elevated for longer than initially anticipated, the cost of capital for funding these massive investments has increased substantially. This makes the profitability threshold for AI projects higher and extends the payback period for infrastructure investments.
For traders looking to navigate this volatile environment with precision, Alphio AI's copy trading feature allows you to mirror the strategies of successful traders who specialize in technology sector rotation.

What Investors Should Watch in the Coming Months
The next several months will be critical for determining whether the current AI spending cycle can be sustained or whether a broader retrenchment is underway. Several key data points should be on every technology investor's radar.
First, fourth-quarter 2026 earnings reports from Microsoft, Alphabet, and Amazon will provide crucial insight into whether these companies plan to moderate their spending plans or double down on current trajectories. Any indication that growth in AI-related revenue is slowing relative to infrastructure investment would likely trigger additional selling pressure.
Second, venture capital funding trends for AI startups will signal whether private market investors share public market concerns about returns. A sustained decline in AI startup valuations or funding rounds would suggest that the ecosystem supporting current demand levels is weakening.
Third, enterprise AI adoption metrics will reveal whether the end customers that ultimately pay for all this infrastructure are actually deploying AI solutions at scale. Surveys suggest that while interest remains high, actual deployment and monetization of AI tools in production environments remains limited outside of a few narrow use cases.
Energy and Infrastructure Constraints
An underappreciated risk to the AI spending boom is the physical limitation imposed by power grid capacity. Training large AI models requires enormous amounts of electricity, and many data center markets are already facing power constraints. The time required to build new power generation and transmission infrastructure could become a binding constraint on AI capacity expansion, potentially forcing a natural slowdown in spending regardless of financial considerations.
How to Position Your Portfolio for the AI Spending Reckoning
For investors trying to navigate this uncertain landscape, several strategies may help manage risk while maintaining exposure to potential upside.
Diversification across the AI value chain remains essential. While Nvidia has been the standout performer, companies involved in data center construction, power infrastructure, cooling systems, and enterprise software may offer more attractive risk-reward profiles as the spending cycle matures. Companies that can generate revenue from AI without requiring massive capital expenditures themselves may be particularly well-positioned.
Active monitoring of capital expenditure guidance should become a core part of any technology investment process. The days when investors could safely ignore quarterly capex figures are over. These numbers now drive near-term stock performance and provide critical signals about management confidence in AI monetization timelines.
Defensive Positioning Strategies
Investors concerned about a broader tech correction might consider increasing exposure to defensive technology subsectors such as cybersecurity, which benefits from AI adoption without requiring comparable infrastructure investment. Companies with strong cash flow generation and reasonable valuations relative to their growth prospects may also offer better downside protection if the AI spending narrative continues to deteriorate.
The divergence between companies that sell AI infrastructure and those that consume it will be a key theme. While hyperscalers are spending billions, the companies actually monetizing AI applications, from healthcare to financial services, may ultimately capture more sustainable value with less capital intensity.
Consider using Alphio AI's automation tools to set conditional trading workflows that respond to earnings announcements and guidance changes without requiring constant manual monitoring.

Conclusion
The October 2026 tech selloff represents more than a routine market correction; it marks a potential inflection point in how investors evaluate the massive capital commitments being made in artificial intelligence. With Big Tech collectively spending approximately $735 billion annually on AI infrastructure, the gap between investment and demonstrable returns has become too wide to ignore.
Meta's disclosure of $825 billion in future commitments, combined with quarterly capital expenditures that now exceed operating cash flow, has forced a fundamental reassessment of how these investments should be valued. Nvidia, despite delivering extraordinary revenue growth, faces questions about demand sustainability as its hyperscaler customers confront their own financial constraints. Microsoft and Amazon continue to build at a pace that implies AI adoption levels that may take years to materialize.
For investors, the path forward requires balancing the genuine transformative potential of AI against the financial reality of funding these investments. The companies that survive this spending marathon will likely emerge as dominant players in a transformed economy. But not every current participant will make it to the finish line, and the journey is likely to involve more volatility like what we witnessed in October.
The coming quarters will reveal whether this selloff represents a buying opportunity in a secular growth trend or the beginning of a more sustained repricing of technology valuations. Either way, understanding the mechanics and magnitude of AI spending has become essential for anyone invested in the modern economy.
To stay ahead of market movements and execute trades with confidence, explore Alphio AI's conversational trading platform for real-time market insights and seamless trade execution.

FAQs
Why did tech stocks sell off in October 2026?
Tech stocks sold off primarily due to renewed concerns about the sustainability of massive AI infrastructure spending. Meta raised its 2026 capex guidance to $135-145 billion and disclosed $825 billion in future commitments, while the Nasdaq dropped 2.6% on October 23 as investors questioned whether these investments would generate adequate returns.
How much are Big Tech companies spending on AI?
Big Tech companies are collectively spending approximately $735 billion annually on AI infrastructure in 2026. Amazon leads at roughly $220 billion, Microsoft spends around $175 billion, and Meta has guided to $135-145 billion in capital expenditures for the full year.
Is the AI investment boom a bubble?
The debate continues, but concerns are growing. Current spending implies revenue generation that may exceed realistic near-term demand. However, unlike the dot-com era, today's tech companies have strong core businesses and substantial revenue to support investment. The outcome likely depends on whether AI capabilities continue improving rapidly enough to justify the enormous capital deployment.
What does Meta's spending mean for its stock?
Meta's Q3 2026 capex of $34.9 billion exceeded its operating cash flow, meaning the company is burning cash to fund AI investments. This raises concerns about future dilution or debt issuance. The stock dropped nearly 7% following the earnings report as investors recalculated the company's path to sustainable free cash flow generation.
How should investors position for AI spending volatility?
Investors should diversify across the AI value chain, monitor capital expenditure guidance closely, and consider defensive positioning in subsectors like cybersecurity that benefit from AI without comparable infrastructure spending. Companies with strong cash flows and reasonable valuations may offer better downside protection during periods of AI spending uncertainty.
Related articles
- Stock Market Surges After 2026 Midterms: What the Democratic Sweep Means for Your PortfolioThe stock market rallied after Democrats won the 2026 midterms. Discover what the election means for investors, tech stocks, and the S&P 500 outlook.
- Stock Market Surges After 2026 Midterms: What the Democratic Sweep Means for Your PortfolioThe stock market rallied after Democrats won the 2026 midterms. Discover what the election means for investors, tech stocks, and the S&P 500 outlook.
- Oil Prices Surge Above $105 Amid US-Iran Conflict: Energy Investment Opportunities in November 2026Oil prices climb past $105 as US strikes Iran's Qeshm Island. Discover energy investment opportunities, top oil stocks, and market outlook for November 2026.
- Amazon Stock Analysis: AWS 37% Growth Powers AMZN to New Highs in 2026Amazon (AMZN) stock analysis for August 2026. Discover how AWS's record 37% growth and AI investments are driving Amazon's $200B quarterly revenue milestone.
- NVIDIA Stock Earnings August 2026: AI Chip Leader's Q2 Preview & Investment OutlookNVIDIA reports Q2 earnings August 26, 2026. Analysts expect 2B revenue. Get expert analysis on NVDA stock, AI data center growth, and price targets.
- Nvidia Stock Earnings August 2026: AI Chip Leader's Q2 Preview & Investment OutlookNvidia's Q2 FY2027 earnings on August 26, 2026: AI chip demand surge, Blackwell ramp, and price targets. Wall Street expects $93-95B revenue.