SMCI Stock Analysis August 2026: Margins Double, Guidance Soars to $72 Billion
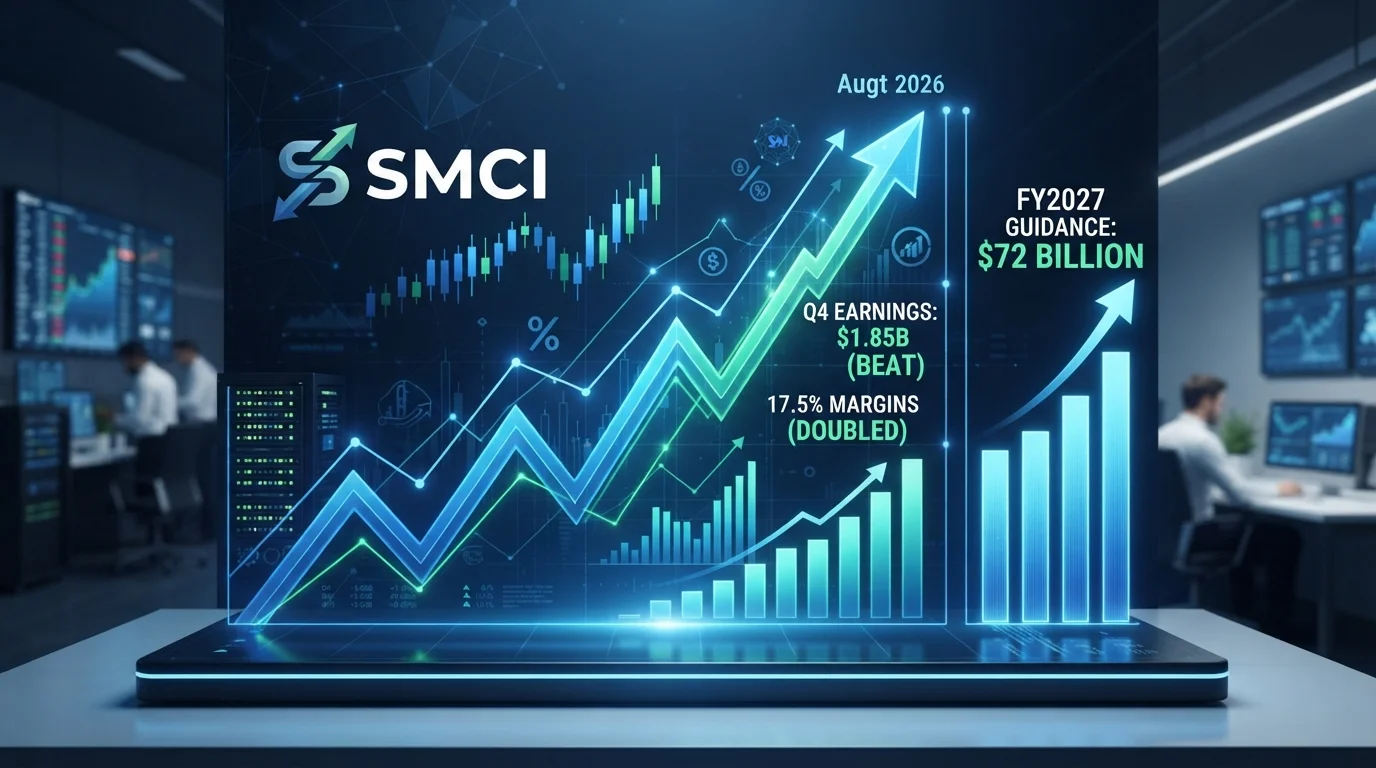
Super Micro Computer (SMCI) stock analysis for August 2026. Q4 earnings beat expectations with margins doubling to 17.5%. Fiscal 2027 guidance hits $72 billion.
Key Takeaway
Super Micro Computer (NASDAQ: SMCI) has emerged as one of the most compelling stories in the AI infrastructure space following its fiscal Q4 2026 earnings report. The company delivered a quarter that exceeded expectations on the bottom line, with adjusted earnings per share of $1.70 beating Wall Street estimates despite revenue coming in slightly below consensus at $11.12 billion versus the expected $11.26 billion. What truly caught investors' attention was the dramatic margin expansion, with gross margins nearly doubling from 9.5% a year ago to 17.5% in the most recent quarter.
This margin recovery represents a fundamental inflection point for Supermicro's business model. The company has successfully shifted its customer mix toward higher-margin enterprise clients while benefiting from broader adoption of its Data Center Building Block Solutions architecture. Management's fiscal 2027 revenue guidance of $65 billion to $72 billion signals confidence in sustained AI infrastructure demand, with the company entering the new fiscal year with a record backlog and more than $60 billion in new orders generated during fiscal 2026.
For investors evaluating SMCI stock at current levels, the investment thesis has evolved from a pure-play AI infrastructure growth story to one that combines top-line expansion with meaningful margin improvement. The stock trades at a significant discount to its 52-week highs, potentially offering an attractive entry point for those willing to navigate the ongoing export-control review and negative operating cash flow dynamics that come with scaling for hypergrowth.
SMCI Q4 2026 Earnings: A Turning Point
Revenue Growth Remains Robust
Super Micro Computer reported fourth-quarter revenue of $11.12 billion, representing a remarkable 93% year-over-year increase. While this figure fell slightly short of Wall Street's $11.26 billion estimate, the magnitude of growth underscores the company's central position in the AI server buildout. Full-year fiscal 2026 revenue reached approximately $40 billion, cementing Supermicro's status as one of the fastest-growing companies in the technology sector.
The revenue composition reveals important insights about the company's market positioning. Nvidia GPU-based platforms continue to drive the majority of demand, reflecting the broader industry trend toward accelerated computing for artificial intelligence workloads. However, Supermicro's architectural approach, which emphasizes modular, scalable data center solutions, has enabled the company to capture value across multiple customer segments from hyperscale cloud providers to enterprise data centers.
CEO Charles Liang emphasized that the company generated more than $60 billion in new orders during fiscal 2026, providing substantial visibility into future revenue. This order momentum, combined with the record backlog entering fiscal 2027, suggests that Supermicro's growth trajectory remains intact despite the quarterly revenue miss.
Margin Expansion: The Real Story
The most significant development in Supermicro's Q4 results was the dramatic improvement in profitability metrics. Gross margins expanded to 17.5% from just 9.5% in the year-ago quarter, representing more than an 800 basis point improvement. This margin recovery transformed what could have been a disappointing quarter into an earnings beat, with adjusted EPS of $1.70 exceeding consensus expectations.
Several factors contributed to this margin expansion. The company has successfully shifted its customer mix toward higher-margin enterprise clients who value Supermicro's engineering capabilities and custom solutions. Additionally, the broader adoption of the company's Data Center Building Block Solutions architecture has enabled greater standardization and operational efficiency. The adjusted gross margin guidance of 15% to 17% for the upcoming quarter represents a significant premium compared to the 8.2% to 8.4% range projected just three months ago.
This margin inflection suggests that Supermicro is successfully navigating the transition from a commodity server vendor to a solutions provider with genuine pricing power. For investors, the implications are substantial. If the company can maintain gross margins in the mid-to-high teens while continuing to grow revenue at a rapid clip, the path to sustained profitability becomes much clearer.
AI Infrastructure Demand: The Growth Engine
Data Center Buildout Accelerates
The global data center infrastructure market is experiencing unprecedented expansion as enterprises and cloud providers race to deploy AI capabilities. Supermicro has positioned itself at the center of this buildout, offering high-performance computing solutions optimized for AI workloads. The company's liquid cooling technologies, high-density server designs, and energy-efficient architectures address the critical challenges facing modern data centers.
For investors seeking exposure to the AI infrastructure theme without taking on the valuation risk associated with semiconductor leaders like Nvidia, consider using Alphio AI's copy trading feature to mirror successful traders and smart money wallets who are positioning in this space.
The competitive landscape in AI servers has intensified, with traditional server vendors like Dell and HPE investing heavily to capture market share. However, Supermicro's first-mover advantage in liquid cooling and its close partnerships with Nvidia have created meaningful barriers to entry. The company's ability to deliver complete rack-scale solutions, rather than just individual servers, provides a differentiated value proposition for customers building large-scale AI clusters.
Fiscal 2027 Guidance: Ambitious but Achievable
Management's guidance for fiscal 2027 revenue between $65 billion and $72 billion represents approximately 60% to 80% growth over fiscal 2026 levels. This ambitious outlook reflects confidence in the sustainability of AI infrastructure demand and Supermicro's ability to capture an increasing share of the market. The guidance also implies continued margin improvement, as the company expects to leverage its scale and operational improvements.
Several analysts have raised their estimates following the earnings report, with Wall Street consensus now projecting EPS growth of 22.1% in fiscal 2026 followed by 41.4% growth in fiscal 2027. The current price target of $39.21 represents approximately 21% upside from recent trading levels around $32, though some bullish analysts see potential for 55% upside if the company executes on its guidance.
Investment Risks and Considerations
Cash Flow and Capital Intensity
Despite the impressive revenue growth and margin expansion, Supermicro's fiscal 2026 produced negative operating cash flow of $6.8 billion. This cash consumption reflects the company's aggressive investment in inventory and capacity to meet surging demand. While this capital intensity is typical for companies experiencing hypergrowth, it creates vulnerability if demand were to slow unexpectedly.
The working capital requirements of the AI server business are substantial, with long lead times for key components like GPUs and memory. Supermicro must maintain significant inventory positions to ensure timely delivery to customers, tying up capital that could otherwise be returned to shareholders or invested in research and development. Investors should monitor quarterly cash flow trends for signs of improvement as the company's scale increases.
Alternatively, explore agentic trading to automate your portfolio management with AI-powered strategies that can help navigate volatile growth stocks.
Regulatory and Governance Concerns
The board is currently conducting an independent review of certain transactions related to export-control issues, and the Q4 results remain preliminary and unaudited. This ongoing review creates uncertainty and could potentially result in restatements or regulatory actions. Investors should be aware that the final audited results may differ from the preliminary figures reported.
Additionally, the company's rapid growth has put pressure on internal controls and governance structures. The transition from a niche server vendor to a $40+ billion revenue company in just a few years has required significant organizational changes. Management's ability to scale operations while maintaining proper controls will be critical to long-term success.
Competitive Positioning in AI Infrastructure
Differentiation Through Innovation
Supermicro's competitive moat rests on several key differentiators. The company's liquid cooling technologies enable higher-density deployments than traditional air-cooled solutions, addressing the thermal challenges posed by high-power AI chips. This capability has become increasingly valuable as data center power densities have risen dramatically with the deployment of Nvidia's latest GPU generations.
The Data Center Building Block Solutions architecture provides customers with modular, scalable infrastructure that can be customized for specific workloads. This approach contrasts with the one-size-fits-all solutions offered by many competitors, allowing Supermicro to capture premium pricing for engineered solutions. As AI workloads become more diverse, from training large language models to deploying inference at the edge, the flexibility of Supermicro's architecture becomes a significant competitive advantage.
Partnership Ecosystem
Supermicro's close partnership with Nvidia has been instrumental to its success in the AI server market. As one of the leading providers of Nvidia GPU-based systems, Supermicro benefits from early access to new chip generations and joint engineering efforts. This relationship has created a virtuous cycle, where Supermicro's engineering capabilities attract Nvidia's partnership, which in turn drives customer demand for Supermicro solutions.
The company has also developed partnerships with other key technology providers, including AMD for CPU solutions and various networking vendors for high-speed interconnects. This ecosystem approach enables Supermicro to offer complete, optimized solutions rather than just individual components.
Valuation and Price Target Analysis
Current Valuation Metrics
At current trading levels around $32, SMCI stock trades at a significant discount to its 52-week highs above $60. The forward price-to-earnings ratio based on fiscal 2027 estimates appears reasonable for a company with projected revenue growth of 60% to 80%. However, valuation must be considered in the context of the company's cash flow dynamics and regulatory uncertainties.
Wall Street analysts maintain a consensus price target of approximately $37.81, implying roughly 18% upside from current levels. Bullish analysts see potential for the stock to reach $50 or higher if the company executes on its fiscal 2027 guidance and continues to expand margins. The wide range of price targets reflects uncertainty about the sustainability of current growth rates and the resolution of the ongoing regulatory review.
For those looking to set up conditional trading strategies around earnings events, Alphio's automation features allow you to set conditional workflows that execute based on price movements or news events.
Comparison to Peers
When compared to other AI infrastructure plays, Supermicro offers a unique risk-reward profile. The stock trades at a lower valuation multiple than Nvidia, reflecting its position further down the value chain and its lower margins. However, Supermicro's growth rate exceeds that of many semiconductor companies, and its margin expansion story provides a catalyst for multiple expansion.
Dell and HPE trade at lower valuations but are growing significantly slower and face greater exposure to declining legacy server markets. Pure-play data center REITs offer exposure to AI infrastructure buildout but lack the technology upside of server vendors. Supermicro occupies a middle ground, offering pure-play AI exposure with reasonable valuation metrics.
Conclusion
Super Micro Computer's Q4 2026 earnings report represents a significant inflection point for the company and its shareholders. The dramatic margin expansion from 9.5% to 17.5% demonstrates that Supermicro is successfully transitioning from a commodity server vendor to a high-value solutions provider. Combined with fiscal 2027 revenue guidance of $65 billion to $72 billion, the investment thesis has evolved from pure growth to growth with profitability.
For investors considering SMCI stock at current levels around $32, the risk-reward profile appears favorable. The stock trades at a discount to analyst price targets and well below its 52-week highs, potentially offering an attractive entry point. However, investors must remain cognizant of the ongoing regulatory review, negative cash flow dynamics, and the inherent volatility of a hypergrowth technology stock.
The AI infrastructure buildout shows no signs of slowing, and Supermicro's central position in this trend provides substantial visibility into future growth. For those seeking to capitalize on the AI revolution through infrastructure plays, SMCI offers compelling exposure with improving fundamentals and reasonable valuation metrics.
Ready to start trading SMCI and other AI infrastructure stocks? Execute trades seamlessly via chat with Alphio's conversational trading interface, designed to make complex trading decisions simple and intuitive.
Whether you're looking to build a position in SMCI ahead of continued AI infrastructure growth or diversify across the semiconductor and server ecosystem, having the right tools at your disposal can make all the difference in capturing this transformative investment opportunity.
FAQs
What was Super Micro Computer's Q4 2026 revenue?
Super Micro Computer reported Q4 2026 revenue of $11.12 billion, representing a 93% year-over-year increase. While this slightly missed Wall Street's estimate of $11.26 billion, the company exceeded expectations on adjusted earnings per share with $1.70 versus consensus estimates.
How much did SMCI's gross margins improve in Q4 2026?
SMCI's gross margins expanded dramatically from 9.5% in the year-ago quarter to 17.5% in Q4 2026, representing an 800+ basis point improvement. This margin expansion was driven by a shift toward higher-margin enterprise customers and broader adoption of the company's Data Center Building Block Solutions architecture.
What is Supermicro's fiscal 2027 revenue guidance?
Management guided for fiscal 2027 revenue between $65 billion and $72 billion, representing approximately 60% to 80% growth over fiscal 2026. This ambitious guidance reflects confidence in sustained AI infrastructure demand and the company's record backlog entering the new fiscal year.
What are the main risks facing SMCI stock?
Key risks include negative operating cash flow of $6.8 billion in fiscal 2026 due to inventory and capacity investments, an ongoing independent board review of export-control related transactions, and intense competition from Dell and HPE in the AI server market. The preliminary nature of Q4 results also creates uncertainty until audited figures are released.
What is Wall Street's price target for SMCI stock?
Wall Street analysts maintain a consensus price target of approximately $37.81 for SMCI stock, implying roughly 18% to 21% upside from current trading levels around $32. Some bullish analysts see potential for 55% upside if the company executes on its fiscal 2027 guidance and continues expanding margins.